
Hello my dears,
"On land, on water and in the air" reminds me of the afternoon show from the 80s in which candidates
candidates had to solve creative and sporting tasks on self-made vehicles. I don't think anyone really believed in drones and robots at the time. Nothing new today.
I'm often asked what defense value you would invest in right now.
When I then give the answer:
"Ideally in several"
Then most people think of an ETF. But I'm not talking about an ETF at all. Because this brings me back to my beloved bucket suppliers.
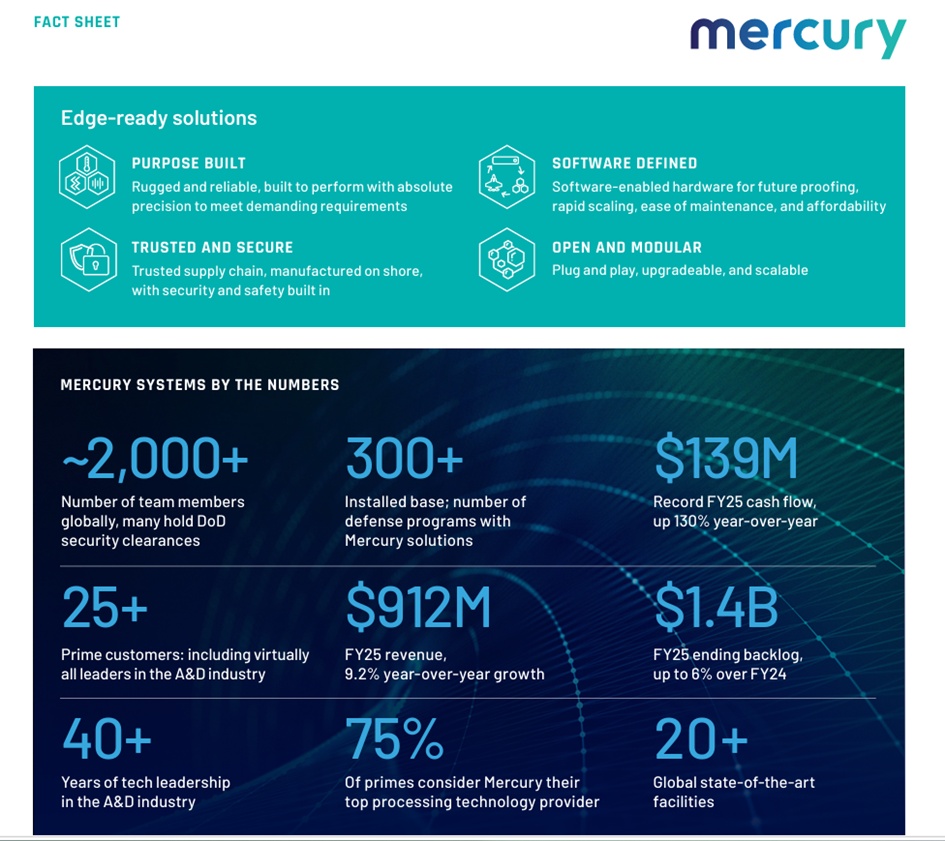
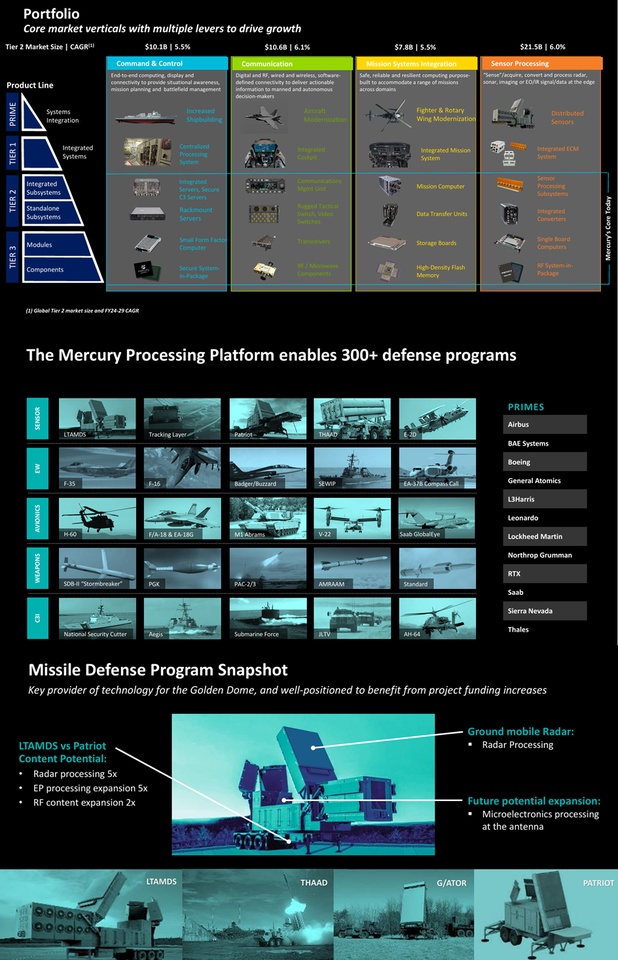
And today I would like to introduce you to a company that is involved in almost all the big ones. And without its technology, no radar or modern defense system would work.
To name just a few of its customers:
Airbus, BAE Systems, Boeing, General Atomics, L3Harris, Leonardo, Lockheed Martin, Northrop Grumman, RTX, Saab, Sierra Nevada, Thales
Dear all, do you know this blade supplier, and what do you think of my thesis?
"With only one company, profit from the success of many others"
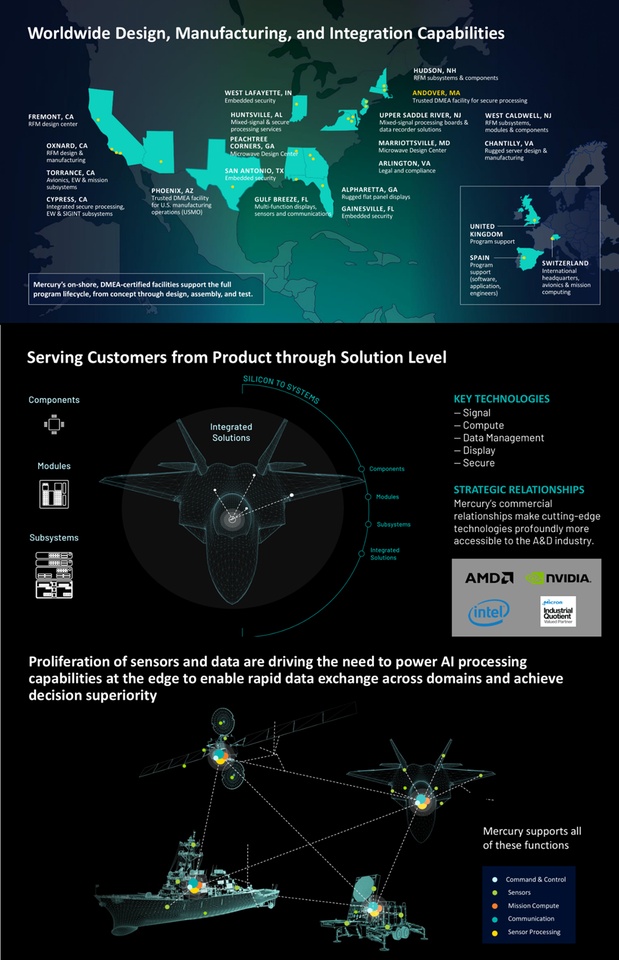
Mercury Systems, Inc. is a technology company that provides mission-critical processing solutions at the edge where signals and data are collected to address the most pressing challenges in aerospace and defense. The Mercury Processing Platform covers the full spectrum of signal processing - from radio frequency (RF) front-end to human-machine interface - to turn data captured in remote and harsh environments into critical decisions. The company offers products and customized solutions from the silicon level to the system level, including components, modules, subsystems and systems. Its products and solutions are used in a wide range of applications, including sensor and radar processing, electronic warfare, avionics, weapon systems and command, control, communications and intelligence (C4I). The company serves leading defense contractors in the United States and Europe, the U.S. government, original equipment manufacturers (OEMs) and commercial aerospace companies.
Number of employees: 2,117
Mercury's products and solutions are used in more than 300 programs and in 35 countries, enabling a wide range of applications in mission computing, sensor processing, command and control, and communications. Mercury is headquartered in Andover, Massachusetts, and has more than 20 locations worldwide.
Land, sea, air, space and cyberspace - Mercury has a proven solution
They bring some of the most advanced technologies to every corner of the world and into space. Mercury solutions are integrated into more than 300 commercial and defense programs in aerospace, transportation, military, security and intelligence in Land-, See-, Luft-, Weltraum- and Cyberspace-Bereichen integrated
Addressable market Mercury serves a large and growing market with favorable tailwinds and multiple opportunities to expand market presence TIER 2 MARKET SIZE AND CAGR(1)
- 50.0 billion
$ 5,8 % Global Tier 2 market
- 21.3 billion $ 5,2% USTier 2 market
- 28.7 billion $ 6,3 % Rest of the world Tier 2 market
STRONG DEFENSE DEMAND SIGNALS
- Increased global defense spending: Western nations commit to significant defense spending for future deployments and evolving threats, led by US spending with renewed emphasis by European partners
- The prioritization of capability modernization: Capital spending is focused on procuring new platform and weapon systems as well as upgrades to existing systems with advanced platform/mission management, C2, communications and sensor capabilities.
- Further "electronification" of systems Spending on electronic systems is expected to outpace overall market growth, reflecting continued growth in electronic content and capability over the previous generation
Mercury benefits from market expenditure and purchasing dynamics
CHANGE IN BUYING DYNAMICS
- Outsourcing from tier 2/3 to scaled tier providers in the A&D supply chain has evolved since the mid-1990s, from significant in-house development and production of tier 2/3 content at primes to today, where scaled tier 2/3 providers are also able to deliver to prime and tier 1 companies.
- End customer desire to "unstack" primary content End customers (government) are increasingly seeking to minimize the primary "vendor lock-in" effect by also directly accessing scaled tier 2/3 vendors and demanding open system architectures
- The desire for faster upgrades is driving open systems. End customers are increasingly looking to utilize open systems and their capabilities to meet the requirements for faster upgrade cycles in electronics and the growing demand for more processing capacity.
789c4662-645c-4392-8f96-2d206d660830
March 12, 2026 at 4:14 pm EDT
Mercury Systems acquires SolderMask to support higher production rate
2026-05-05 22:01Pressemitteilung
Mercury Systems reports fiscal Q3 2026 results
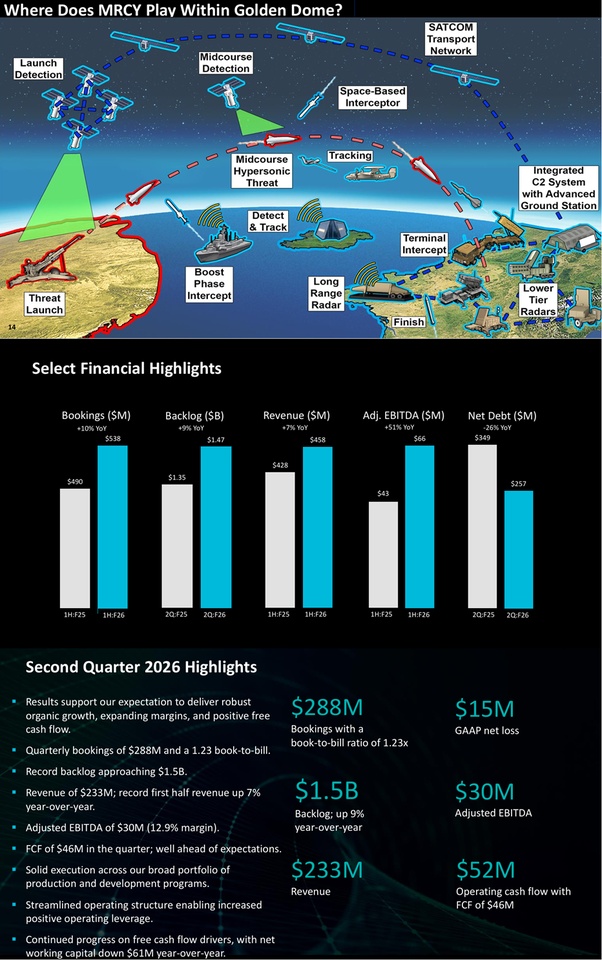
- Record bookings in the third quarter 26 increased year-over-year up 73.7% year-over-year; book-to-sales of 1.48
- Record backlog of approximately $1.6 billion; An increase of 17.9% year-over-year
- Q3 FY26 sales of 236 million US dollars; Organic plus by 11.5% year-on-year
- GAAP net loss of $3 million; and Adjusted EBITDA of $36 million, an increase of 46.2% year over year
Mercury Systems Reports Third Quarter Fiscal 2026 Results
MRCY_2025_10k_Wrap_F_TSG D14.indd
Mercury vergab Aufträge für US-Raumfahrt- und strategische Waffenprogramme
2025-05-01 22:15
Press Release
Maritime autonomy pioneer impresses in Q3 with AI-driven robotic vessels!
15,05,2026
Mercury Systems develops AI-controlled robotic ships for defense and research purposes. On May 5, the company significantly exceeded market expectations with its Q3 figures, fueled by a new major order from the US Navy worth USD 420 million. Gross margins improved to 38% thanks to more efficient series production of the "Swift Path" drones. With a cash position of USD 150 million, future growth in fleet production is secured. The company is establishing itself as the market leader for maritime surveillance solutions.
Mercury Systems, an aerospace and defense supplier
Mercury Systems Inc (ISIN: US5893781089) is a supplier of hardware and software solutions for the architecture of safety-critical applications, particularly in aerospace and defense. Its products include processor modules, avionics mission computers and ruggedized servers. The company was founded in 1981. The shares have been listed on the Nasdaq since 1998.
Thanks to modular, open and software-defined platforms that are specially optimized for demanding applications at the edge, Mercury Systems is actively working on the modernization of defence electronics, thus creating the basis for flexible and scalable solutions. Technological expertise is also acquired through takeovers. Mercury Systems has already made over 15 acquisitions since 2014.
Geographical distribution of sales:
2025 (USD)
U.S.A. 870 million
Europe 62.83 million
Eliminations -20.94 million
🧑💻 Short Juan summary - Mercury Systems
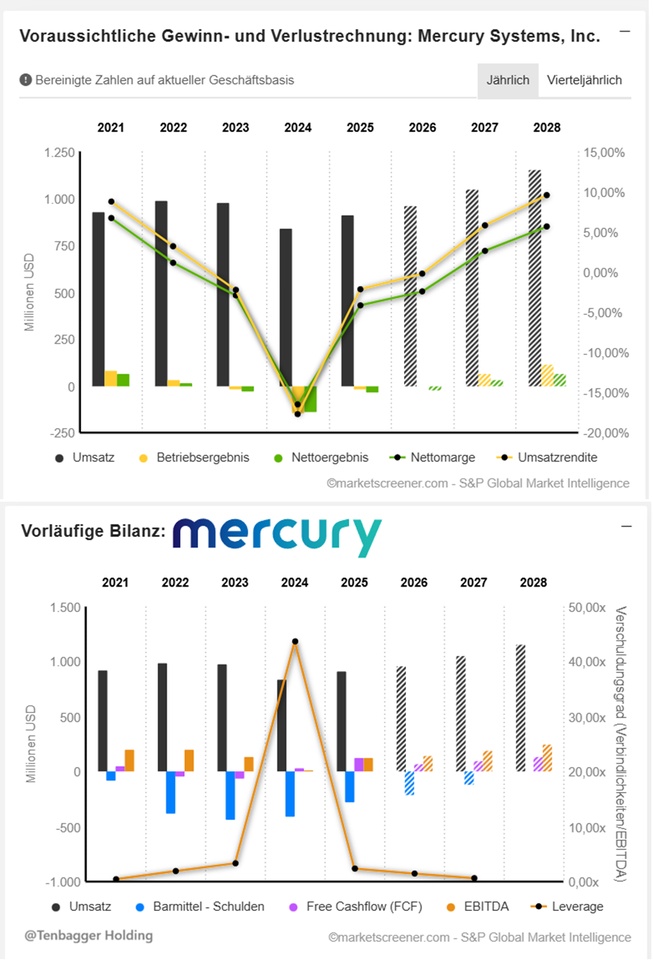
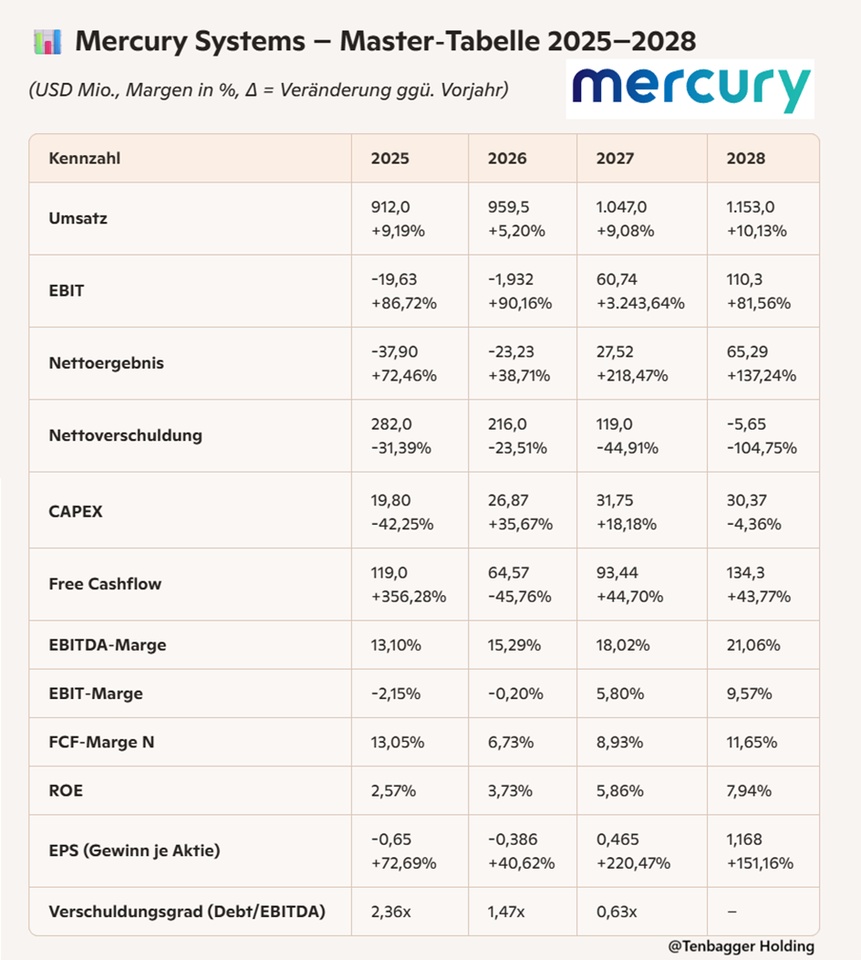
Mercury is visibly stabilizing. Sales are growing solidly again, margins are slowly improving and free cash flow is turning strongly positive. Debt is being reduced year by year, practically neutral until 2028. Earnings and EPS jump significantly upwards from 2027 - classic turnaround trajectory. Not yet a high-flyer, but the direction is right and the risk is decreasing noticeably.
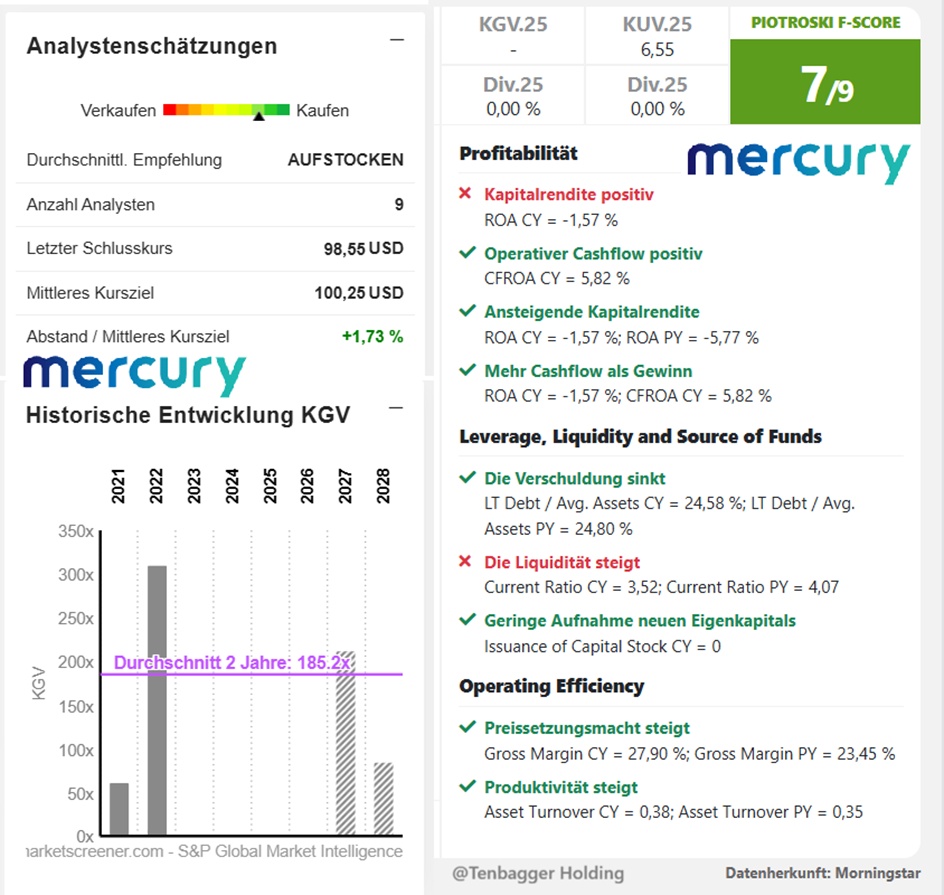
Market value 5,917
Number of shares (in thousands) 60,043
Date of publication 11.08.2025
🧑💻 Short Juan conclusion - Mercury Systems valuation
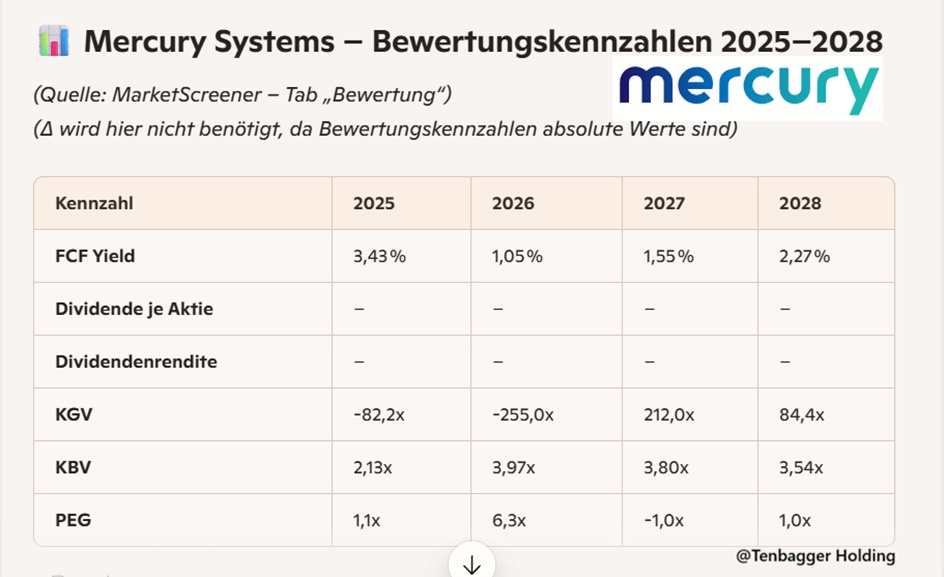
Mercury still looks like a classic turnaround case in 2025-2026: FCF yield fluctuates, P/E ratio is distorted due to negative earnings and not really meaningful. From 2027, the picture stabilizes significantly - the valuation normalizes, PEG becomes meaningful again and FCF yield increases. No dividend, so complete focus on re-investment and strengthening the balance sheet. In sum: Valuation still volatile, but the trend is clearly pointing towards recovery.
🧑💻 Combined Juan conclusion - financials + valuation (Mercury Systems)
Mercury shows a clean turnaround profile from 2025 onwards: stable double-digit sales growth, margins increasing year on year and free cash flow turning strongly positive. The balance sheet will be visibly relieved - net debt will fall to practically zero by 2028. Earnings and EPS jump significantly from 2027, confirming the operating rebound.
On the valuation side, the picture remains distorted in 2025-2026: negative earnings → unusable P/E ratios and a PEG that is hardly meaningful. From 2027, the valuation will normalize, FCF yield will rise again and the risk/reward profile will become much clearer. No dividend, focus remains on re-investment and strengthening the balance sheet.
Bottom line: Clear upward trend in operational terms, strong improvement in balance sheet, valuation still volatile - but real re-rating potential from 2027.
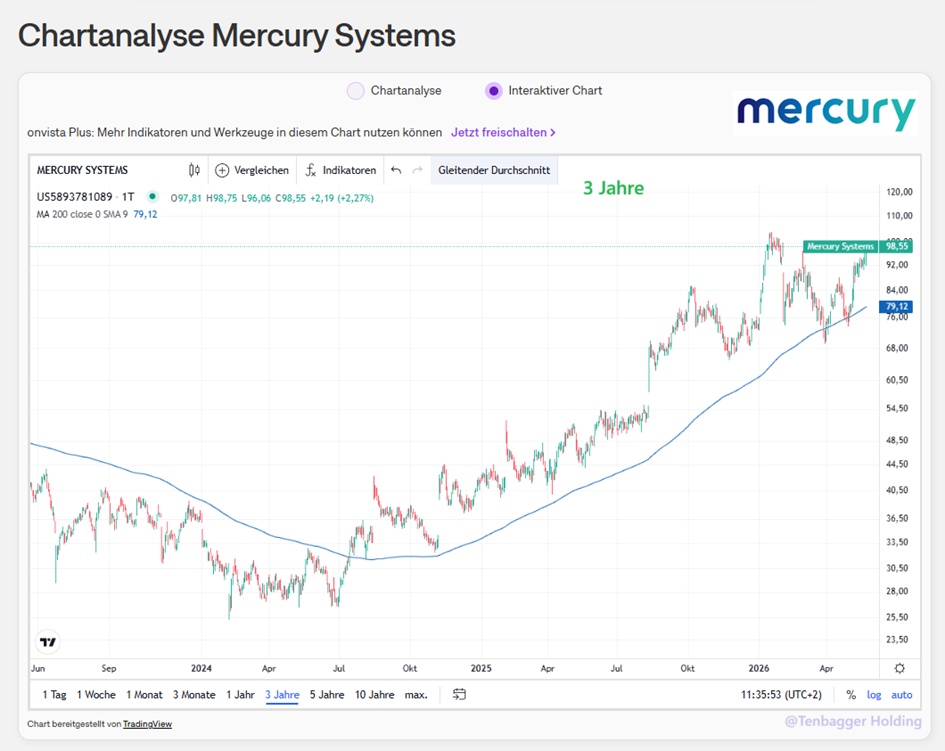
Performance
1 week +7.91 %
1 month +29.67 %
6 months +43.50 %
1 year +106.97 %
3 years +133.97 %
26,05,2026
today, 15:14:18 -
gettex (EUR)
86,72 EUR


