

Hello my dears,
I usually don't miss out on a visit to Silicon Valley to look for new companies.
But Juan has really shown his flair with his latest companies.
And has done a great job.
That's why he more than deserved the trip.
My dears, and with the company he brought us back from the trip. He shows once again that he knows his trade.
Here is his thought:
Seize opportunities in major corrections.
Dear ones, what do you think of Juan's thought?
We look forward to your comments on Rambus $RMBS (-0.25%)
AI-driven memory chip specialist slips after forecast disappointment - opportunity or exaggerated expectation?
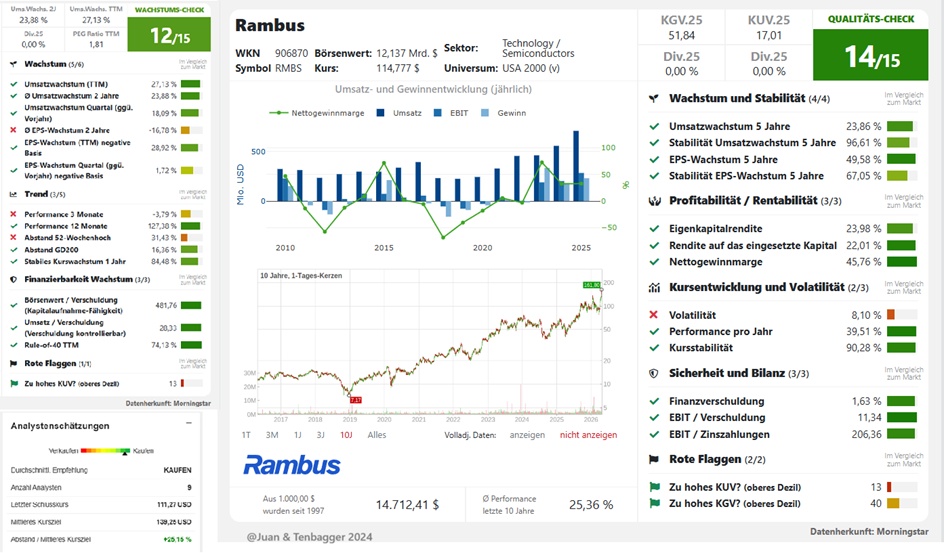
Rambus shares may have taken a knock after a strong rally, but experts see the price slide following the latest figures as a healthy correction rather than a genuine trend reversal. As an indispensable trailblazer for AI data centers, the company remains in an excellent fundamental position, but in view of its ambitious valuation, investors need to have good nerves for short-term fluctuations. Share price slide despite solid figures: Analysts remain bullish.
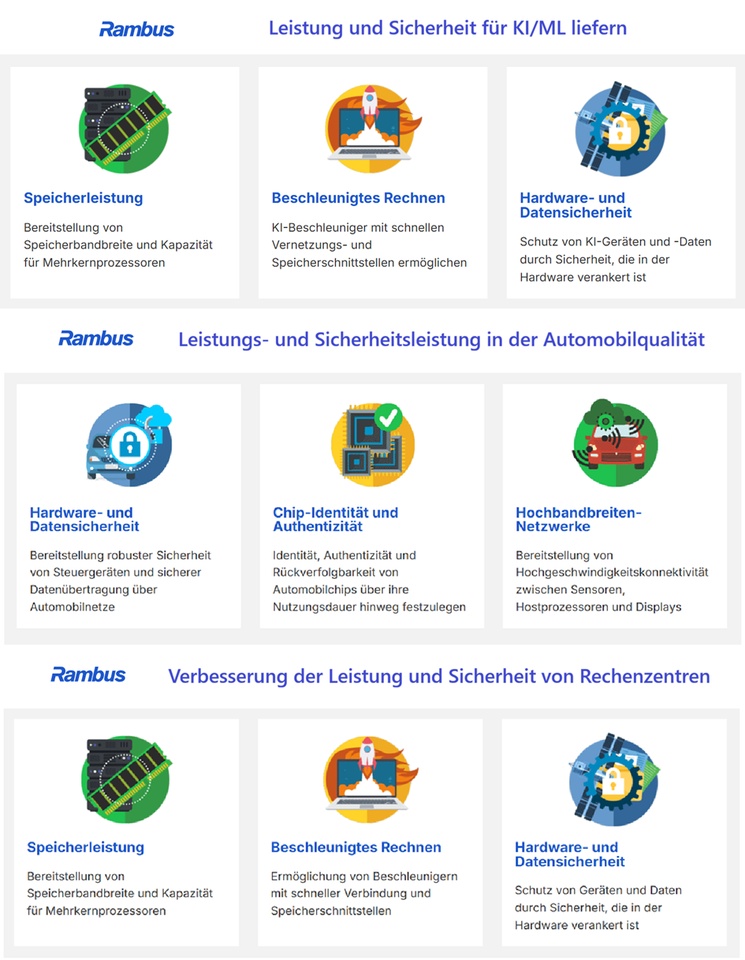
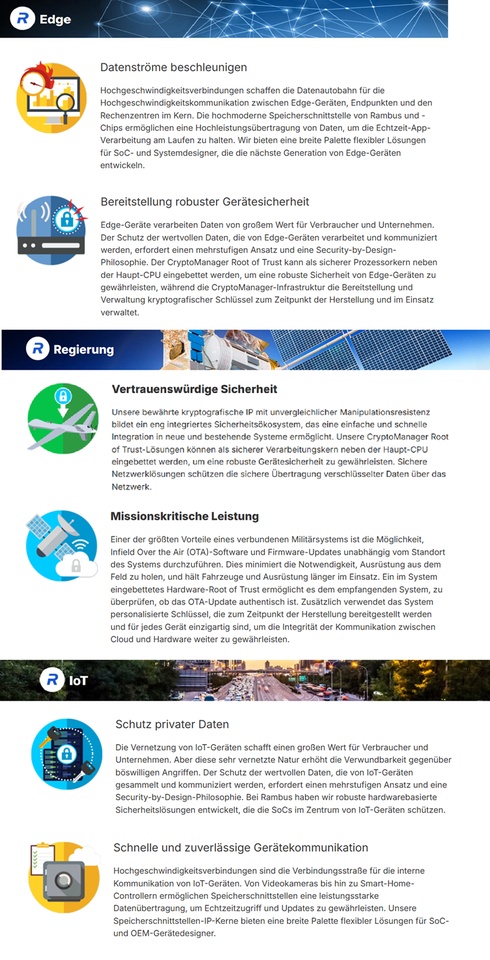
Rambus Inc. is a provider of chips, silicon-based intellectual property (IP) and innovations that address the fundamental challenges of data acceleration and enable critical performance improvements for data centers and other growing markets. The company offers a balanced and diverse portfolio of chip, silicon IP and patent licensing solutions. Its Rambus Double Data Rate (DDR) memory interface chips for server memory modules enable higher bandwidth and expanded capacity in enterprise and cloud servers. The portfolio includes DDR5 and DDR4 memory interface chipsets. The DDR5 chipset solution includes the Registering Clock Driver (RCD), Serial Presence Detect Hubs (SPD Hub) and Temperature Sensors (TS). Rambus Silicon IP includes interface and security IP solutions for the transmission and protection of data in advanced data center, government and automotive applications. The company sells memory interface chips directly and indirectly to memory module manufacturers and original equipment manufacturers (OEMs).
Number of employees: 791
Rambus Inc. – Rambus berichtet über die Finanzergebnisse des ersten Quartals 2026
Rambus Inc. – Rambus ermöglicht energieeffiziente KI-Plattformen mit SOCAMM2 Servermodul-Chipsatz
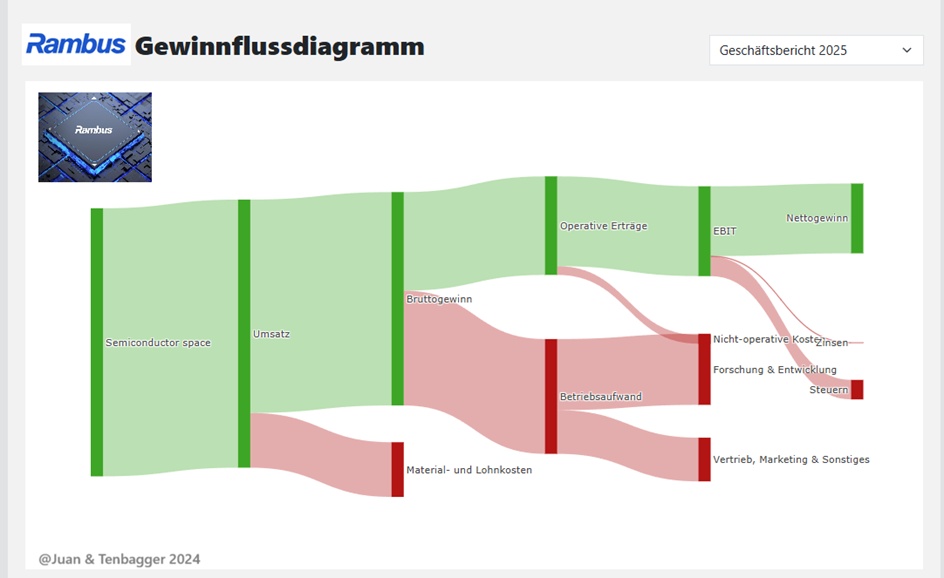
Geographic sales distribution:
2025 (USD)
South Korea 329 million
Singapore 164 million
USA 124 million
Other 90.45 million
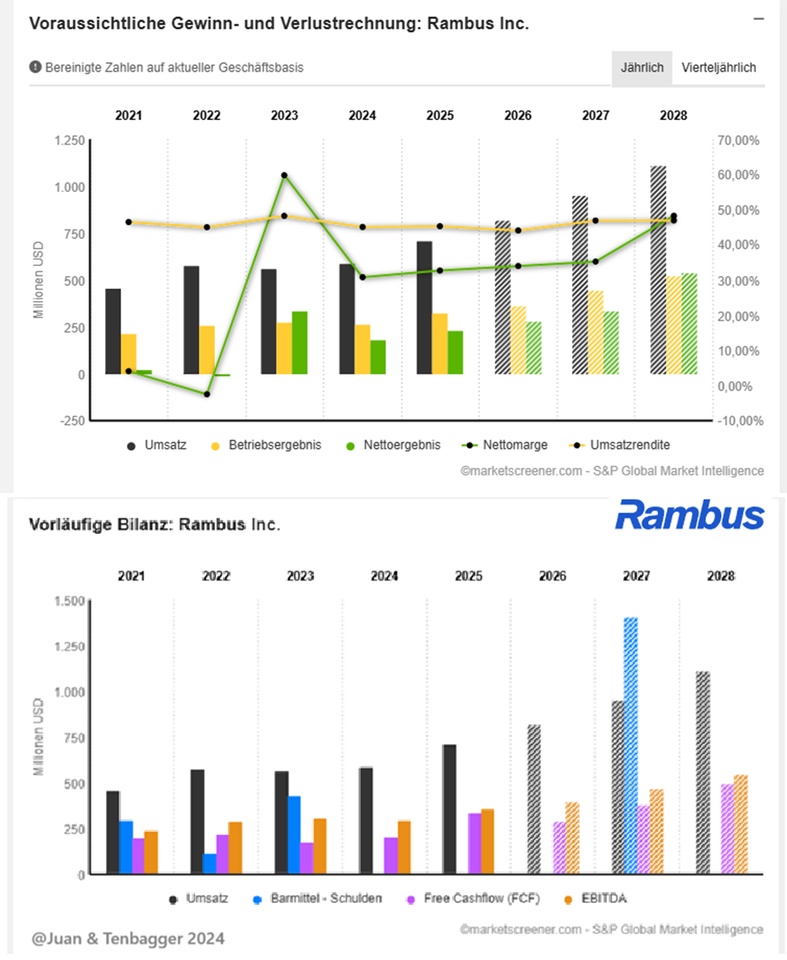
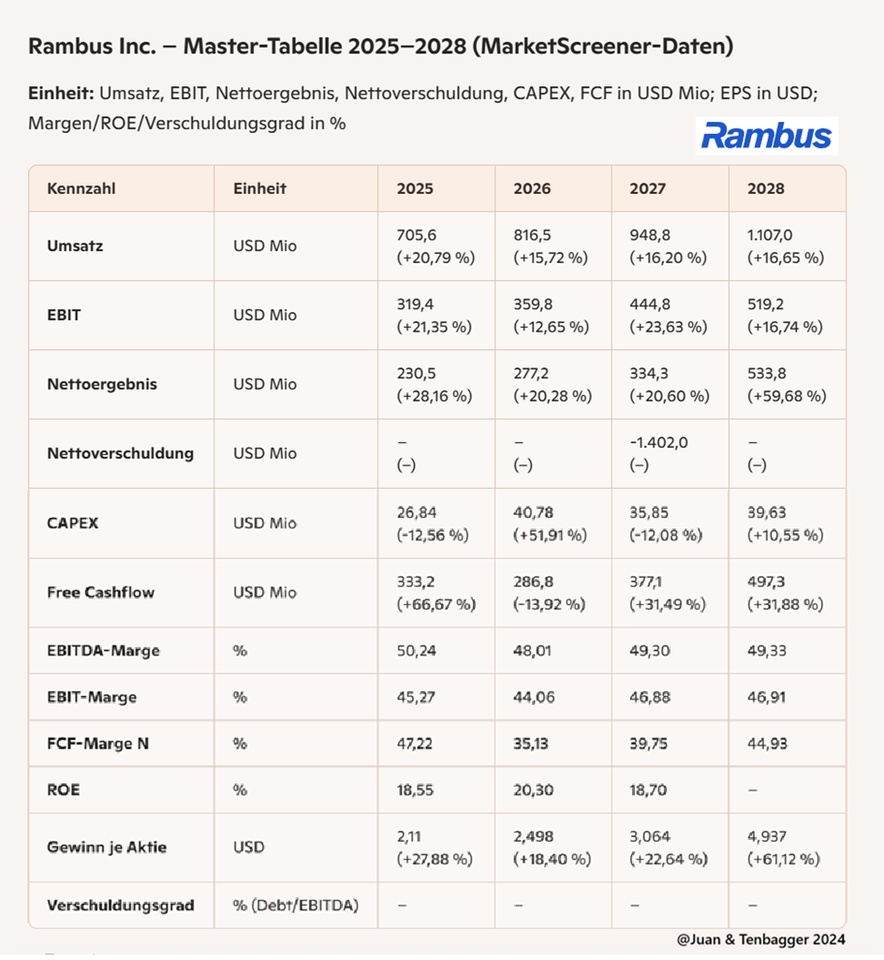
Juan's brief conclusion on Rambus (2025-2028)
"Rambus delivers a clean, powerful numbers picture - just the kind of structure I like."
Growth remains stable in double digits: Sales and EBIT are clearly increasing year on year, with no dropouts. This is typical for a company with strong pricing power and high demand in the semiconductor IP segment.
Margins at premium level: EBIT margin constant >44 %, FCF margin strong and 2028 back towards 45 %. That is absolute quality class.
Free cash flow impresses: 2025-2028 Rambus shows an FCF machine that generates solid cash every year - 2028 almost 500 million USD.
EPS explosion 2028: The jump to USD 4.94 (+61 %) is a real highlight and shows how strong the operating leverage is.
Net cash position: 2027 with USD -1.402 bn Net cash - a rare luxury in the industry.
Low risk, high quality: No debt, strong margins, predictable growth - Rambus is a structural winner in the memory and security IP market.
Juan concludes: "Rambus looks like a company that does its homework: strong growth, strong margins, strong cash flow. No show, just solid execution. Definitely an exciting candidate for long-term quality investors."
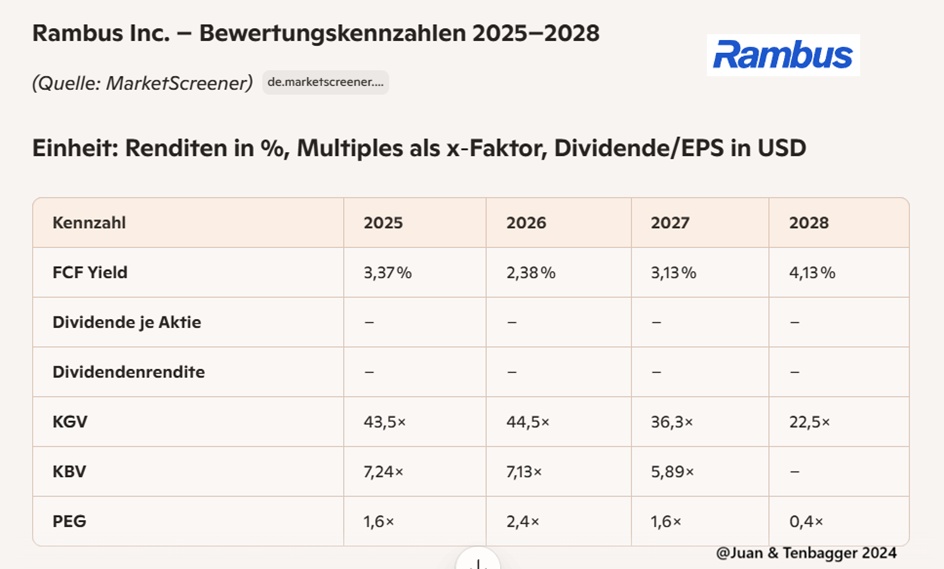
Juan's conclusion on the valuation ratios (Rambus 2025-2028)
"Valuation-wise, Rambus looks like a quality tech stock that is just starting to be valued more efficiently."
P/E ratio falls massively from 2027/2028: From 43-44× in 2025/26 down to 22,5× in 2028. This is a clear indication that earnings growth is rising faster than the price.
PEG 2028 extremely attractive: A PEG of 0.4× is almost a gift for a structural growth stock. This signals: The market is not fully pricing in growth.
FCF yield is steadily improving: From 3,37 % to 4,13 % - not spectacular, but solid and growing. Absolutely strong for a high-margin IP player.
No dividend - but that's good: Rambus is putting everything into growth, buybacks and IP development. This is the right capital allocation for a high-margin compounder.
P/B ratio sinks towards fair: From 7,24× to 5,89× - shows that the valuation is not overheating despite rising profits.
Juan conclusion:
"Rambus is getting cheaper every year, even though earnings are exploding. This is exactly the kind of valuation profile that enables long-term outperformance. When a quality company gets cheaper while growing faster - that's when it gets really exciting for investors."
Tenbagger probability matrix
- Rambus Inc.
(Based on your MarketScreener data 2025-2028 and our standardized Juan scoring)
As always, I'll build the matrix for you compact, clear - and of course in the typical Juan style.
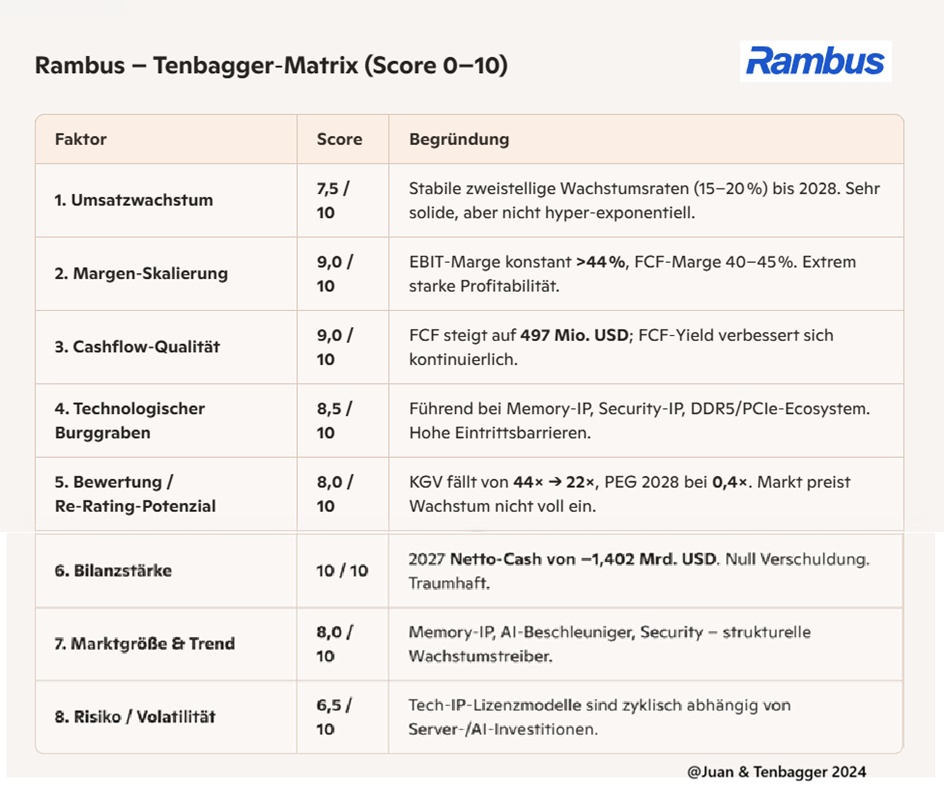
⭐ Overall score: 8.3 / 10
🎯 Realistic Tenbagger probability until 2033: 25-35 %
Juan's conclusion on the Tenbagger opportunity
"Rambus is a quality compounder with premium margins, net cash and a valuation profile that is becoming increasingly attractive. Not a classic high-risk moonshot - rather a quiet, efficient stock that can stack up huge returns over the years."
- The Margins are world class.
- The balance sheet is outstanding.
- The valuation becomes more favorable every yearalthough profits are exploding.
- The growth is stablebut not hyperbolic - therefore not a 50-60% score, but a realistic 25-35%.
"If Rambus continues to deliver like this and the AI memory boom continues, this could be a real long-distance tenbagger."
Performance:
1 week -14.59 %
1 month +21.91 %
6 months +6.98 %
1 year +107.78 %
3 years +136.13 %
5 years +487.81 %
7 years +820.74 %
SHARE 97.10€ (30.04.2026 at 11.00 a.m.)

