
Vonovia, Germany’s largest residential real estate group, is firmly stuck in a bear market: On October 28, 2026, management issued an ad hoc announcement clarifying the targets for 2026 and lowering those for 2028; the stock fell to EUR 15.26 the following day, its lowest level since 2014. The Q3 results released on November 4, 2026, however, show a stable core business: In the first nine months, rental revenue rose by 3.0% to EUR 2.63 billion and adjusted EBITDA by 3.3% to EUR 2.19 billion; the vacancy rate stands at just 2.3%. The catch is interest rates: Higher financing costs are pushing adjusted EBT down by 3.5% to EUR 1.41 billion, operating free cash flow is plummeting by 34%, and organic rental growth is falling to around 3.8%. On Xetra, the stock is trading at EUR 17.11 (+1.3%) as of November 5, 2026, about 63% below the EPRA NTA of EUR 46.31 per share. Analysts’ average target price is around EUR 20.80. From a technical analysis perspective, I see a clear buying reaction at EUR 15.32 following the earnings report, and the most likely path is initially a rebound toward the EUR 20 mark; only a breakout above that level would be the first genuine positive signal, with upside potential to around EUR 24.
Key Points
- 9M 2026: Rental income EUR 2.63 billion (+3.0%), Adjusted EBITDA EUR 2.19 billion (+3.3%), Adjusted EBT EUR 1.41 billion (−3.5%)
- 2026 forecast refined: Adjusted EBITDA in the lower half of the 2.95–3.05 billion EUR range, Adjusted EBT at the lower end of the 1.9–2.0 billion EUR range
- 2028 targets lowered: organic rental growth of approximately 4.5% instead of 5%, Adjusted EBITDA at the lower end of the range of EUR 3.2–3.5 billion
- EPRA NTA: 46.31 EUR per share; LTV: 46.1%; dividend: 1.25 EUR (yield approx. 7.3%)
- Analysts: Average price target around 20.80 EUR, range 14 to 24.50 EUR
- Chart levels: Support at 15.32 EUR, first positive signal above 20 EUR, target around 24 EUR
What are the current key metrics for the Vonovia stock?
On November 5, 2026, the Vonovia stock was trading on Xetra at 17.11 EUR (+1.3%, 2:32 p.m.), which is about 41% below its 52-week high of 28.90 EUR.
With a market capitalization of approximately 14.5 billion EUR, the group is now valued at just over one-third of its book value (EPRA NTA of 46.31 EUR per share), and the dividend of 1.25 EUR corresponds to a yield of approximately 7.3%.
What news is currently driving Vonovia’s stock?
Three topics are currently driving Vonovia stock: the lowered targets announced on October 28, 2026, the Q3 results released on November 4, 2026, and rising interest rates.
The ad hoc announcement sent the stock down to 15.26 EUR on October 29, 2026—its lowest level since 2014. The Q3 results on November 4, 2026, triggered a 3.6% rebound. In the background, the ECB’s September interest rate hike and Berlin’s plans for public ownership are weighing on market sentiment. Anyone who wants to see which side of the interest rate turnaround is making money should check out my analysis of Deutsche Bank Aktie —there, it is precisely the interest rates that are driving the stock price up, while Vonovia is currently being dragged down by them.
What does Vonovia’s management say about the Q3 results?
CEO Luka Mucic emphasizes the strength of the rental business: “Our results once again demonstrate the resilience of our core business,” he said during the presentation of the nine-month figures.
However, the environment remains challenging for the sales segments. CFO Philip Grosse makes it clear, given the current interest rate environment, what matters most now: securing cash flow, deploying capital strategically, and strengthening the balance sheet.
What went well: The rental business grew by 3.5% in adjusted EBITDA Rental despite having approximately 5,000 fewer apartments. The Value-Add segment, which includes the tradesmen’s organization and energy business, increased by 31.4% to EUR 197.2 million. The vacancy rate stands at just 2.3%, the rent collection rate at 99.6%, and sales of approximately 900 million EUR were generated.
The catch: Interest expenses are eating into growth. Adjusted EBT fell by 3.5%, operating free cash flow by 34.1%, and organic rental growth dropped from 4.2% to 3.8%. The Development segment plummeted by 56.4%, and recurring sales fell by 11.8%. New investments in the Manage-to-Green program have been put on hold for the time being, new construction for the company’s own portfolio is being scaled back, and the development division is undergoing a strategic review. In addition, there is a personnel change: Philip Grosse does not intend to seek a contract extension.
Outlook: For 2026, Vonovia expects Adjusted EBITDA in the lower half of the range of 2.95 to 3.05 billion EUR, Adjusted EBT at the lower end of the range of 1.9 to 2.0 billion EUR, and rental revenue in the upper half of the range of 3.45 to 3.55 billion EUR. In 2027, Adjusted EBITDA is expected to rise slightly, while Adjusted EBT is expected to remain roughly flat. Debt reduction is the top priority; AI-driven efficiency measures are expected to generate approximately EUR 50 million per year starting in 2030.
What does Vonovia do—and how does the company make its money?
Vonovia is Germany’s largest residential real estate company and generates most of its revenue by renting out approximately 527,000 apartments in Germany, Sweden, and Austria.
The DAX-listed company, headquartered in Bochum, is led by CEO Luka Mucic; the market value of its portfolio stands at EUR 85.8 billion. Since August 2025, Deutsche Wohnen has been fully integrated via a control and profit transfer agreement; compensation payments to its minority shareholders rose to 257.1 million EUR in the first nine months.
Rental: The core business. Rental income after nine months totaled EUR 2,627.7 million, of which EUR 2,223.5 million was generated in Germany, EUR 310.6 million in Sweden, and EUR 93.6 million in Austria. The average actual rent rose to EUR 8.57 per square meter, and adjusted EBITDA from rental operations rose to EUR 1,912.2 million (+3.5%).
Value-Add (Additional Business): In-house tradespeople, energy, neighborhood amenities, and cable TV. The segment generated revenue of EUR 1,203.9 million, primarily from intra-group transactions, and delivered EUR 197.2 million in adjusted EBITDA (+31.4%).
Recurring Sales (Individual Sales): Sales of individual apartments to tenants and owner-occupiers. 965 units sold generated EUR 216.8 million at a 42.2% premium to market value; Adjusted EBITDA fell to EUR 49.9 million.
Development (Project Development): New construction for sale and for the company’s own portfolio. Revenues totaled EUR 267.4 million; the gross profit margin fell to 13.7%, and Adjusted EBITDA dropped to EUR 28.1 million (−56.4%).
How Vonovia Makes Money: About 87% of adjusted EBITDA comes from rent. Growth is driven by rent increases based on the rent index, modernization, and ancillary services related to the apartments. Because the portfolio is heavily financed with debt, interest expenses determine earnings per share and the value of the properties.
Fundamental Analysis: Is the Vonovia Stock Undervalued After the Plunge?
Fundamentally, Vonovia stock is more cheaply valued than it has been in over a decade, but there’s a reason for the discount: interest rates.
According to Aktienfinder, the adjusted P/E ratio stands at 9.1, which is nearly half the 10-year average of 17.7. Based on the forecast for Adjusted Shareholder Earnings (the upper half of the range from 1.4 to 1.5 billion EUR), I arrive at a 2026 P/E ratio of around 10. At EUR 17.11, the stock is trading about 63% below the EPRA NTA of EUR 46.31 per share.
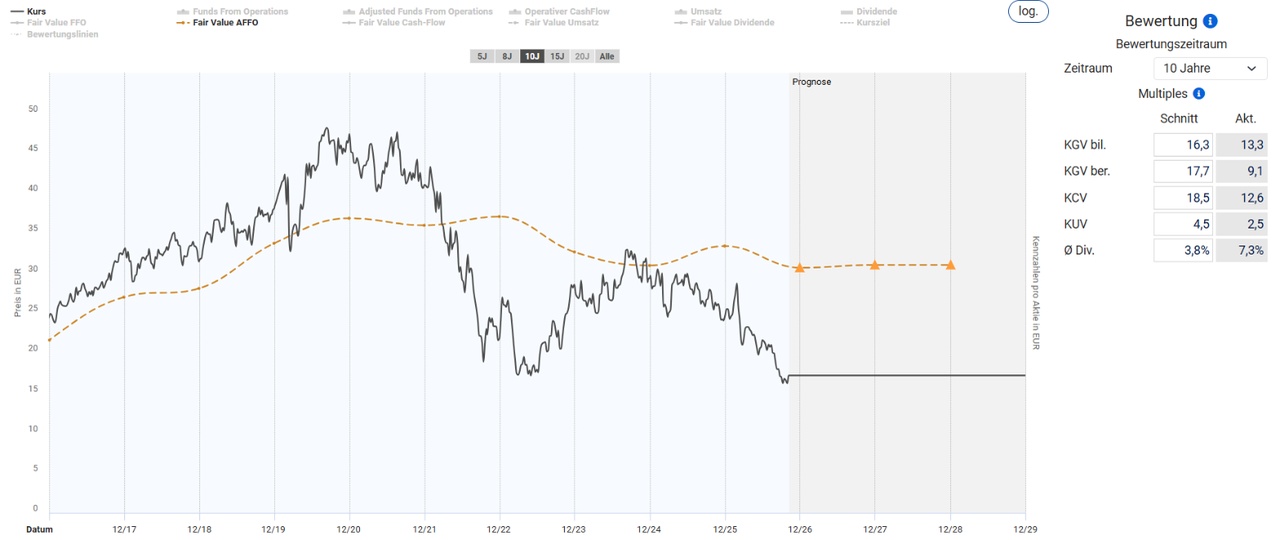
Interest and Depreciation: Rising interest rates hit Vonovia twice. First, financing costs are increasing, which reduced Adjusted EBT by 3.5% to EUR 1,408.0 million after nine months. Second, market values decline in valuation models when interest rates rise. Vonovia still expects a largely stable portfolio valuation for 2026, but according to Reuters, the yield on Vonovia’s eight-year bonds has risen by about 140 basis points since the escalation in the Middle East. The ECB raised the deposit rate to 2.50% in September; with inflation at 3.8%, economists expect another rate hike in December. Every interest rate hike increases the risk of new write-downs.
Debt and Cash Flow: The loan-to-value ratio rose to 46.1%; net debt stands at 13.9 times adjusted EBITDA, and the interest coverage ratio at 3.5 times. Operating free cash flow fell to EUR 932.5 million (−34.1%). As a result, debt reduction now takes priority over growth.
Dividend: For 2025, Vonovia paid EUR 1.25 per share, representing a yield of about 7.3% at the current price. No statement has yet been made regarding the dividend for 2026. Anyone wishing to weigh the security of a dividend against that of an insurer should review my analysis of Münchener Rück Aktie —it demonstrates how stable a dividend can be when interest rates work in favor of the business rather than against it.
Peers and Politics: The entire industry is suffering from interest rates. In the case of LEG Immobilien, the Aroundtown subsidiary Grand City Properties has held a 20.04% stake since October 20, 2026, because the stock is trading significantly below book value. For Vonovia, there’s also the Berlin risk: The group owns around 130,000 apartments in Berlin; a law mandating the transfer of housing to public ownership is planned for 2028 and is likely to end up before the Constitutional Court.
Vonovia Stock Price Targets and Forecast for 2026
On average, analysts see a price target of around 20.80 EUR for the Vonovia stock, representing a solid 20% upside potential; however, from a technical analysis perspective, the stock remains firmly in bearish territory.
Since the ad hoc announcement on October 28, 2026, nearly all firms have lowered their targets, with the range extending from 14 EUR (Morgan Stanley) to 24.50 EUR (JPMorgan). My analysis of Telekom Aktie.
Key price levels:
- 52-week high: 28.90 EUR (end of February 2026)
- Current price: 17.11 EUR (Xetra, November 5, 2026, 2:32 p.m., +1.3%)
- First resistance: 19.89 to 20.00 EUR (red zone, first positive signal upon a breakout)
- Second resistance: 24.20 EUR (red zone, target following a breakout)
- Third resistance: 32.90 EUR (red zone, 2024 high)
- Support and critical level: 15.32 EUR (annual low zone, Xetra intraday low of 15.26 EUR on October 29, 2026)
Analyst price targets:
- Average price target: approx. 20.80 EUR (our own calculation based on seven targets since October 20, 2026)
- JPMorgan: Overweight, 24.50 EUR (November 3, 2026)
- Jefferies: Buy, 23.00 EUR (November 4, 2026)
- Berenberg: Buy, 23.00 EUR (October 29, 2026)
- UBS: Buy, 23.00 EUR (October 29, 2026)
- Deutsche Bank: Buy, 20.00 EUR (November 3, 2026)
- Goldman Sachs: Neutral, 18.20 EUR (November 2, 2026)
- Morgan Stanley: Underweight, 14.00 EUR (October 20, 2026)
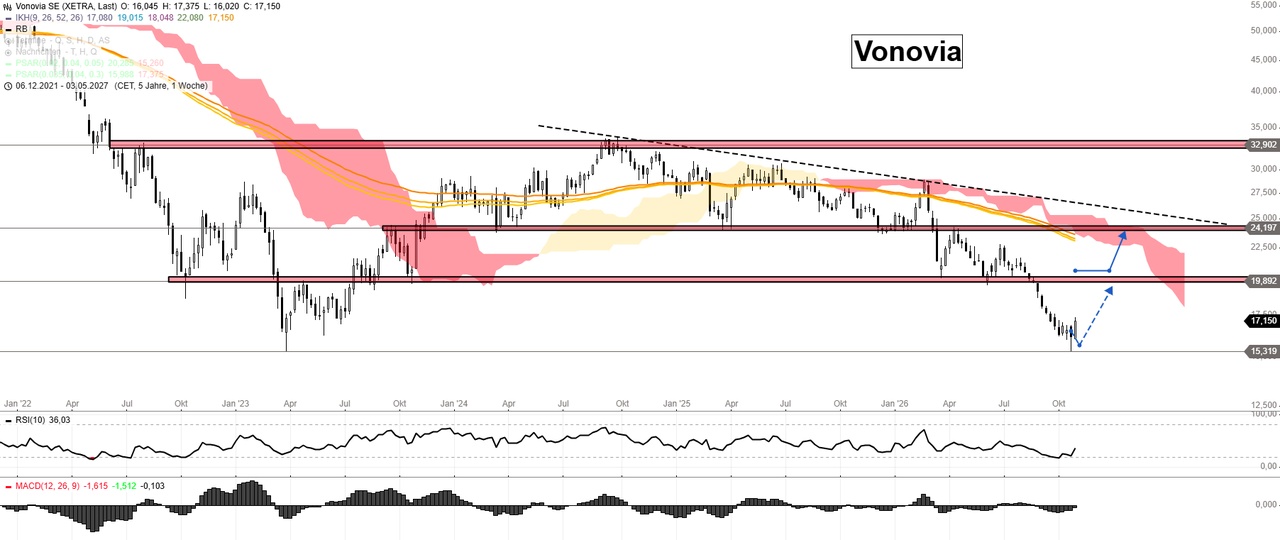
Chart Analysis:
On Vonovia’s weekly chart, the situation is clear: The stock remains firmly in bearish territory due to rising interest rates and the real estate write-downs that Vonovia will then have to take. The dotted downtrend line dating back to mid-2024 is pushing any recovery lower, and in the fall, the price fell further into the red zone around 19.89 EUR.
However, market participants are showing a clear buying reaction at 15.32 EUR following the earnings report. Long-term investors could certainly take advantage of this for a contrarian position. The most likely path, in my view, is initially a rebound from 15.32 EUR back to the 20-euro mark.
A breakout above 20 EUR would then be the first positive signal, which could be rewarded with buying interest up to around 24 EUR. There, the red resistance zone lies at 24.20 EUR, and this resistance level is likely to prove extremely stubborn.
If, on the other hand, the current annual low of 15.32 EUR is breached, the downtrend will simply continue—especially if further interest rate hikes follow.
Opportunities and Risks of the Vonovia Stock
Opportunities:
- ✅ Stable core business: rental income up 3.0%, vacancy rate only 2.3%
- ✅ Value-add segment grows by 31.4% to EUR 197.2 million in adjusted EBITDA
- ✅ Historically cheap: adjusted P/E ratio of 9.1 instead of the 10-year average of 17.7
- ✅ Discount of approximately 63% to the EPRA NTA of EUR 46.31
- ✅ Dividend of 1.25 EUR for 2025, yield approx. 7.3%
- ✅ Buying interest at 15.32 EUR; a rebound toward the 20-euro mark is the likely path
Risks:
- ⚠️ Rising interest rates: ECB deposit rate at 2.50%, further increase expected in December
- ⚠️ Interest-rate-related write-downs on the real estate portfolio possible
- ⚠️ Adjusted EBT −3.5%, operating free cash flow −34.1%
- ⚠️ 2028 targets lowered; rent growth now only about 4.5%
- ⚠️ Berlin plans to convert approximately 130,000 Vonovia apartments into public housing
- ⚠️ A break below EUR 15.32 continues the downward trend
Conclusion: Vonovia Stock—A Bear Market with a Countercyclical Opportunity?
The Vonovia stock remains in a bear market—in my view, a contrarian position starting at 15.32 EUR is only suitable for long-term investors; the first positive signal won’t appear until the price exceeds 20 EUR.
Operationally, the company is delivering: rental income is rising, vacancy rates are minimal, and ancillary business is growing at a double-digit rate. However, interest rates are weighing on profits, cash flow, and property values, which is why management has lowered its 2028 targets and made debt reduction its top priority.
With an adjusted P/E ratio of 9.1, a dividend yield of around 7.3%, and a discount of about 63% to net asset value (NTA), the stock is historically undervalued. From a technical analysis perspective, the plan is clear: the most likely path leads back to the 20-euro mark for now. A breakout above that level could trigger buying interest up to around 24 EUR, where very stubborn resistance awaits. If the annual low of 15.32 EUR is breached, the downtrend will continue, especially if interest rates rise further.
Anyone in the DAX who prefers to bet on a company where growth—rather than interest rates—will determine the next price surge should read my analysis SAP Aktie —there, the situation is exactly the opposite.
Sources
- Vonovia Press Release: 9M Results 2026 (November 4, 2026)
- Vonovia Interim Report 9M 2026: Earnings by Segment
- Vonovia 9M 2026 Interim Report: Business Outlook
- Vonovia Ad Hoc Announcement: New Guidance for 2026, 2027, and 2028 (October 28, 2026)
- Vonovia Investor Relations: Financial Calendar
- Deutsche Börse: Xetra Price and 52-Week Range for Vonovia
- Vonovia Xetra Price as of Nov. 5, 2026, 2:32 p.m.: 17.11 EUR (+1.30%), previous day’s close 16.89 EUR, 52-week range 15.26 / 28.90 EUR (Deutsche Börse); Alpha Vantage VNA.DEX comparison (daily and weekly prices)
- dpa-AFX: Vonovia is taking a more cautious approach—high interest rates are weighing on real estate sales (October 29, 2026)
- Reuters: Vonovia lowers targets for 2028 – higher interest rates slow growth (Oct. 29, 2026)
- dpa-AFX Analyser: Ratings from Jefferies (Nov. 4, 2026), Deutsche Bank and JPMorgan (Nov. 3, 2026), Goldman Sachs (November 2, 2026), Berenberg, and UBS (October 29, 2026)
- Morgan Stanley: Downgraded to Underweight, price target 14 EUR (Oct. 20, 2026, media reports)
- dpa-AFX: Vonovia – Public ownership not feasible in the planned form (October 19, 2026); ZDFheute (October 28, 2026)
- ECB interest rate decisions in September 2026 and Oct. 29, 2026 (Biallo, LBBW)
- Aroundtown/Grand City Properties: Ad-hoc announcement regarding LEG stake (October 20, 2026)
- Vonovia 2020 Annual Report: All-time high of 62.74 EUR (September 2, 2020)
- Stock3: Vonovia Weekly Chart (Xetra, EUR), as of Nov. 5, 2026
- Aktienfinder: Fair value calculation and valuation metrics for Vonovia, as of Nov. 5, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What do you currently think of the $VNA (-1.25%)?