

The sun is blazing—and maybe this stock is in for a hot summer, too. ☀️📈
Today I’d like to introduce you to a company in the biotech sector. This stock is definitely speculative and can be considered a gamble, but at the same time, the company offers an interesting CRV and significant potential if the investment thesis proves correct.
🧬 Alpha Teknova Inc.: The “Head Chef” in the Biotech Lab on the Path to a Turnaround
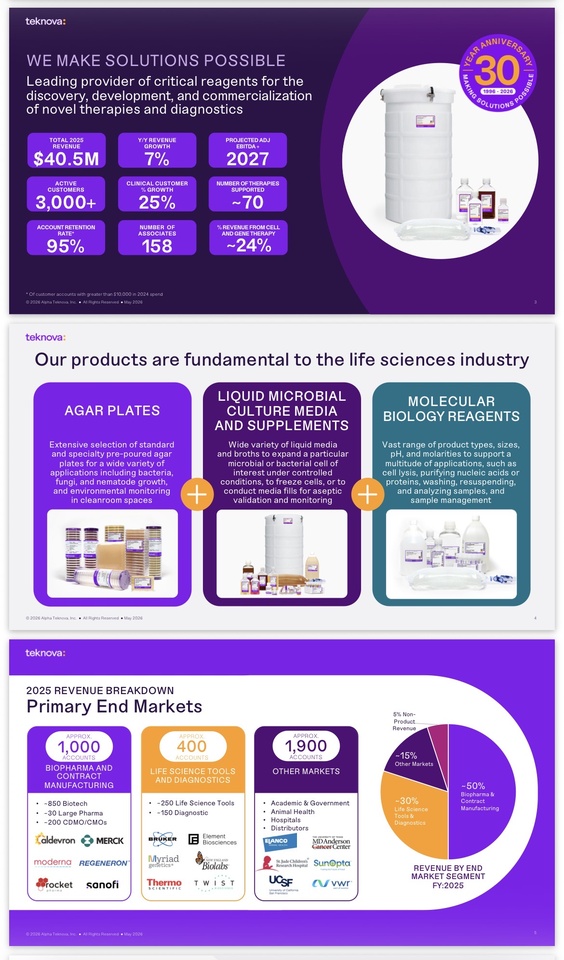
While tech investors are blindly pumping billions into unprofitable AI silicon in 2026, an unnoticed comeback is taking place among second-tier life sciences suppliers: Alpha Teknova $TKNO The company is not a glamorous tech startup, but in 2026 it will celebrate its 30th anniversary as a critical systems supplier to the pharmaceutical and biotech industries. Its core business? Customized cell culture media, buffer solutions, and reagents.
What sounds boring—like “mixing liquids”—is in fact the fundamental infrastructure for the most advanced medicine of our time. After a brutal post-COVID hangover and the subsequent collapse of the biotech sector, the stock made a spectacular turnaround in the summer of 2026. From its low in February of just under $1.90, the stock had climbed above the $5.30 by July 2026. The market is slowly realizing: The trend has reversed, costs are capped, and the new high-tech factory is finally hitting its stride.
1. The Business Model: The Razor Blade Principle of Gene Scissors 🧪🧫🧬
Teknova $TKNO doesn’t develop its own drugs. Instead, it sells the “shovels” in the biopharma industry’s modern gold rush. Its business model is based on extremely strong customer loyalty:
① Lab Essentials (The Stable Foundation): Accounts for about 75% of the business. It supplies the standard daily equipment (gels, agar plates, cleaning media) for research laboratories.
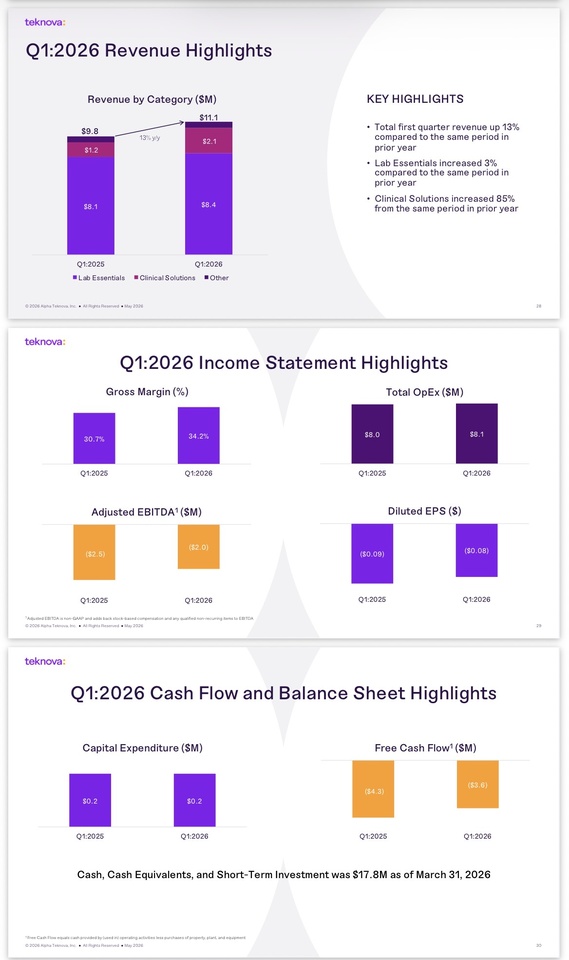
② Clinical Solutions (The Hyper-Growth Lever): The driving force behind the growth story (approx. 20–25% of revenue). Here, Teknova formulates highly specialized GMP-certified media for Phase 1 through 3 clinical trials, particularly for cell and gene therapy (e.g., mRNA, CRISPR). In Q1 2026, this segment exploded by a staggering 85% year-over-year.
③ The FDA Gag Agreement (The Sticky Part): If a pharmaceutical company develops a drug in the clinical phases using Teknova’s media $TKNO , it cannot simply switch suppliers. Any change in the chemical composition would jeopardize FDA approval. The result: Teknova has a historical retention rate of a phenomenal 95% and is currently deeply embedded at the core of around 70 active clinical therapies.
The financial strategy: Maximizing capacity at the Hollister stronghold 🏭📉
The reason for the deep valley of tears in previous years was a classic overinvestment problem. Teknova built a gigantic, highly automated production facility in Hollister, California, which consumed enormous fixed costs, while post-COVID customer demand plummeted at the same time.
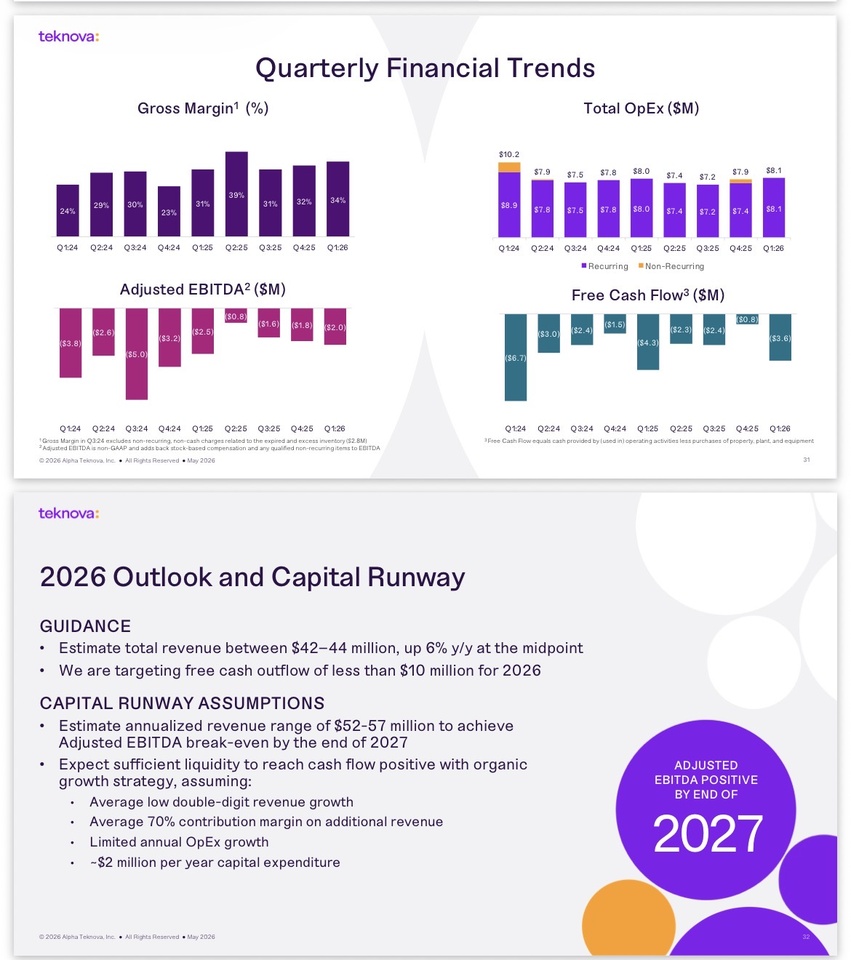
The strategy implemented in 2026 is now paying off: By strictly capping operating costs (OPEX stable compared to the previous year) and increasing volume, the operating leverage is having a relentlessly positive impact. Every additional bottle of liquid that now leaves the factory drives the gross margin higher and rapidly erodes the loss.
Key figures (as of July 2026 / FY26 estimate) 📊
Stock listing: NASDAQ under the ticker TKNO.
Market capitalization: ~195 to 215 million USD
Revenue & Growth: Q1 2026 generated 11.1 million USD (+13% YoY) the strongest start to the year in nearly three years. For the full year 2026, management is fully on track to meet the confirmed guidance of $42 to $44 million.
Margin Expansion: The highlight of the rally. Thanks to improved factory utilization, the gross margin climbed by 350 basis points in the last quarter, from 30.7% to 34.2%. Gross profit jumped 26.7%.
Cash Runway: As of March 2026, there are $17.8 million in cash and short-term investments, compared to a moderate total debt of 13.2 million USD. Since the free cash outflow for 2026 is projected to be less than 10 million USD, the liquidity is exactly sufficient to cover the...
Path to Profitability (2027): ...to be achieved. The net loss per share (EPS) has already fallen to $-0.08 (beating analysts’ estimates). The company has its sights firmly set on reaching operational breakeven in 2027.
Why is this stock exciting RIGHT NOW? 🚀
1. The end of the slump in the biotech sector
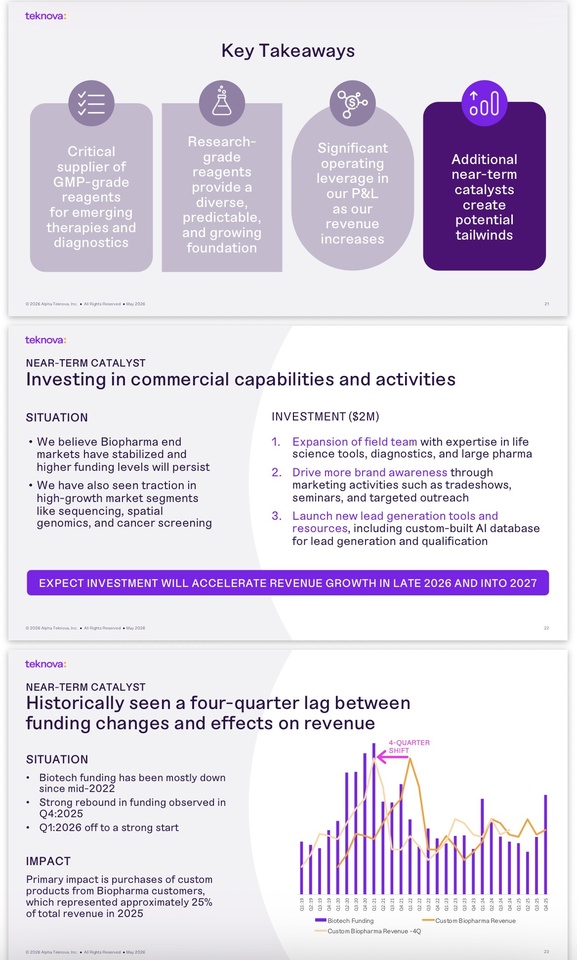
The macroeconomic turnaround in the healthcare tools sector is taking hold. Customer inventories have been reduced, and research budgets are rising again. Teknova $TKNO is riding a perfect cyclical tailwind.
2. Symmetrical leverage in “Clinical Solutions”
Since gross margins for custom clinical solutions are significantly higher than for “Lab Essentials,” the current 85% growth in this segment is driving a disproportionately large improvement in profitability.
3. A Logical Acquisition Target
With a market capitalization of around 200 million USD and a state-of-the-art, fully certified production facility in California, Teknova is a prime target for the industry giants (Thermo Fisher $TMO (-0.43%) , Danaher $DHR (+0.36%) Merck $MRK (+0.34%) ). They would much rather buy Teknova’s 70 sticky therapeutic pipelines $TKNO rather than build them from scratch.
4. Competition & Moat ♟️
The giants (Thermo Fisher $TMO (-0.43%)
/ Danaher $DHR (+0.36%)
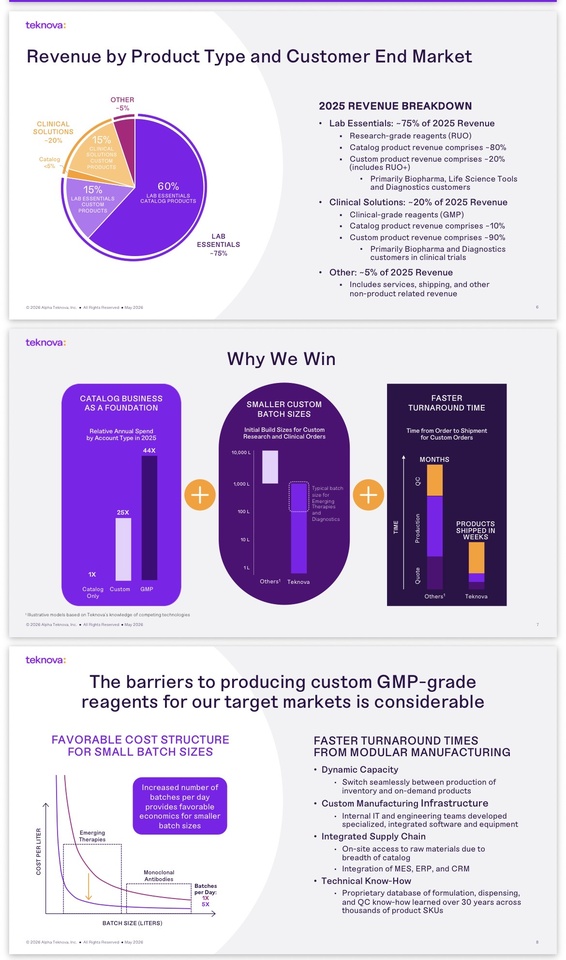
): They have infinite economies of scale but are slow to respond. It often takes a giant months to produce a custom buffer solution in small batches for a Phase 1 study. Teknova excels with extremely short lead times and tailored flexibility (“Customization at Scale”).
The Moat: The combination of FDA certification, close integration into pharmaceutical companies’ production protocols, and a relentless 95% retention rate makes it nearly impossible for competitors to displace Teknova from an ongoing clinical phase.
6. Risks ⚠️
❗️The narrow cash path: Teknova $TKNO cannot afford any major operational missteps until 2027. Should the biotech sector freeze up again, a dilutive capital increase looms despite the current recovery.
❗️Concentration risk in the clinical portfolio: If three or four of its clients’ major therapies fail in Phase 3 clinical trials, planned future revenue will evaporate.
Personal Conclusion & Reaper Bonus 🧐
Alpha Teknova $TKNO is a bet on an operational turnaround in the small-cap sector. Anyone who had the courage to buy in February is sitting on over 150% in profits. But even at current levels, the story remains intact: factory utilization is rising, the high-margin clinical segment is booming, and the macroeconomic environment is stabilizing.
Jack’s Verdict:
“Teknova smells like the bright future of gene therapy, but isn’t making any money yet. Why do I like it anyway? Because they own the toll booth for the sterile lab environment. Wall Street completely wrote this stock off after the COVID-19 hype. Now we’re seeing that the new factory wasn’t an expensive white elephant—instead, the depreciation is slowly being offset by actual volume. Anyone investing here isn’t betting on that one miracle drug, but on the fact that labs will continue to need liquids. With a $200 million market cap and a 95% retention rate, this is a damn hot turnaround bet following the February crash.”
REAPER RATING: ✅ SPECULATIVE BUY
REAPER SCORE: 7.2/10 · Anchor: Turnaround / Micro-Cap Growth
CONFIDENCE: 🟡 MEDIUM – The turnaround is fundamentally sound (margin expansion!), but as an unprofitable micro-cap, the stock remains vulnerable to setbacks in its cash burn rate.
This is a rather atypical pick on my part 😬—it’s not (yet) a profitable company 👀
I’m curious to hear your opinions 😎😏
@Get_Rich_Or_Die_Tryin @Raketentoni
@Multibagger
@Tenbagger2024
@Stocktective
@schlimmschlimm
@Dividendenopi


