1. The statement about Texas is correct
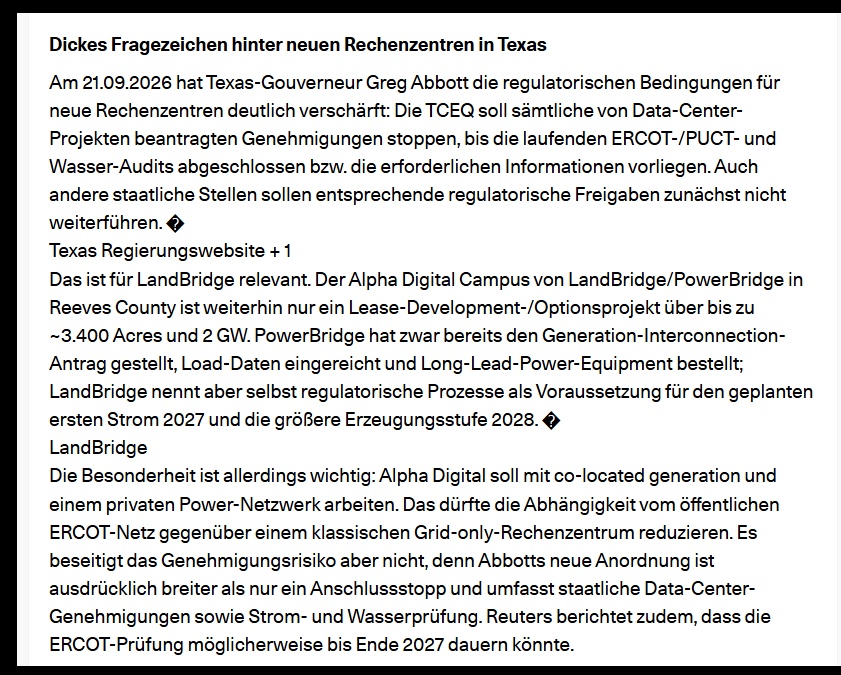
On September 21, 2026 , Governor Abbott did indeed order the TCEQ to suspend processing new data center permits until the ongoing reviews by ERCOT, PUCT, and TWDB provide sufficient information on electricity and water consumption.
However, it is important to note: This is not a blanket ban on data centers in Texas. It is a moratorium on permits—or an additional regulatory hurdle—while the reviews are underway. The TCEQ is to suspend processing until October 19 report on its implementation.
2. For LandBridge, the text is more interesting than it appears at first glance
The screenshot reads:
“This is relevant to LandBridge.”
Yes—definitely.
Because LandBridge has an agreement with PowerBridge for the Alpha Digital Campus :
- up to 3,400 acres
- up to 2 GW
- Co-located Power Generation
- Private power infrastructure
- First power delivery according to current plans 2027
- Increased electricity generation 2028
- However, expressly subject to regulatory processes and commercial discussions.
And in my opinion, it is precisely this last point that is is not emphasized enough.
3. The most important point: “private power network” does not fully protect LandBridge
The screenshot essentially says:
The private power network reduces dependence on the ERCOT grid.
This is plausible and consistent with the project structure.
According to LandBridge, PowerBridge has already submitted its Generation Interconnection Request, transmitted load data, and ordered long-term equipment. The campus is to be supplied via a private-use network .
But this implies notthat the project is completely independent of current regulations.
This is precisely where the screenshot is actually a bit too optimistic.
Abbott’s current order has explicitly been broadened: It not only applies to traditional ERCOT grid connections but is also intended to prevent other state permits for data center projects from proceeding until the relevant information is available.
Texas pausiert die Genehmigung einer Umweltgenehmigung für Rechenzentren
4. The Crucial Difference for the LandBridge Thesis
I would therefore assess the situation as follows:
🔴 Short term: negative regulatory signal
The timeline for the Alpha Digital Campus may be become more uncertain or slower .
This particularly affects the assumption:
2027 → first power
and
2028 → larger-scale power generation
These dates are not guaranteed dates. LandBridge itself makes them subject to ongoing regulatory processes and commercial discussions.
🟢 Medium-/long-term: This does not undermine the LandBridge story
And I consider that to be the far more important point.
Texas is not currently trying to eliminate data centers altogether. Rather, the government is trying to resolve issues related to electricity, water, infrastructure, and costs before proceeding with further expansion.
For a company like LandBridge, this can even serve as a kind of quality filter :
Projects with a secure energy supply, suitable land, and their own infrastructure could be better positioned than speculative projects.
However, this is a possible consequence—not a trend that has already been proven.
5. There’s one thing in the screenshot I would definitely change
The sentence:
“It does not, however, eliminate the permitting risk”
is very important and should actually be emphasized even more.
Because this is precisely where the investment risk with LandBridge currently lies.
I would even phrase it this way:
“The private power grid reduces dependence on the ERCOT grid but does not eliminate regulatory risk. The Texas government’s current measures could delay the approval timeline and, consequently, the transition of the Alpha Digital Campus from the development phase to an operational project.”
That’s much more precise.
6. And that brings us to the chart
This is where it gets particularly interesting for me.
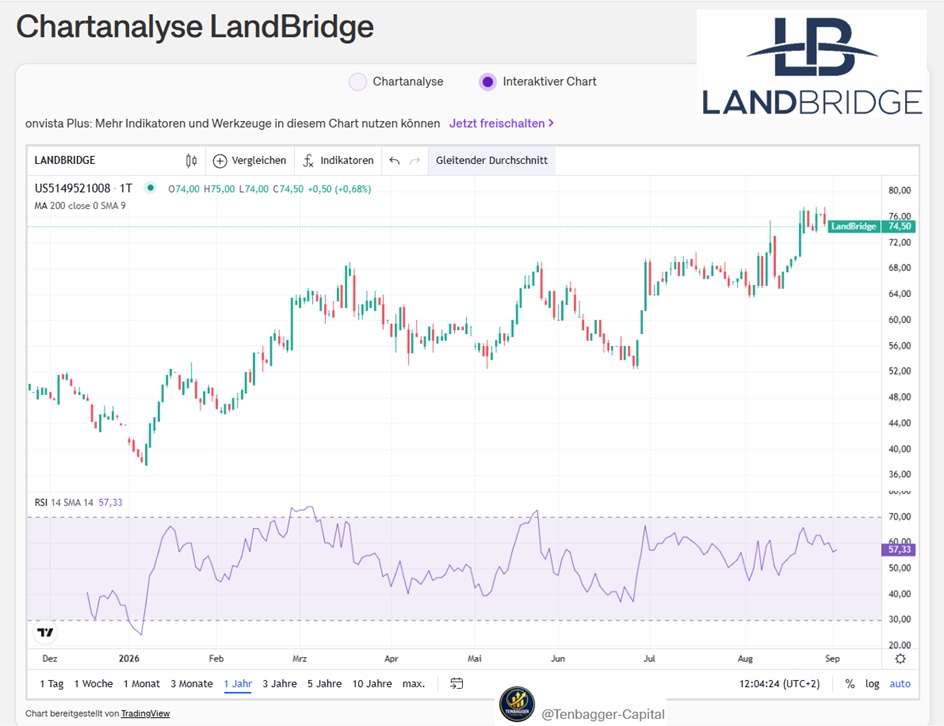
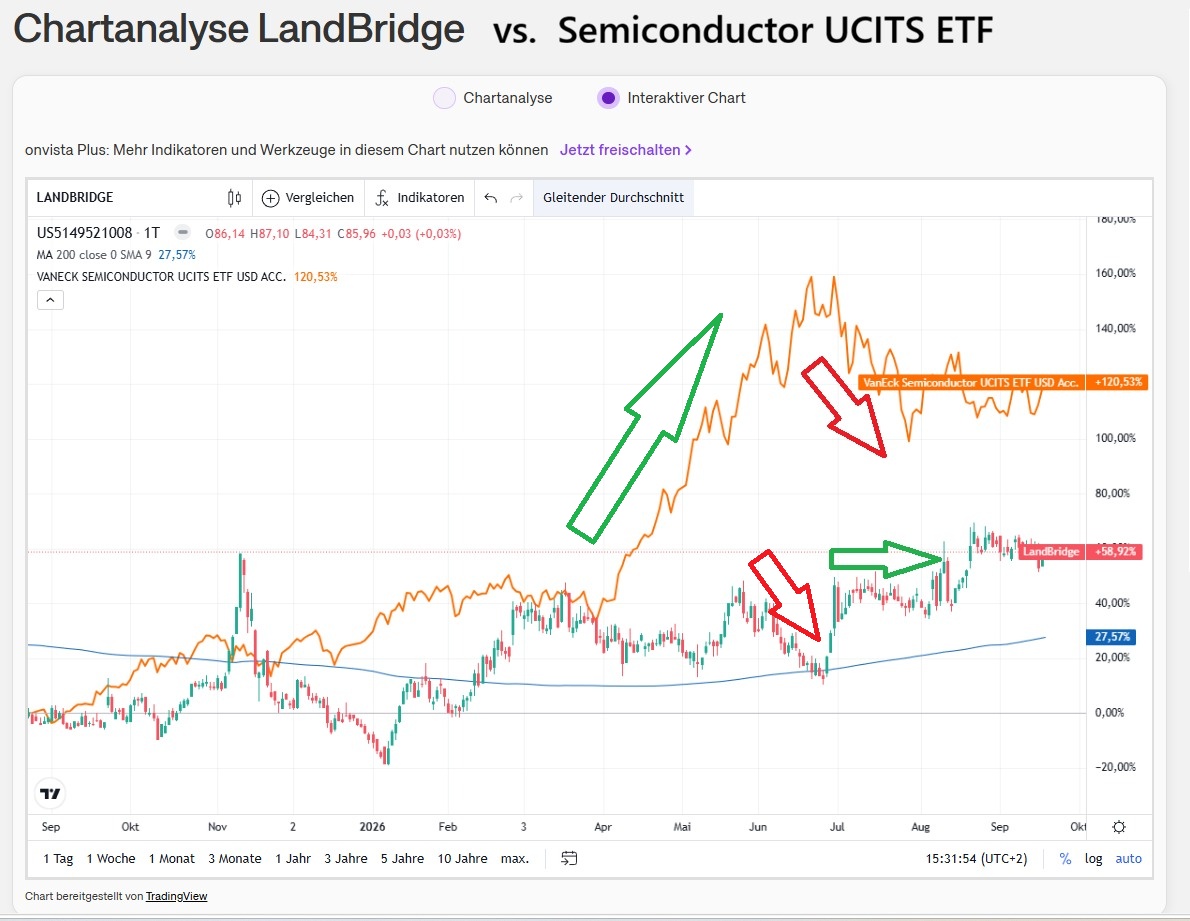
The chart shows no typical AI hype surrounding LandBridge.
And now there’s an additional reason for this:
The market currently has to process three things at once:
LandBridge today
→ existing land/infrastructure business
LandBridge in 2027/28
→ Alpha Digital Campus / Data Center
LandBridge risk
→ Regulatory delays in Texas
This explains why the stock price isn’t simply rising like a semiconductor or AI stock.
LandBridge is therefore currently more of a infrastructure/land play with a very significant AI/data center component than a traditional AI stock.
My take on the screenshot:
The text is generally good and up-to-date, but I wouldn’t interpret the conclusion as “LandBridge is now facing a problem.”
Rather:
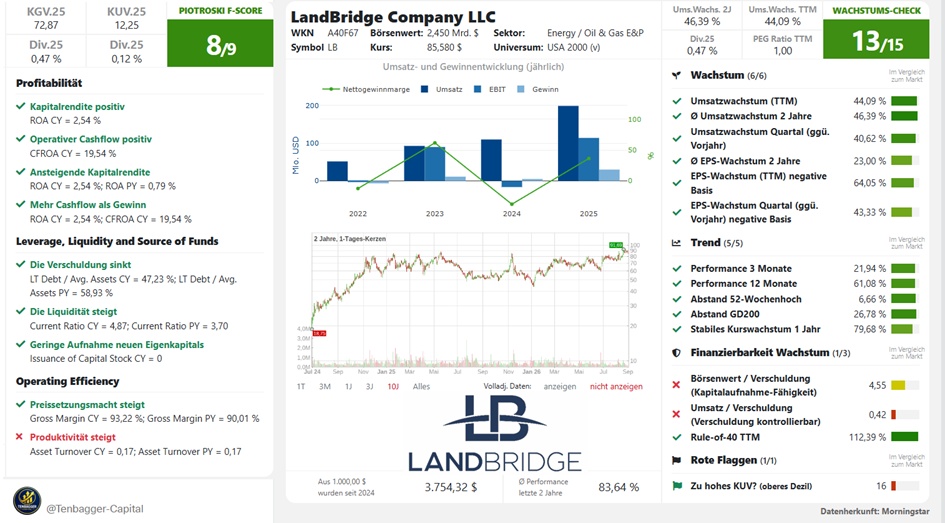
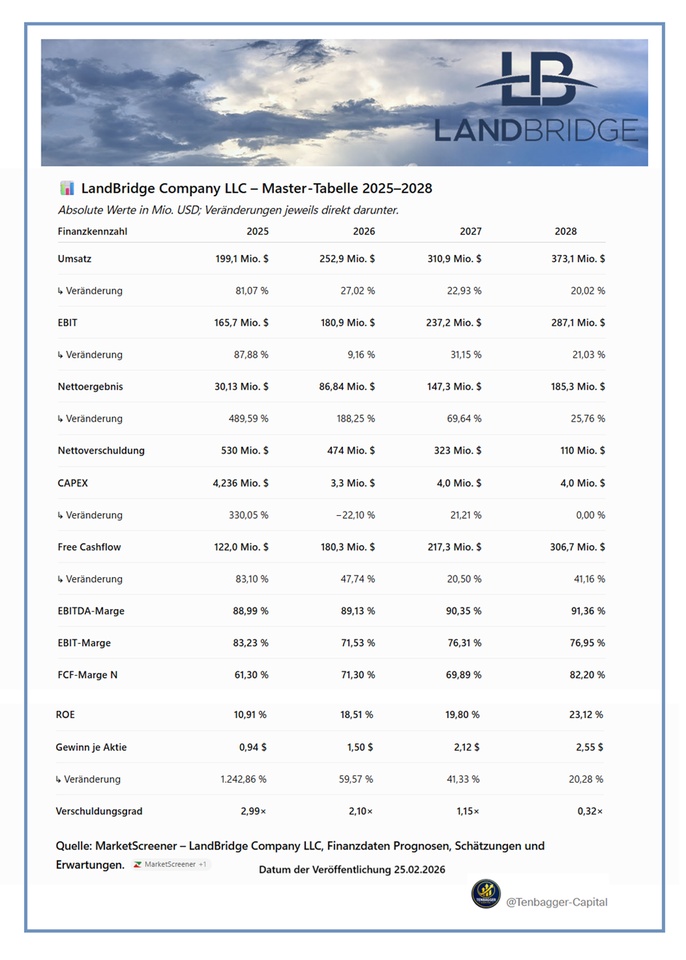
The data center story is real, but it hasn’t yet fully translated into cash flows. At the same time, regulatory risk has increased. The market has apparently priced in part of the story, but it doesn’t yet value LandBridge as a classic AI stock.
And that’s exactly why I find the chart comparison very interesting.
What the chart actually shows
Over the period shown, LandBridge is up approximately +58%, while the semiconductor ETF is at around +120% . At the same time, while LandBridge did rally significantly over the summer, the move was not nearly as strong or dynamic as that of traditional AI/semiconductor stocks.
This suggests that the market currently views LandBridge as a pure-play AI stock.
Is the data center story already priced in?
Partly yes—but in my assessment, not yet fully as an earnings story.
The key point:
- LandBridge already signed the agreement in April for the up to 2-GW Alpha Digital Campus back in April.
- The project initially covers approximately 3,400 acres.
- The first electricity deliveries are scheduled for 2027, with larger-scale power generation scheduled for 2028 .
- In July, Liberty Energy joined the project as a concrete partner for energy supply. The first phase is expected to generate over 300 MW and will be expanded later.
- Furthermore, at its Investor Day, LandBridge very clearly positioned its entire digital infrastructure story as a long-term growth opportunity.
So the market is definitely familiar with the story.
However, the crucial cash flows from the data centers still in the future. LandBridge itself points out that this depends on obtaining regulatory approvals and commercial agreements
And this is exactly where the chart gets interesting
Right now, I’d describe LandBridge more as:
Land + Energy + Water + Permian Basin + future digital infrastructure
— and not as a traditional AI stock.
This also explains why LB moves differently from the Semiconductor ETF.
Factor / Situation at LandBridge
Traditional AI chip
❌
AI data center
🟡 future option
Land for data centers
🟢 already available
Energy supply
🟢 is being actively developed
2-GW project
🟢 announced
First power in 2027
🟡 Future
Large cash flows from data centers
🟡 Not yet realized
Oil/gas/water business
🟢 Current core business
And that, to me, is the crucial difference.
Particularly interesting: The market isn’t yet pricing in 2 GW in revenue
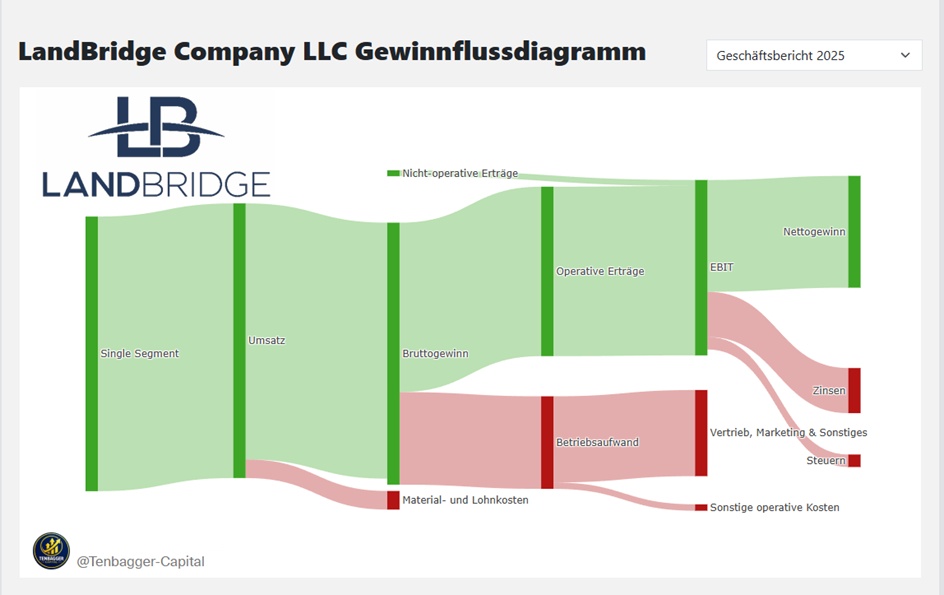
The Alpha project is currently not a 2-GW revenue project for LandBridge. LandBridge primarily provides the land and infrastructure and generates revenue through the corresponding leasing and development structures.
This means:
2 GW of announced capacity ≠ 2 GW in revenue for LandBridge.
However, if long-term, high-value lease agreements result from this, the value of the portfolio—which has so far been viewed primarily as a land/infrastructure business—could change significantly.
In addition, according to LandBridge’s own figures, has identified approximately 25,000 acres suitable for data center development, with a theoretical potential of up to 18 GW.
LandBridge & PowerBridge Partner für den 2GW-Rechenzentrumscampus in Westtexas – DCD
🔎 My key observation regarding the chart comparison
The market has recognized the story but still largely views it as an option on future infrastructure cash flows.
This aligns very well with the stock’s price action.
If LandBridge transitions over the next 12–24 months from “option on data centers” → “signed long-term contracts → actual construction/power progress → rising recurring revenue” over the next 12–24 months, the nature of its valuation could also change.
That would then be the interesting re-rating point—not today’s headline “2 GW Data Center.”
And that’s exactly why I find the chart comparison with the semiconductor ETF very insightful: So far, LandBridge hasn’t been trading like an AI hype play.
For me, the crucial next step right now wouldn’t be the next wave of general AI hype, but rather a concrete announcement from LandBridge/PowerBridge regarding the progress of approvals, the final project structure, or a long-term data center lease. Then it would be much easier to assess how much of today’s valuation is already attributable to Alpha Digital.