

Hello everyone,
Just in time for the weekend, here’s another industrial stock from the U.S.
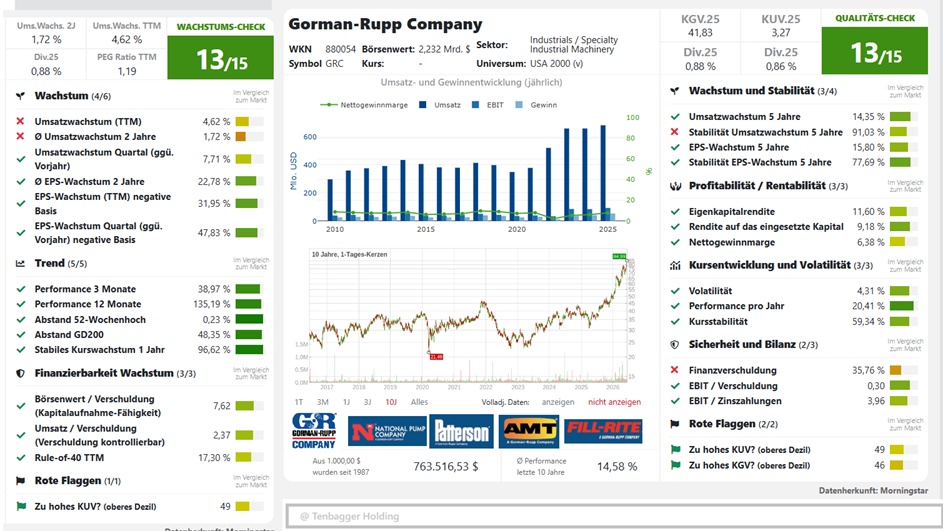
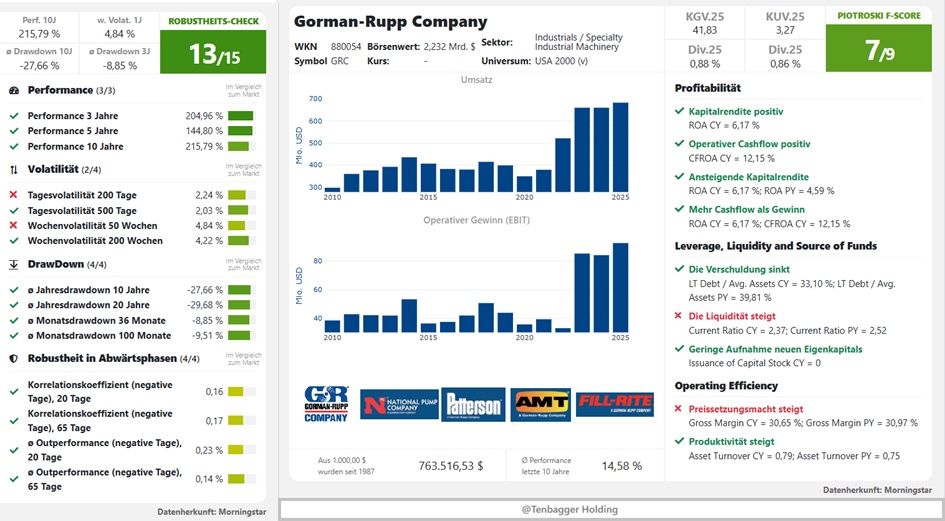
The great thing about this stock is that, thanks to its solid and growing business model and strong product portfolio, it excels in three categories of the Traderfox Check.
Scoring 13 out of 15 points in each of three categories is relatively rare. That’s why I really wanted to introduce this company to you.
I’m especially looking forward to your comments here.
The Gorman-Rupp Company, founded in 1933, designs, manufactures, and sells pumps and related equipment (pump and motor controls) for use in water, wastewater, construction, drainage, industrial, petroleum, original equipment, agriculture, fire protection, heating, ventilation, and air conditioning (HVAC), military, and other fluid handling applications from locations in the United States, Canada, the Netherlands, Belgium, Ireland, and South Africa. The company markets these products through its wholly owned subsidiaries and a broad network of dealers, through manufacturer’s representatives, through third-party distributor catalogs, and through direct sales in the U.S. and internationally.
Overview
• Founded in 1933 by J.C. Gorman and H.E. Rupp
• Headquarters: Mansfield, Ohio, USA
• Operates in 6 countries
• Approximately 1,415 employees worldwide
• Sales in 140 countries
• Annual dividend increase for 53 consecutive years
• New York Stock Exchange: GRC
• Chairman: Jeffrey S. Gorman
• President and CEO: Scott A. King
Mission Statement
The Gorman-Rupp Company was founded on a philosophy and commitment to product quality and technological leadership in the pump industry. Gorman-Rupp’s philosophy regarding growth and service is reflected in the mission statement of co-founders J.C. Gorman and H.E. Rupp, which reads: “To deliver a quality product, competitively priced, delivered on time, backed by reliable service, with a profit that provides a fair return for our shareholders, and to provide our employees with competitive wages and benefits.” Fulfilling this promise has laid the foundation for the Gorman-Rupp Company to become a global leader in pumps, with the company continuing to emphasize customer education and training as part of the sales process.
Focus on Product Quality and Customer Service
• Leading designer and manufacturer of pumps and pump systems
• Reputation for high-quality products and outstanding customer service
• Certified, state-of-the-art testing facilities
• Emphasis on customer education and training
• Over 5,000 pump models
• More than two million square feet of design, production, and distribution space worldwide • Strategically located international facilities
• Investment in research and development with a history of innovation
Product Diversity The company’s product line includes pump models ranging in size from 1/4 inch to nearly 15 feet and with flow rates from less than one gallon per minute to over one million gallons per minute. The types of pumps the company manufactures include self-priming centrifugal pumps, standard centrifugal pumps, magnetically driven centrifugal pumps, axial and mixed-flow pumps, vertical shaft-driven turbines, submersible pumps, high-pressure boosters, rotary gear, rotary vane, diaphragm, bellows, and oscillating pumps.
NEWS
24.04.2026: Gorman-Rupp Company erklärt Bardividende
04/24/26: The Board of Directors of the Gorman-Rupp Company has...
26.04.2026: Gorman-Rupp berichtet Finanzergebnisse des ersten Quartals 2026
04/23/26: Gorman-Rupp Company reports financial results for the first quarter...
06.02.2026: Gorman-Rupp berichtet Finanzergebnisse für das vierte Quartal und das gesamte Jahr 2025
02/06/26: The Gorman-Rupp Company reports financial results for the fourth quarter...
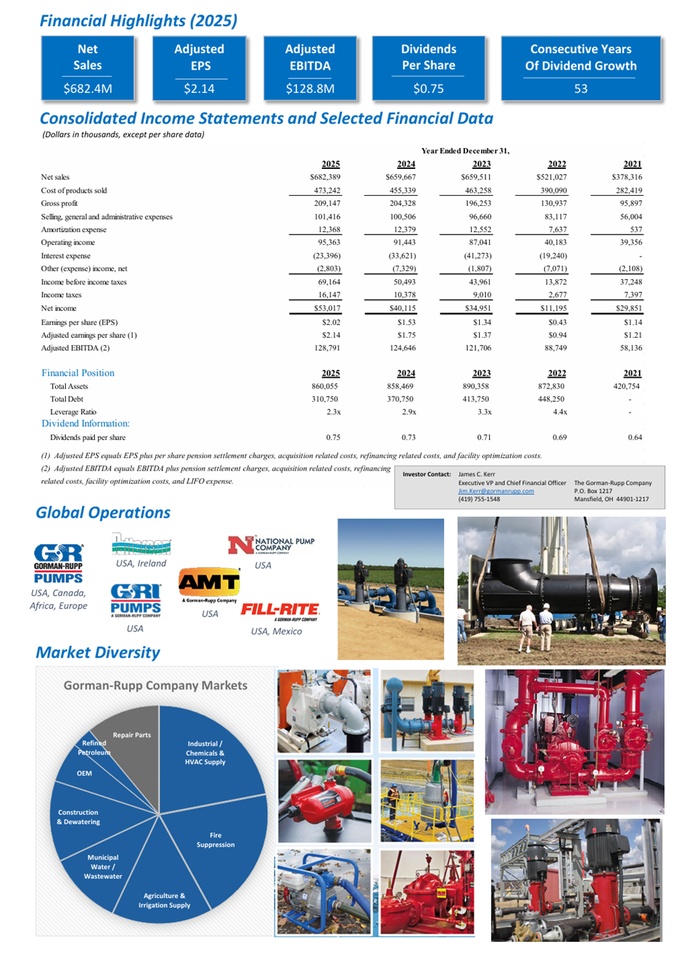
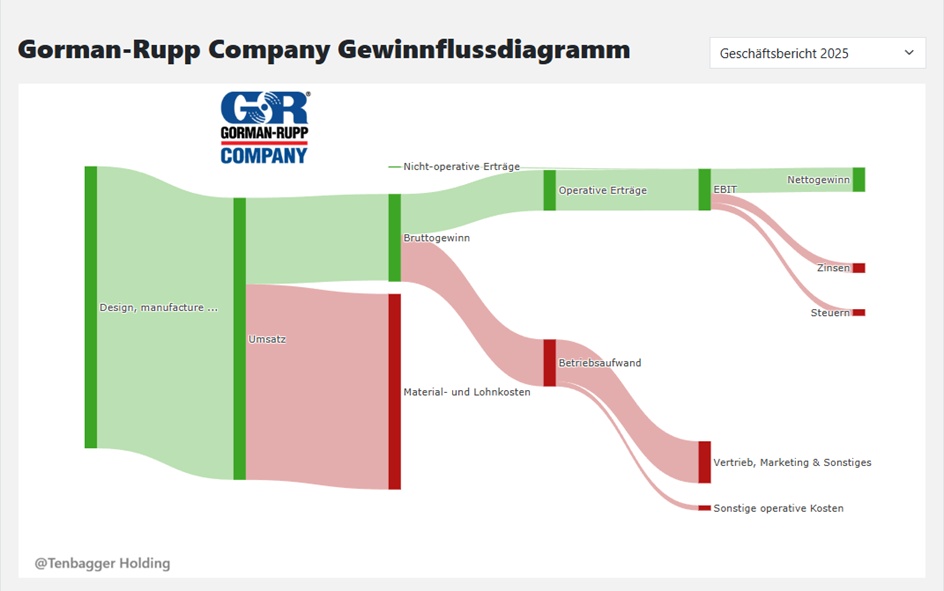
In the last fiscal year, The Gorman-Rupp Company’s revenue increased by 3.4% from $659.7 million to $682.4 million. Net income rose by 32.2% from $40.1 million to $53.0 million. The net profit margin was thus 7.8%, compared to 6.1% in the previous year. On April 27, 2026, The Gorman-Rupp Company reported its Q3 results for the quarter ending March 31, 2026. Revenue for the reporting period was $176.6 million (+7.7% compared to the same quarter last year) and profit was $17.8 million (+47.1% compared to the same quarter last year).
2026
2027 2028 2029 2030
Revenue
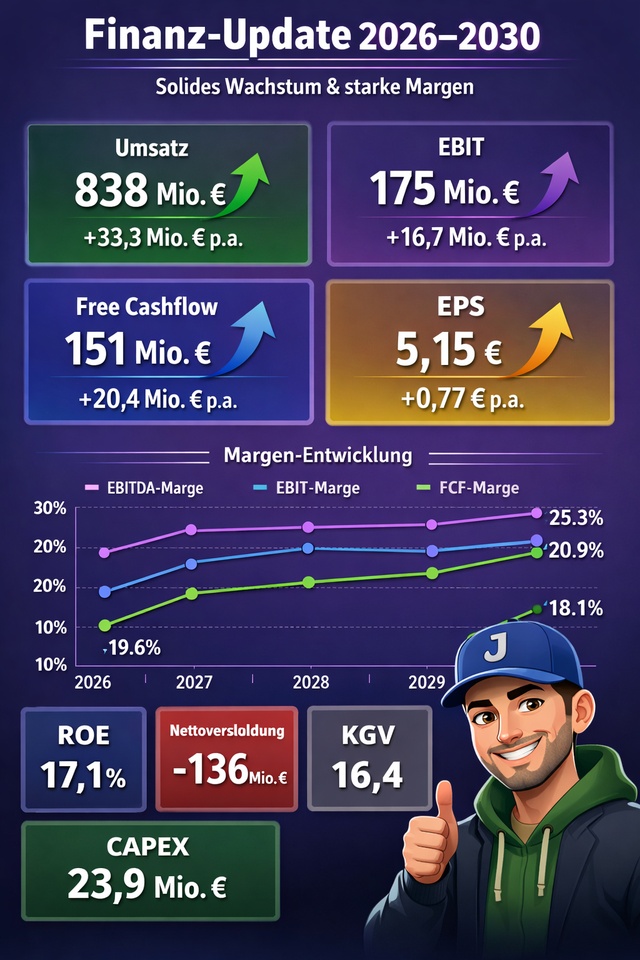
721.20 756.42 773.10 805.10 838.40
Δ
+38.81 +35.22 +16.68 +32.00 +33.30
2026
2027 2028 2029 2030
EBIT 110.11 121.17 144.30 158.50 175.20
Δ +11.79 +11.06 +23.13 +14.20 +16.70
2026
2027 2028 2029 2030
Net income
68.82 77.18 93.10 112.50 132.20
Δ
+15.80 +8.36 +15.92 +19.40 +19.70
2026 2027 2028 2029 2030
Net debt
211.17 145.40 75.50 -14.10 -136.20
Δ
+7.97 -65.77 -69.90 -89.60 -122.10
2026
2027 2028 2029 2030
CAPEX
21.55 19.70 23.50 22.90 23.90
Δ —-
1.85 +3.80 -0.60 +1.00
2026
2027 2028 2029 2030
Free Cash Flow
83.06 90.16 109.00 130.90 151.30
Δ —
+7.10 +18.84 +21.90 +20.40
2026
2027 2028 2029 2030
EBITDA margin 19.6% 20.2% 23.2% 24.2% 25.3%
EBIT margin
15.3%
16.0% 18.7% 19.7% 20.9%
FCF margin
11.5% 11.9% 14.1% 16.3% 18.1%
2026
2027 2028 2029 2030
ROE
14.9% 14.9% 15.7% 16.8% 17.1%
2026
2027 2028 2029 2030
EPS
2.63 2.95 3.60 4.38 5.15
Δ
+0.61 +0.32 +0.65 +0.78 +0.77
2026
2027 2028 2029 2030
P/E
32.12 28.64 23.50 19.31 16.43
Juan’s Conclusion (short and sweet, just the way you like it)
Gorman-Rupp delivers a solid, steady growth package. Revenue, EBIT, and profit are rising steadily every year, while net debt is consistently shifting toward net cash—a strong signal. Margins are clearly improving, especially the FCF and EBIT margins, which shows that the business model is becoming more efficient. EPS is growing reliably, and the P/E ratio is falling year after year, even as earnings rise. Classic quality compounder look with an ever-improving valuation range.
Performance:
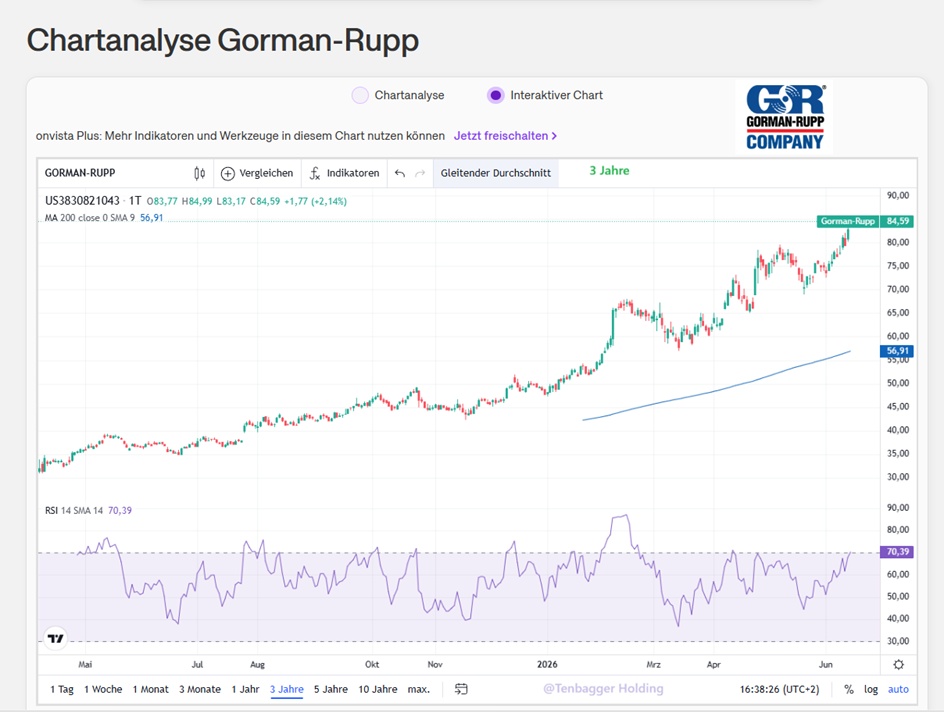
1 week +9.73%
1 month +11.45%
6 months +70.61%
1 year +130.24%
3 years +213.06%
June 12, 2026, 10:00:02 PM •
NYSE (USD)
$84.59
June 12, 2026, 11:20:22 •
Lang & Schwarz (EUR)
73.00 EUR


