10Mes·

Is it Christmas already🎁 Monopolist at a P/E ratio of 3.6, with growth and dividends to boot

Hello my dears,

It almost feels like Christmas. Because I was already looking for a surprise for you today 🎁.

A company with a net profit growth of 134% and a P/E ratio of 3.6.

On top of that, there is a great and rising dividend.


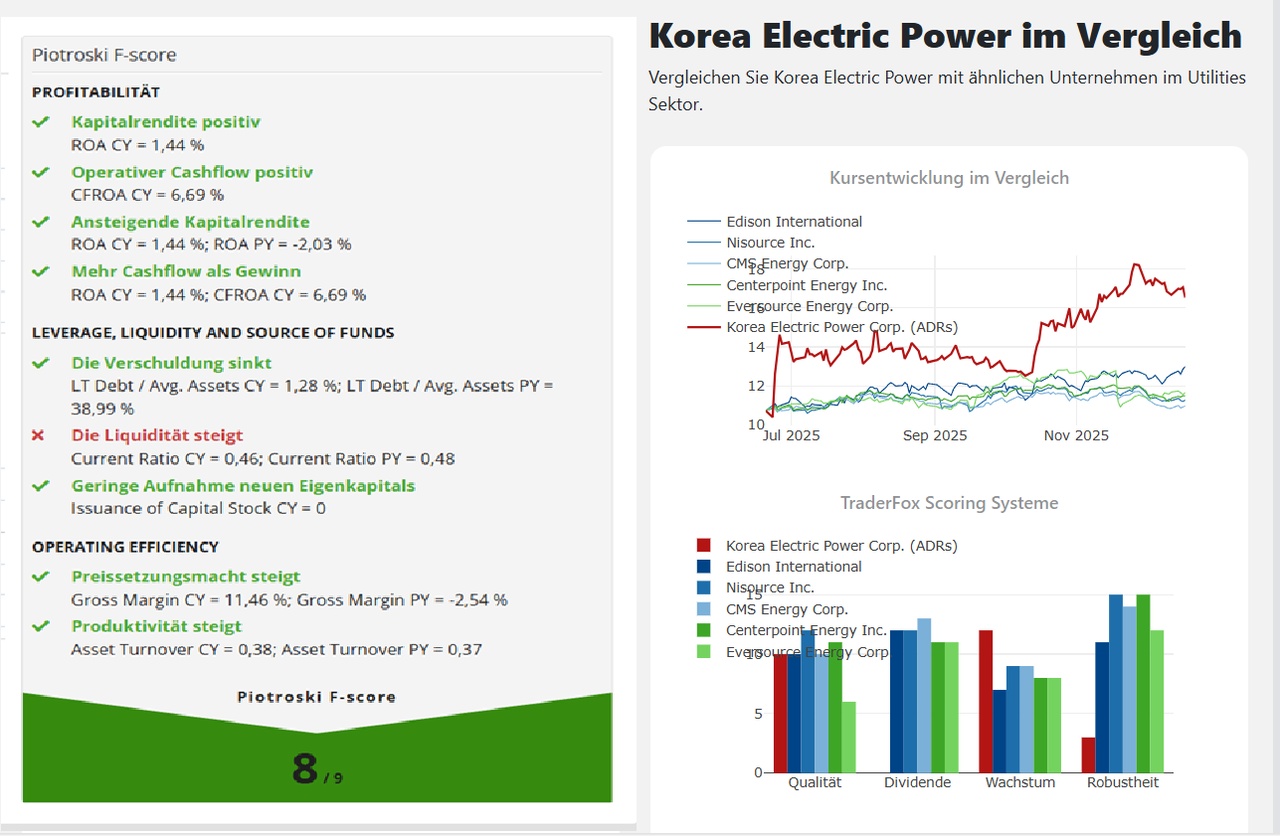
For comparison, I have listed some companies from the sector below.


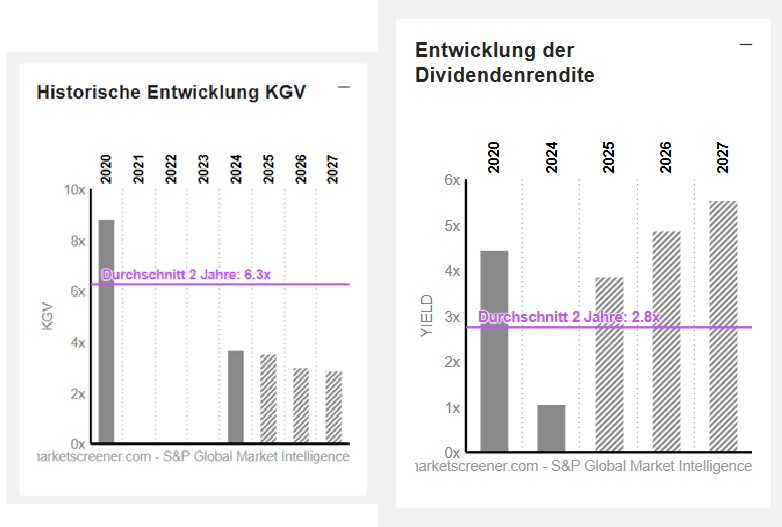
So that you can see how well the company has already developed, I have also added historical figures for margin and earnings per share.


A great surprise for me would be plenty of comments and opinions on the company.


Perhaps also a gift for our dividend investors.

@Dividendenopi
@SAUgut777
@Max095

$KEP (+1,06%)

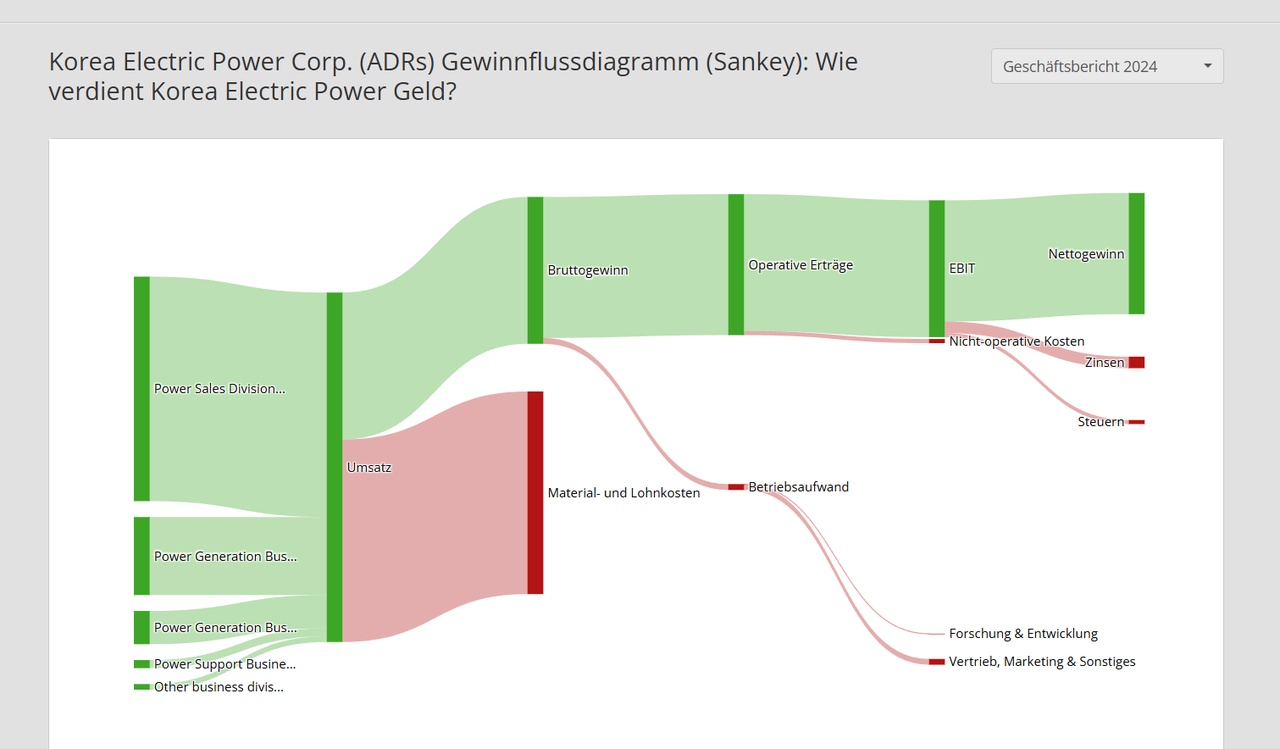
Korea Electric Power Corp is a Korea-based company principally engaged in the sale and supply of electricity. The company operates its business through four segments. The electricity sales business segment is engaged in the sale and supply of electricity and the development of energy resources, among others. The Nuclear Energy business segment is active in the areas of nuclear energy, hydropower and pumped-storage power generation. The Thermal Power operating segment is active in the field of electricity generation such as hard coal, anthracite coal, liquefied natural gas (LNG) and others. The Other operating segment is involved in the planning of power plants, the maintenance of power generation plants, the supply of nuclear fuel, the provision of information and communication technologies (ICT) for power generation, the operation of renewable and solar power generation plants and the emission of greenhouse gases.

Number of employees: 21,914


Korea Electric Power does not lower electricity tariffs despite falling energy prices - share could now end consolidation!

(23,07,2025)


Korea Electric Power Corporation (KEPCO) is the largest electricity supplier in South Korea and has assets of almost KRW 250 trillion (approx. USD 184 billion). It has a monopoly on the transmission and distribution of electricity in South Korea and has a dominant market share of 62% in electricity generation.


In recent years, its results have been affected by the fact that it has not been able to pass on all price increases to customers due to its public utility mandate. However, at the end of June, the company announced that, despite the recent significant fall in energy prices, it would not be lowering its current electricity tariffs for the third quarter but maintaining them, which should lead to a further improvement in KEPCO's financial stability.


The news from the end of June, which led to an up-gap, has now been consolidated. In my opinion, trend following can be used here. (KEP)
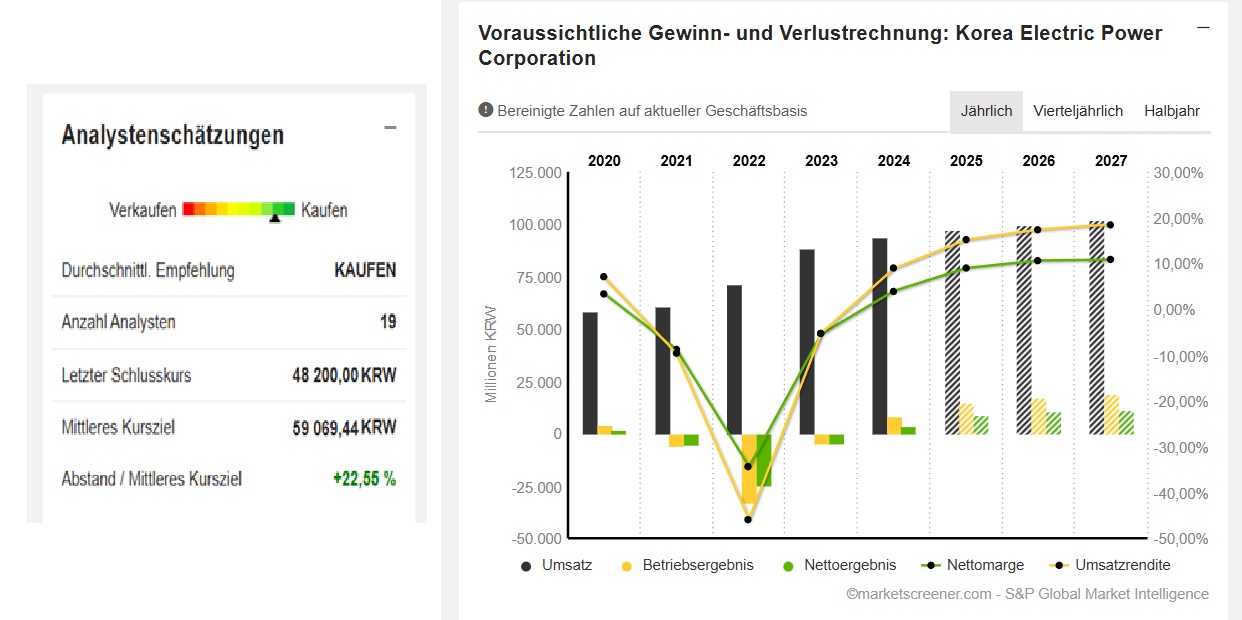
attachment

KRW in billions2KRW in millions

Estimates


year
Turnover
Change in

2025 97 520 3,74 %

2026 99 719 2,26 %

2027 101 945 2,23 %


Year
EBIT
Change in

2025 14 787 77,11 %

2026 17 335 17,24 %

2027 18 887 8,95 %


Year
Net result
Change in

2025 8 779 134,21 %

2026 10 607 20,82 %

2027 11 043 4,11 %


Year
Net debt
CAPEX

2025 124 161 17444

2026 118 519 19035

2027 112 857 19887


Year to date
Free cash flow
Change in

2024 1 660 079 113,4 %

2025 8 562 425 415,78 %

2026 7 821 114 -8,66 %

2027 7 803 462 -0,23 %


Year
EBIT margin
ROE

2024 8,88 % 9,22 %

2025 15,16 % 19,83 %

2026 17,38 % 19,48 %

2027 18,53 % 18,51 %


Year
Earnings per share
Change in

2024 5 439 172,4 %

2025 13 495 148,12 %

2026 15 880 17,67 %

2027 16 607 4,57 %


Year
P/E RATIO
PEG

2023 -2.52x 0x

2024 3.69x -0x

2025 3.57x 0x

2026 3.04x 0.2x

2027 2.9x 0.63x


Year
Dividend p share
Yield

2025 1 858 3,86 %

2026 2 357 4,89 %

2027 2 674 5,55 %

No. of shares (in thousands) 641,964

Market value 30 942 669


Market Cap in € 17,88 Mrd. EUR


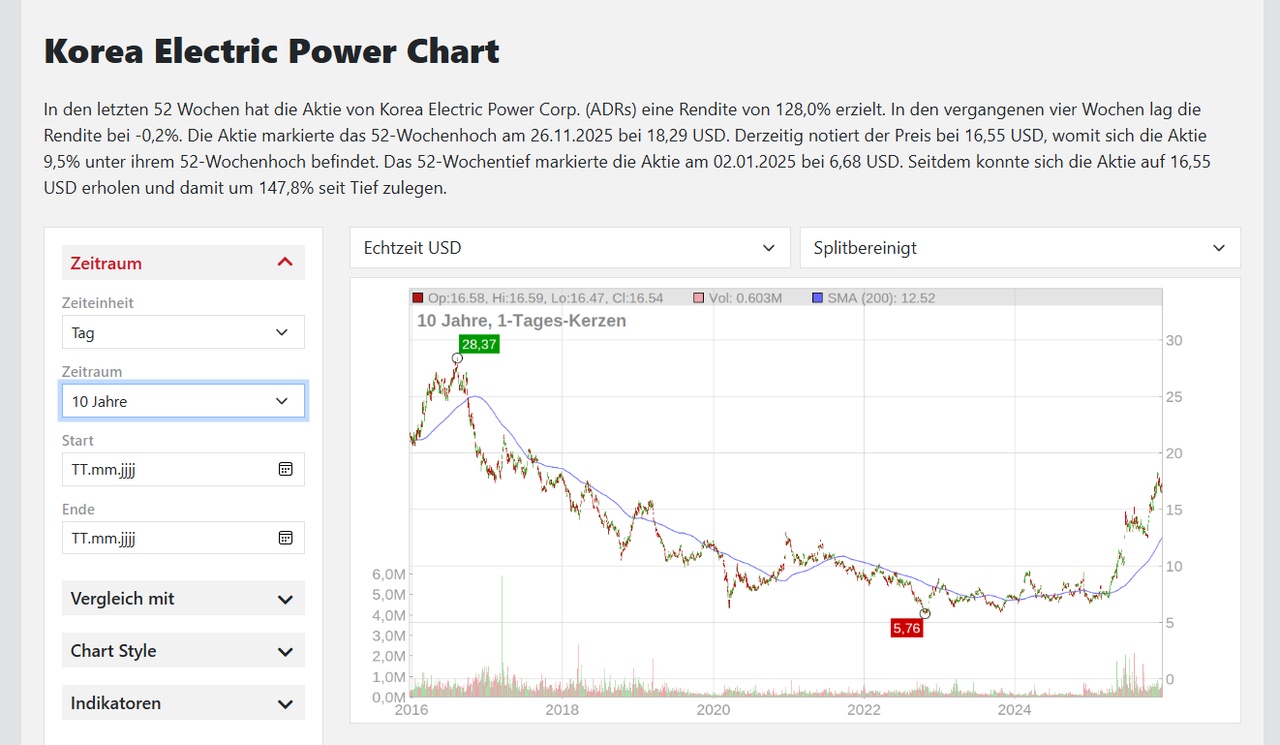
Performance: 6 months 50% 12 months 100%


SECTOR COMPARISON


NEXTERA ENERGY

P/E ratio 23.44x

Dividend yield 2.8

Cap. 168 bn


GE VERNOVA INC.

P/E ratio 83.34x

Dividend yield 0.15

Cap. 173 bn


IBERDROLA, S.A.

P/E ratio 18.57x

Dividend yield 3.83 %

Cap. 139 bn


CONSTELLATION ENERGY CORPORATION

P/E ratio 39.38x

Dividend yield 0.43 %

Cape 113 bn


ENEL S.P.A.

P/E ratio 12.72x

Dividend yield 5.61 %

Cap. 102 bn


SOUTHERN COMPANY

P/E ratio 20.67x

Dividend yield 3.38 %

Cap. 96.04 bn


DUKE ENERGY CORPORATION

P/E ratio 18.6x

Dividend yield 3.62 %

Cap. 91.41 bn


AMERICAN ELECTRIC POWER COMPANY, INC.

P/E ratio 18.85x

Dividend yield 3.24 %

Cap. 61.73 bn


VISTRA CORP.

P/E ratio 33.94x

Dividend yield 0.56

Cap. 56.3 bn
attachment
attachment


attachment


attachment


attachment


attachment
37
17 Commenti

immagine del profilo
Where do you keep pulling out the titles 🤔🙃👍.... I think the express train has already left the station and the jumps in the figures are reflected in this year's share price and the outlook is no longer so rapid. Utilities are always interesting, especially in the long term. Suitable for young investors to invest in this sector and in Asia. Unfortunately nothing for me, until the current meager dividend generates real cash flow I won't be around for a long time. Due to a lack of children or other heirs, there is also no inheritance😇😂. In my next life, I'll start investing at the age of 18 and there will be many of your stocks among them
•
10
•
immagine del profilo
@Dividendenopi
Oh, you disappoint me. I chose the value especially for you for Christmas. Remember, the company has as good as a monopoly. And there are also AI and data centers in South Korea. I think the estimates are too conservative. Take a look at the P/E ratios in the sector. There is still plenty of room for upside.
•
1
•
immagine del profilo
@Tenbagger2024 My dearest, I will certainly have to disappoint you more often😓. I have great respect for all your work and the great presentations. As already mentioned, if I were much younger, I would have some of your stocks in my portfolio. I am cash flow focused. I know, of course I can also achieve this with stocks that are constantly gaining and then sell at a profit. Even if I sometimes gamble, max. 5% of my capital, then that's the gambling child in me and not the goal of building up assets. I have the assets, live off them and can't "afford" a zero before the decimal point in the dividend 😉🤷‍♂️
•
1
•
immagine del profilo
The risks: Why the stock is dangerous (Contra)
1. the political price tag (the main reason not to buy) 🚫 KEPCO is not a normal company that raises prices when costs rise.

The South Korean government controls electricity prices.

The problem: When oil/gas are expensive (input costs rise), the state often doesn't allow a price increase for the end customer to keep inflation low and not anger voters.

The result: KEPCO makes billions in losses, even though they are a monopolist. They are effectively subsidizing the Korean industry at the expense of shareholders.

2. the mountain of debt 📉 Due to the above-mentioned policy, KEPCO has accumulated a gigantic mountain of debt in recent years (especially during the 2022/23 energy crisis). The interest burden is putting massive pressure on profits.
•
7
•
immagine del profilo
After 2026, however, things look very bleak with more lush growth. Fundamentally favorable valuation, yes. But this obviously also reflects significantly lower growth. Not for me.
•
2
•
immagine del profilo
@All-in-or-nothing
Well . I think the estimates are very conservative and still leave plenty of room for improvement. Data centers are also being built in Korea. And energy demand is growing there in particular. And the company has virtually no competition.
••
immagine del profilo
@Tenbagger2024 I rather think, based on what I read in your introductory text with regard to price restrictions etc., that the lush growth following the fall in prices is now over. For me, this is also reflected in the estimates.🤷🏼‍♂️ Unfortunately, I find it difficult to imagine "explosive" future growth here, with virtually no pricing power (as it is obviously restricted by the state).
••
immagine del profilo
@All-in-or-nothing
So I still see upside potential for the share
•
1
•
immagine del profilo
@Tenbagger2024 That's the nice thing about personal assessments, that they can be quite different.
•
1
•
immagine del profilo
A very low P/E ratio compared to the other stocks. However, I see future growth as rather moderate, comparable with quality stocks.
•
2
•
immagine del profilo
An energy company valued so favorably?👀 A great find!
•
1
•
immagine del profilo
@Neyney
And with a monopoly
•
1
•
immagine del profilo
@Tenbagger2024 I think I'll open a savings plan soon
••
immagine del profilo
@Neyney
Let's see if there are any comments from the community on the value. But the P/E ratio is tempting for such a company
•
1
•
immagine del profilo
@Tenbagger2024
What's going on today? 🤑
••
Utente eliminato
10Mes
Il commento è stato cancellato
immagine del profilo
@Iwamoto
Wait and see. When Buffet gets in, you'll say, I wish I'd been invested.
••
Partecipa alla conversazione