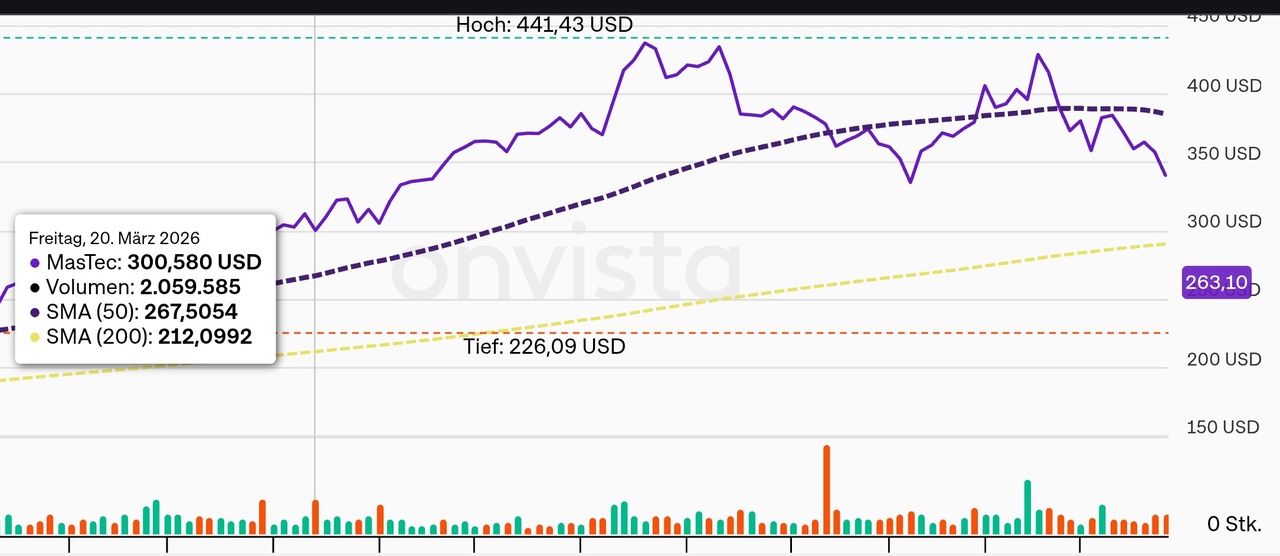
MasTec (MTZ) shares
fell 16% in after-hours trading on Thursday after the infrastructure construction company raised its full-year revenue and adjusted earnings guidance—though the updated projections still fell short of Wall Street estimates.
Management now expects revenue of approximately $18.2 billion for 2026, up from the $17.5 billion forecast issued in April, but below Wall Street’s consensus estimate of $18.46 billion.
The company also raised its forecast for adjusted earnings per share to $9.30, up from $8.79 in April. Nevertheless, this outlook also falls short of the Wall Street consensus estimate of $9.52, although management emphasized that it remains confident in the long-term growth prospects.
The improved forecast follows continued strength in several end markets. MasTec (MTZ) reported a record order backlog of $21.4 billion for the next 18 months, up 30% from the previous year, driven by strong demand in the renewable energy, power transmission, and data center infrastructure sectors. Last week, the company completed the acquisition of electrical contracting firm The Superior Group, further expanding its presence in data center construction and other infrastructure sectors.
Second-Quarter Results
MasTec (MTZ), which builds communications networks, power transmission systems, pipelines, and renewable energy infrastructure, reported second-quarter revenue of $4.37 billion, a 23% increase from the previous year and above the Wall Street consensus estimate of $4.31 billion.
Adjusted earnings per share were $2.22, compared with $1.49 a year ago, but slightly below the consensus estimate of $2.23.
Net income rose to $130.1 million, or $1.65 per share, compared with $85.8 million, or $1.09 per share, in the prior year.
Chief Executive Officer Jose Mas said: “We have once again delivered a very strong quarter with excellent performance in revenue growth, margin expansion, and order backlog.”
The company also expects full-year net income of approximately $539 million, or $6.20 per share. Adjusted earnings before interest, taxes, depreciation, and amortization (EBITDA) are estimated at approximately $1.6 billion, corresponding to an adjusted EBITDA margin of 8.8%. These forecasts are based on the updated outlook of approximately $18.2 billion in revenue and adjusted earnings per share of $9.30.
The Clean Energy and Infrastructure segment led the growth, with revenue up 43% year-over-year. The Pipeline Infrastructure segment grew by 19% and nearly doubled its segment profitability. Revenue in the Communications segment rose by 6.2%, albeit with declining margins, while the Power Delivery segment grew by 19%.
Management stated that the acquisition of The Superior Group strengthens MasTec’s capabilities in electrical infrastructure for data centers and expands its presence in the healthcare, entertainment, and industrial sectors, positioning the company for
further long-term growth.