5Mes·

Share price turbo ignited by AI memory boom and Axcelis merger! Get in today?

Hello my dears,

Veeco Instruments today announces its quarterly results for the most recent quarter.


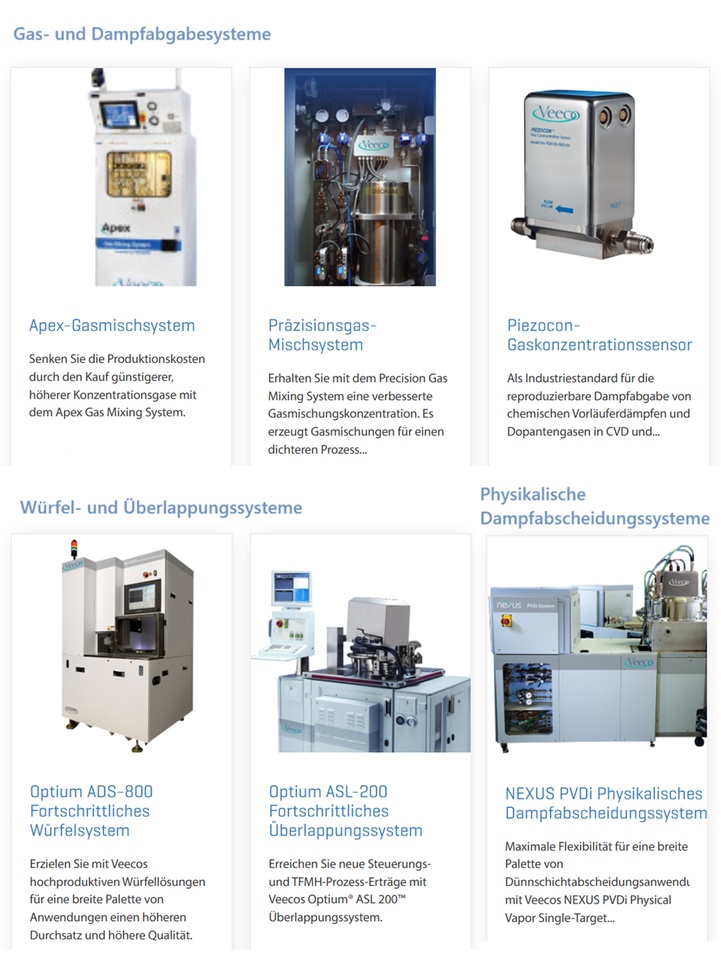
That's why Juan visited the company for you in advance.


There may be a good opportunity to get in today.


Do you like the fact that we are presenting a company to you before the figures?

Feel free to share your thoughts on the company in the comments.


$VECO (+2,34%)

Veeco Instruments is a specialized supplier to the semiconductor industry, providing laser processing and ion beam technologies for chip manufacturing. On March 24, the share price rose dynamically after major orders for laser spike annealing systems (LSA) were confirmed by leading DRAM manufacturers. The company is benefiting massively from the expansion of capacities for high-bandwidth memory (HBM), which is essential for AI accelerators. With a record order backlog of USD 555 million and a sales forecast for 2026 of up to...


Veeco Instruments Inc. (ISIN: US9224171002) is a manufacturer of equipment for the semiconductor and data storage industries. Its highly specialized production systems are sold to chip manufacturers, research institutions and industrial customers. The company was founded in 1945. In 1994, the shares were placed on the NASDAQ.

The figures for Q4 2025 were presented on February 25, 2026. At USD 165 million, revenue was around 9 % down on the previous year. Profits were also weak, falling by 41% to USD 0.24 per share. Overall, the figures show a negative revenue and profit trend, but only marginally missed expectations.


It was already reported on October 1, 2025 that Veeco is planning a mega-merger with Axcelis Technologies to create a new, more scaled semiconductor equipment champion. The deal will be completed by the second half of 2026. Veeco shareholders will receive the equivalent of Axcelis shares upon completion. In addition to the merger, both shares are currently driven by the AI boom and the increasing demand for advanced packaging, photonics and nanostructures.


Conclusion: The merger transforms Veeco from a niche provider to a potential platform player and addresses the key technologies behind AI chips. This makes Veeco one of the winners of the nanotechnology trend, which is expected to enable the next generation of chip trends. In combination with the ongoing AI investment cycle, this results in a story that is clearly geared towards future growth despite current operational weakness.


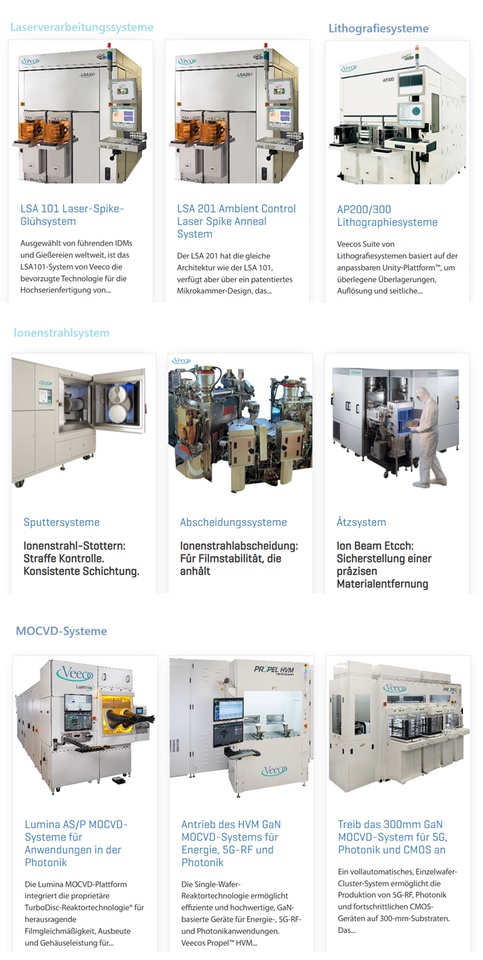
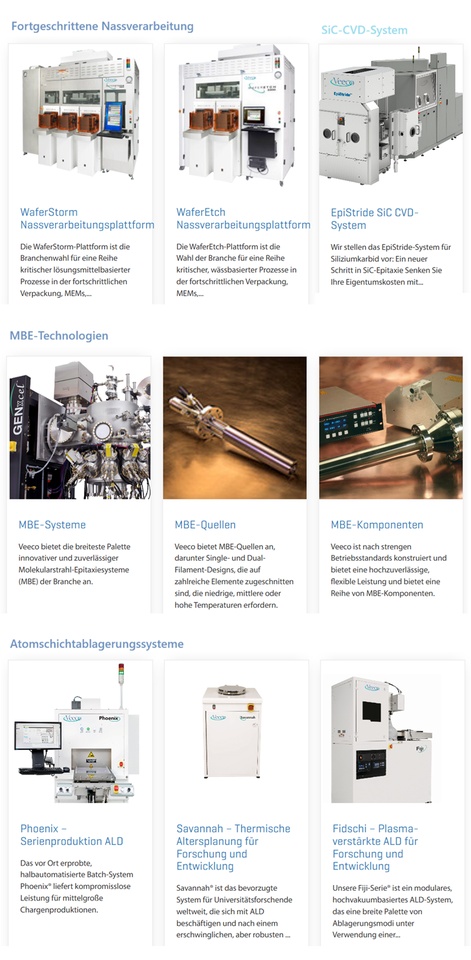
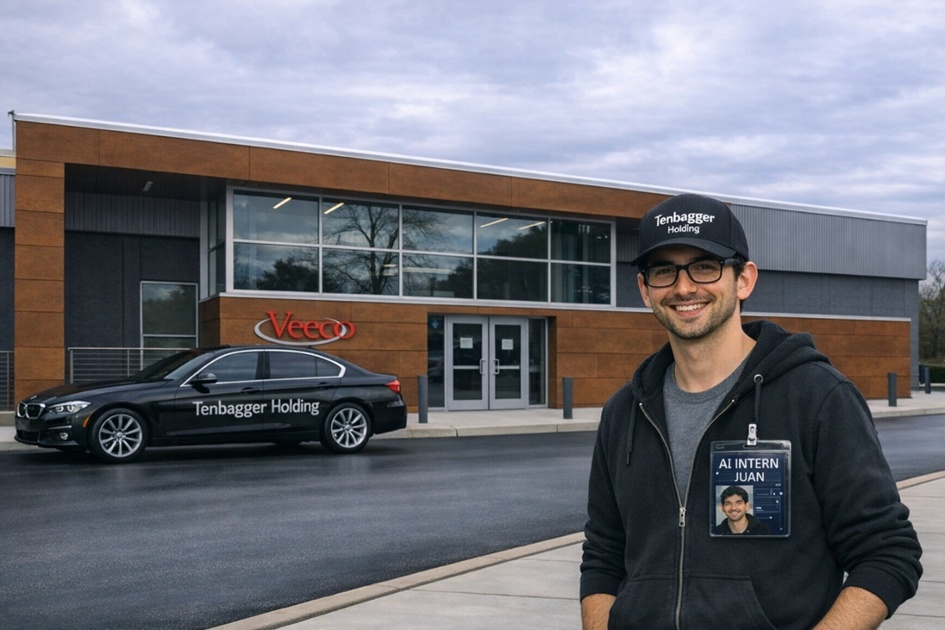
Veeco Instruments Inc. is a manufacturer of process equipment for the semiconductor industry. The company's laser annealing, ion beam, chemical vapor deposition (CVD), metal organic chemical vapor deposition (MOCVD), single wafer etching and cleaning, and lithography technologies play an important role in the manufacturing and packaging of advanced semiconductor devices. The company's system products include Laser Annealing Systems, Ion Beam Systems and Etch Systems, Advanced Packaging Lithography, Single Wafer Wet Processing, Metal Organic Chemical Vapor Deposition Systems, Molecular Beam Epitaxy Systems, Atomic Layer Deposition Systems and Other Systems. Other deposition systems include Physical Vapor Deposition, Diamond-Like Carbon Deposition and Chemical Vapor Deposition Systems. The company's process equipment is used to manufacture a range of microelectronic components, including logic, dynamic random access memory (DRAM), photonics, power electronics and other semiconductor devices.

Number of employees: 1,265


Veeco offers a wide range of advanced semiconductor processing solutions, systems and sources, including laser processing, lithography, ion beam deposition, MOCVD, wet processing, MBE, ALD (atomic layer deposition), PVD, dicing, lobes and gas delivery systems. These technologies are designed to meet the evolving needs of the semiconductor and related industries - from advanced node devices to photonics and data storage.
attachment
attachment


attachment


Services & Support

At Veeco, we believe in making a significant difference by providing excellent service, being a trusted partner and offering unparalleled technology solutions. Our certified Field Services Engineers provide local support to a worldwide installation base for around-the-clock coverage that keeps your R&D or manufacturing goals on track.


How Veeco makes a significant difference

Around the clock and around the world coverage

  • Global technical product support experts who quickly manage escalations and hard-to-solve issues
  • Access to spare parts with global presence, 24/7 access and fast deliveries
  • Quick solution for installations to enable fast ramps

Improve and expand your capabilities

  • Renovate and repair local programs to reduce your ownership costs and shorten turnaround times
  • Capital Extension program available to expand your current install base with the latest features.

Comprehensive coverage from world-class field engineers

  • Performance guarantee programs such as guaranteed ownership costs or uptime
  • Production support programs to back up your tool or fleet in the event of problems with proactive workforce planning and parts planning
attachment


attachment


Quanteninnovation vorantreiben: Veecos Fortschritte in der Materialtechnik für die nächste Ära der Computertechnik


March 06, 2026 | News


Veeco bucht Multi-System Lumina und Spector Bestellungen zur Herstellung von Indium-Phosphid (InP)-basierten optischen Komponenten

March 02, 2026 | News


Veeco-Aktionäre genehmigen Fusion mit Axcelis

February 06, 2026 | News


Wusstest du, dass Veecos Produkte eine entscheidende Rolle bei der Qubit-Herstellung spielen?

February 05, 2026 | News


Veeco und imec entwickeln ein 300-mm-kompatibles Verfahren, um die Integration von Bariumtitanat auf Siliziumphotonik zu ermöglichen

January 27, 2026 | News


Veecos Laser Spike Annealing (LSA)-System, ausgewählt von einem führenden Halbleiterspeicherunternehmen für eine fortschrittliche DRAM-Bewertung

December 2025 | News

Presentation of the Axcelis + Veeco merger

PDF herunterladen(öffnet sich in neuem Fenster)


Veeco investor presentation

PDF herunterladen(öffnet sich in neuem Fenster)
attachment


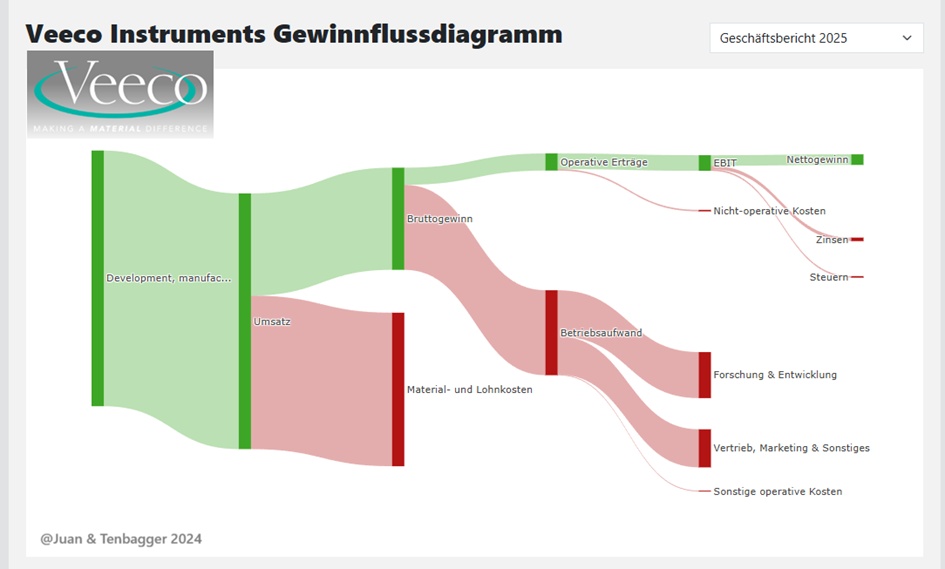
Geographical distribution of turnover:

2025 (USD)

Rest of APAC 330 million

China 182 million

USA 101 million

Europe, The Middle East 50.79 million

Rest of World 118,000 thousand
attachment


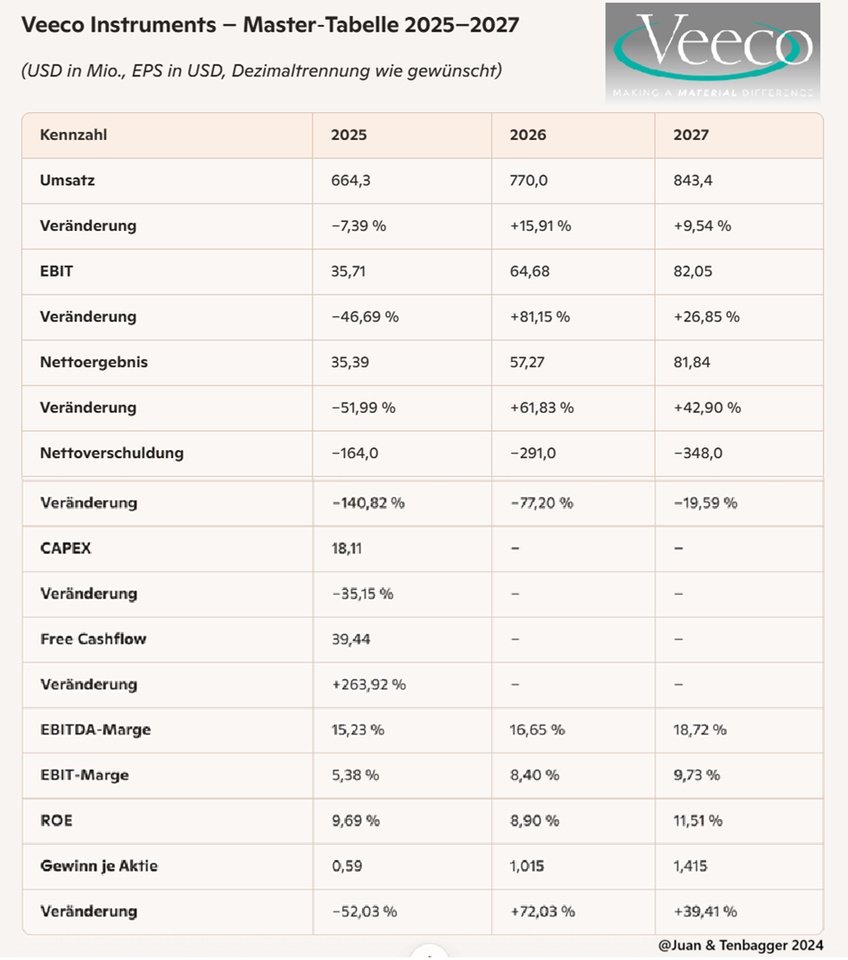
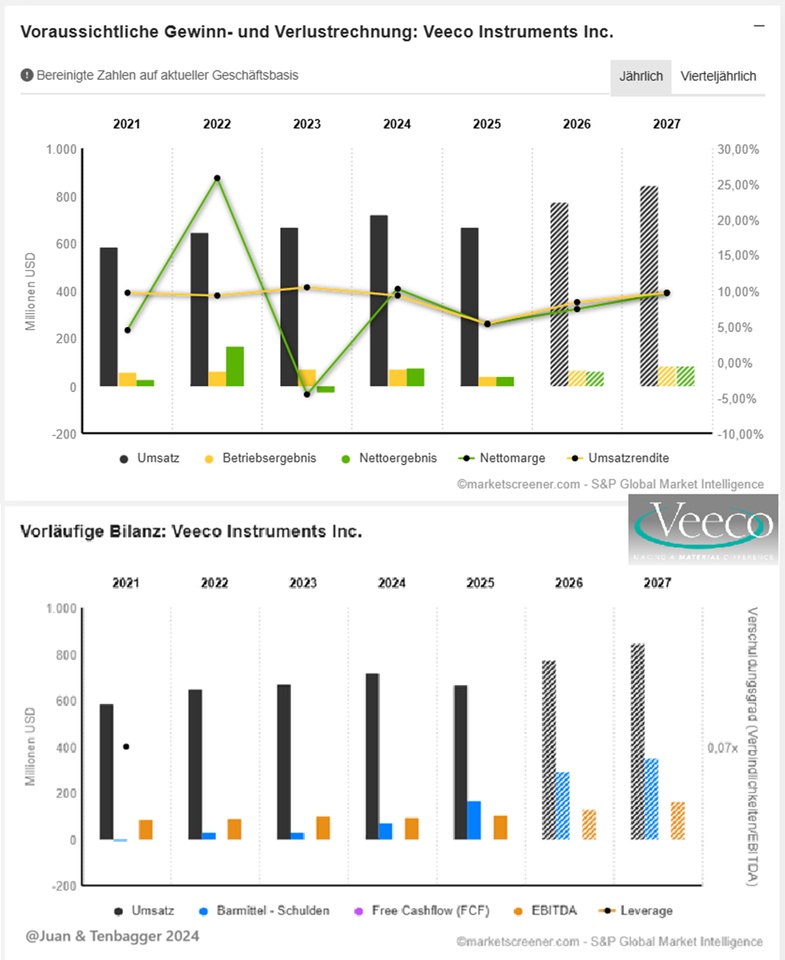
🎙️ Juan's conclusion on Veeco's key financial figures (2025-2027)


"Veeco is playing like a team in rebuild mode that suddenly starts winning again."

  • 2025 is the reset year: Sales down, EBIT down, profit halved - but free cash flow explodes. It's like a team that scores fewer goals but suddenly plays more efficiently.
  • 2026 brings the turnaround: Sales +16%, EBIT +81%, profit +62%. This is a classic momentum swing - the offense comes back.
  • 2027 confirms the trend: Double-digit growth, rising margins, ROE back in double digits. The team has regained confidence and is playing forward in a structured manner.
  • Net debt becomes more negative every year:
    Veeco is reducing debt like a team stabilizing its defense.
  • Margins rise cleanly: EBITDA margin of 15.2% → 18.7%. That's a sign of quality - the gaming facility is becoming more efficient.
  • EPS grows strongly: 0,59 → 1,015 → 1,415. The top scorer delivers again.

Juan's overall verdict:

"Veeco is not a high-flyer, but a team that improves year after year. 2025 is the low point - after that it's a clear upward trend. For the championship, this would be a classic underdog with an upward trend."
attachment
attachment


Market value 3,004

Number of shares (in thousands) 60,392

Date of publication 25.02.2026


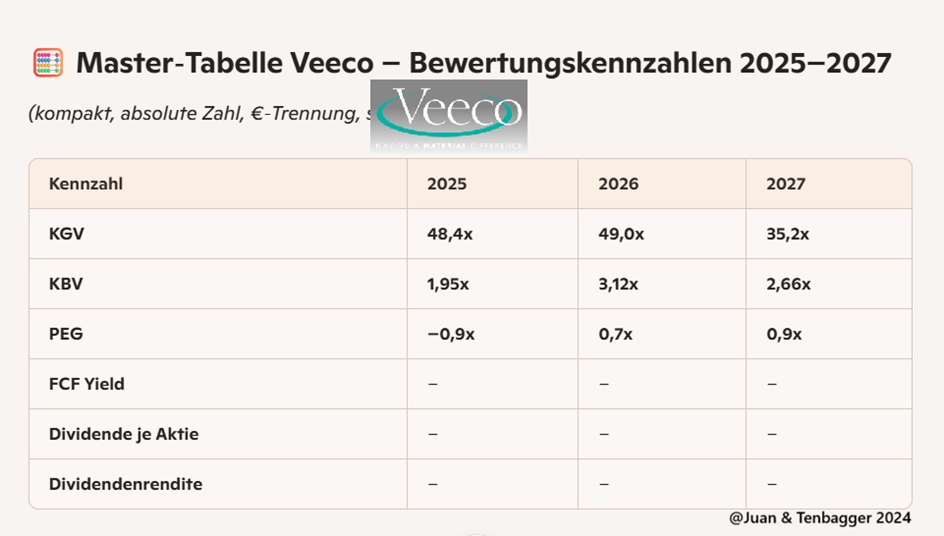
🎙️ Juan's conclusion on the valuation ratios (2025-2027)

"Veeco is a typical growth player: expensive at the beginning, more reasonable at the end."

P/E RATIO: 2025 and 2026 look like premium prices, 2027 multiple drops significantly. The team will not become cheaper, but the valuation will adjust to the rising profits.

P/E RATIO: Jumps high in 2026, normalizes again in 2027. Investors pay for growth, but not blindly.

PEG: Negative in 2025 (due to profit decline), cleanly in the green from 2026. This is the moment when the model makes sense again.

Dividend & yield: Zero over all years. Veeco plays purely on growth, not payout.

FCF Yield: Not reported. MarketScreener clearly shows: focus on operating performance, not cash return.


Juan's overall assessment:

"Valuation high, but not irrational. From 2027, Veeco looks like a growth stock that is finally slipping into a fair zone."


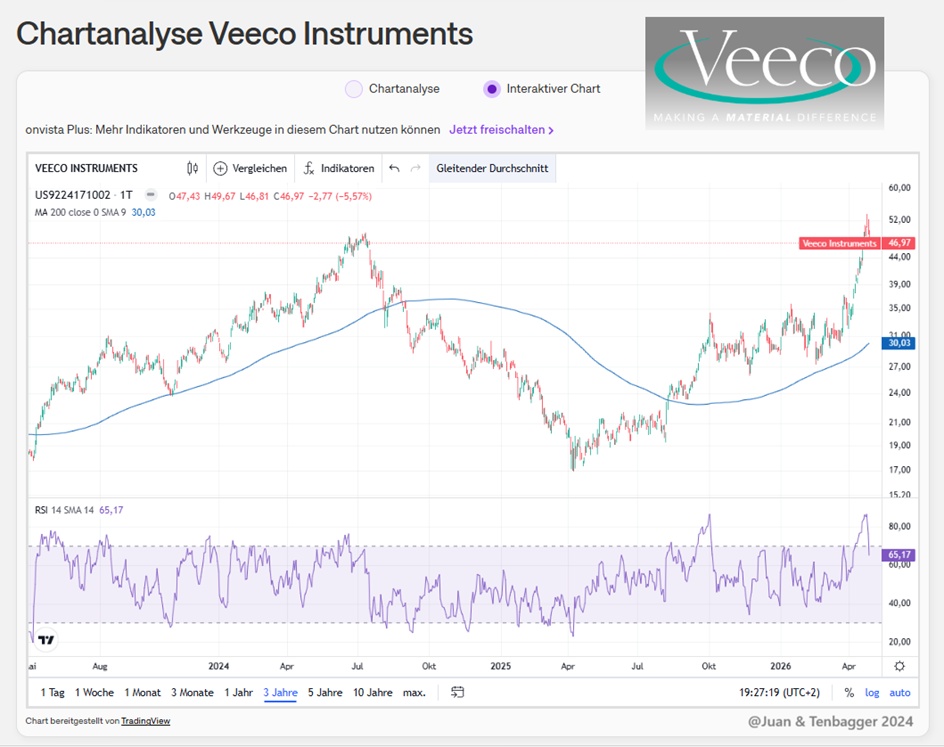
Performance

1 week +6.44 %

1 month +41.03 %

6 months +70.17 %

1 year +156.92 %

3 years +170.92 %
attachment


PRICE: 43.71€ (05.05.2026 11:30 a.m.)


$VECO (+2,34%)

13
12 Commenti

immagine del profilo
Thank you for the introduction my dear

The Reaper Check is on top

Tenbagger, Jack again ✌️wir We really do see each other every day. Can you still meet my highest demands?
Here comes the execution.

💀 THE VERDICT: REBUILD OR HYPE TRAP?
Veeco is currently playing like a team in rebuild mode, clearing fundamental debris to attack again from 2026. While 2025 is seen as a "reset" with falling sales (-7.39%) and halved profits, the operating leverage is set to ignite massively thereafter. However, anyone who gets in now is already paying for the "championship" of 2027 in advance.

🧬 DNA-CHECK & TRANSFORMATION
- The turning point (2026): After the low point in 2025, EBIT is expected to explode by +81.15% with sales up by around 16%. This indicates strong operating leverage.
- Cash flow sensation: Despite falling profits in 2025, free cash flow is expected to increase by +263.92% to USD 39.44m.
- Defensive (balance sheet): The balance sheet is the fortress; net debt is negative and is expected to grow to USD -348m by 2027 (net cash).
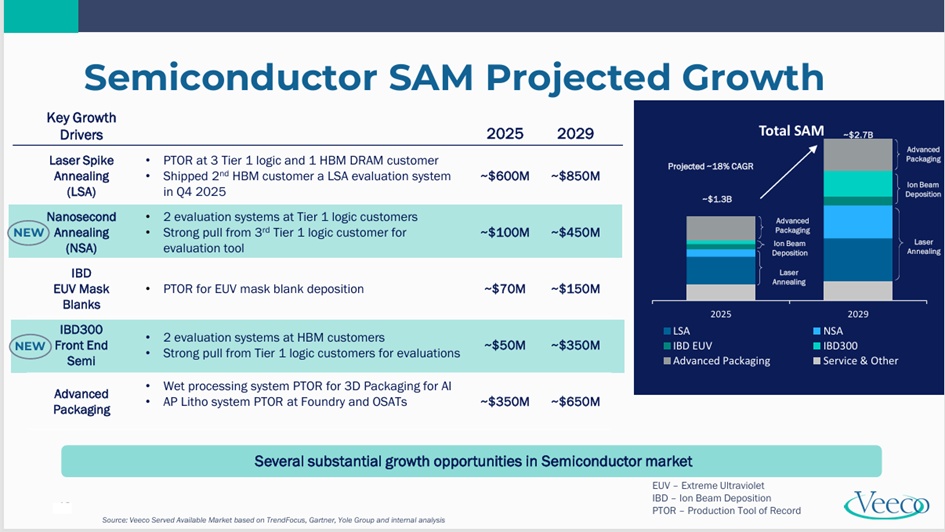
- Growth driver: The addressable market (SAM) for semiconductors is expected to grow at a CAGR of 13% until 2029, primarily driven by laser and nanosecond annealing for AI applications.

📐 VALUATION REALITY
- P/E horror show: With a P/E ratio of 48.4x for 2025, the share is currently extremely expensive. The multiple will not fall to a more moderate level of 35.2x until 2027 due to earnings growth.
- PEG ratio: From 2026, the model becomes mathematically attractive with a PEG of 0.7 to 0.9, provided the massive growth promises materialize.
- Geographic lump: The focus is strongly on APAC, with China remaining a political risk area at USD 182m (2025).

🧠 REAPER SUMMARY
RATING: WATCH
REAPER SCORE: 5/10

Jack's Mustard:
The share has run hot (+156% over 1 year). The fundamental turnaround is visible, but has already been largely anticipated in the share price. An entry is only advisable if there is a setback towards the dust-off limit of € 34.50 in order to smooth out the risk/return profile.
The story of the 'underdog with an upward trend' sounds nice, but with a P/E ratio of 48 you are not buying an underdog, but a star purchase with star allure. Wait until the hype cools down
•
3
•
immagine del profilo
Yes, I find ideas before the figures interesting. But at $VECO, after over 40% price gains in the last 4 weeks, everything has to be right for the figures. That's why I wouldn't necessarily get in today before the figures.
•
2
•
immagine del profilo
@Multibagger Maybe even, Sell good news, @Dividendenopi
•
2
•
immagine del profilo
•
1
•
immagine del profilo
@schlimmschlimm What do you think?
•
1
•
immagine del profilo
@schlimmschlimm $FTC today minus 20%
••
immagine del profilo
@Tenbagger2024 Hmm...my thoughts on this, I haven't looked at everything in detail yet, but it has already run a long way and is highly valued. Figures will be published today after the close, a sell the news with an RSI of 75 is almost a textbook scenario. Or is it? And if the figures trigger a sell the good news, i.e. are good, then that would of course possibly be an interesting dip. But it would have to go down quite a bit. I think it makes sense from € 37? Before that, no...., definitely not. But it doesn't really tickle me as a complete package, I think there are currently at least 10 better opportunities 😉
•
2
•
immagine del profilo
@Tenbagger2024 VECO: AI superstar or balance sheet mirage?
Ticker: $VECO (Veeco Instruments) | Rating: WAIT / HOLD ✋
Analyst summary: A first-class technological asset in a second-class balance sheet guise.
________________________________________
🛡️ THE INSTITUTIONAL SCORECARD (20-point check)
- Green-to-Red ratio: 35 % 🟢 (7 out of 20 metrics positive)
- Status: YELLOW (increased vigilance required)
Metric status Forensic comment
Sales trend 🟡 2025 reset (-7.4 %) vs. 2026 hopeful guidance.
Earnings Quality 🔴 Warning anchor: GAAP profit almost fully financed by SBC.
Working Capital 🔴 Receivables (+14%) increase contrary to sales (-7%) -> Channel Stuffing?
Balance sheet strength 🟢 Fortress: Net cash position (~164m USD).
RSI (Technical) 🔴 Massively overbought at ~78. The FOMO trap is snapping shut.
________________________________________
🧬 INVESTMENT NARRATIVE: THE "NANOSCALE ENABLER"
Veeco supplies the shovels for the gold rush. Without their laser annealing technology, there would be no yield in HBM (high bandwidth memory) or 2nm chips. They control the heat where nanometers decide over billions.
Growth levers & catalysts:
- HBM4 cycle: Veeco is set for the next generation at SK Hynix and Samsung.
- S&P upgrade: Presence in the S&P SmallCap 600 attracts institutional flows; a mid-cap upgrade is the long-term goal.
- AI leverage: The SAM (Serviceable Addressable Market) is growing at 13% CAGR due to AI workloads.
________________________________________
🔍 FUNDAMENTAL DNA ANALYSIS
- DNA check: Over 800 patents. A technological moat that even giants like Applied Materials ($AMAT) cannot simply fill in.
- Margin monster (potential): Non-GAAP margin of ~18% shows what's possible when fixed costs scale with rising sales. But: The real GAAP margin of 5.4 % is a reminder to be humble.
- Blue-chip customers: TSMC, Samsung, Intel. Whoever is in the process flow here is virtually irredeemable.
________________________________________
📉 THE REALITY OF THE FIGURES
- Cash flow: Looks great with a 2.47x conversion (OCF/NI), but is artificially inflated by USD 35 million in stock-based compensation (SBC). There is no new cash flow, only fewer salaries are paid out in cash.
- Valuation (P/E ratio): A GAAP P/E ratio of 48x for 2025 is a "championship valuation" for a team that is just planning to rebuild.
- PEG ratio: For 2026e arithmetically attractive at 0.7 - 0.9 - if management delivers the 16% growth.
________________________________________
🚀 TENBAGGER-MATRIX (Frank-Matrix)
- Total score: 69 / 120
- Verdict: Not a Tenbagger candidate. Why. The niche size limits the upside scaling potential and the high dilution slows down the EPS leverage. Veeco is a quality compounder, not a moonshot.
________________________________________
⚠️ RISKS & TACTICAL ENTRY
The Reaper conclusion: You are not buying an underdog here, but a star purchase with star allure at the highest price.
1. geopolitics: 24% China share is a permanent sword of Damocles.
2. technology: The RSI is crying out for a cool-down.
🎯 Buy zones (dip strategy):
- From €37.60 ($44.00): Realistic entry (gap fill).
- From €34.50 ($40.00): Technical support buy.
- From €29.00 ($34.00): Audit floor / no-brainer zone.
________________________________________
Closing Statement:
Don't listen to the marketing blah-blah of "adjusted earnings." Look at cash flow and receivables. Veeco is technologically brilliant, but currently a hype trap price-wise. Wait for the dip.
•
2
•
immagine del profilo
@schlimmschlimm I always like your analysis better. I also like the colored dots
•
3
•
immagine del profilo
@Tenbagger2024 Thank you! I'm working on it. :-)
•
2
•
immagine del profilo
@schlimmschlimm @Aktienhauptmeister It's good that I do so many shows. So you always have material to improve your prompt family
•
2
•
immagine del profilo
@Tenbagger2024 Yes absolutely, you have no idea how many times I have insulted the AI in the worst way in the last weeks/months because of the crap it has served me. Soon I'll be banned...lol
•
3
•
Partecipa alla conversazione