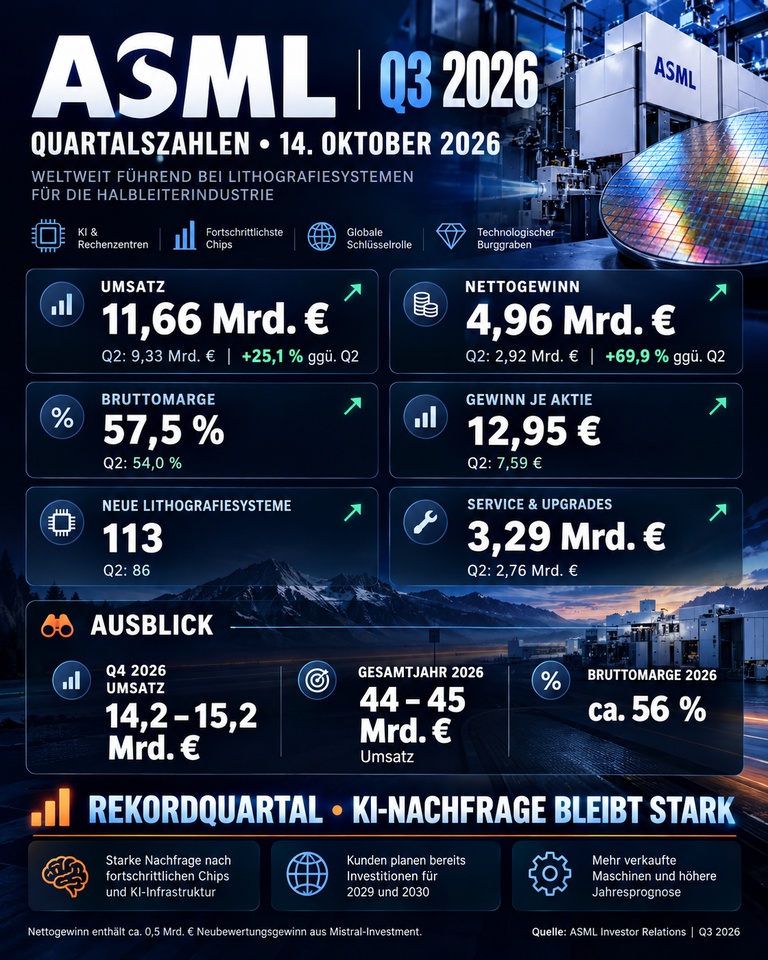
The new quarterly figures from $ASML (-0,26%) show the key role the Dutch company plays in the global chip industry.
Revenue in the third quarter of 2026 rose to 11.66 billion euros, and net income to 4.96 billion euros. Particularly impressive: The gross margin improved to 57.5%.
What particularly convinces me as an investor, however, is not just the look back, but above all the outlook:
ASML is raising its revenue forecast for 2026 to 44 to 45 billion euros. Revenue of 14.2 to 15.2 billion euros is even expected for the fourth quarter.
Why is this so interesting?
Without ASML’s state-of-the-art lithography systems, the most advanced chips cannot be manufactured in this form. Whether it’s AI, data centers, or more powerful processors—ASML occupies a pivotal position in the technological value chain.
Of course, one must not ignore the valuation. An outstanding company isn’t automatically a good buy at every price. Especially after sharp price increases, market expectations can be very high.
My conclusion: For me, ASML remains one of the most exciting quality stocks in the semiconductor sector. The numbers and the outlook are fundamentally positive. Now it comes down to what the market has already priced in.
What’s your take on ASML?
Would you continue to add to your position at current levels, or would you rather wait for a pullback?
#ASML
#Aktien
#Börse
#KI
#Halbleiter
#LangfristigInvestieren