1Settimana·

Portfolio beats work 📈👨‍🔬

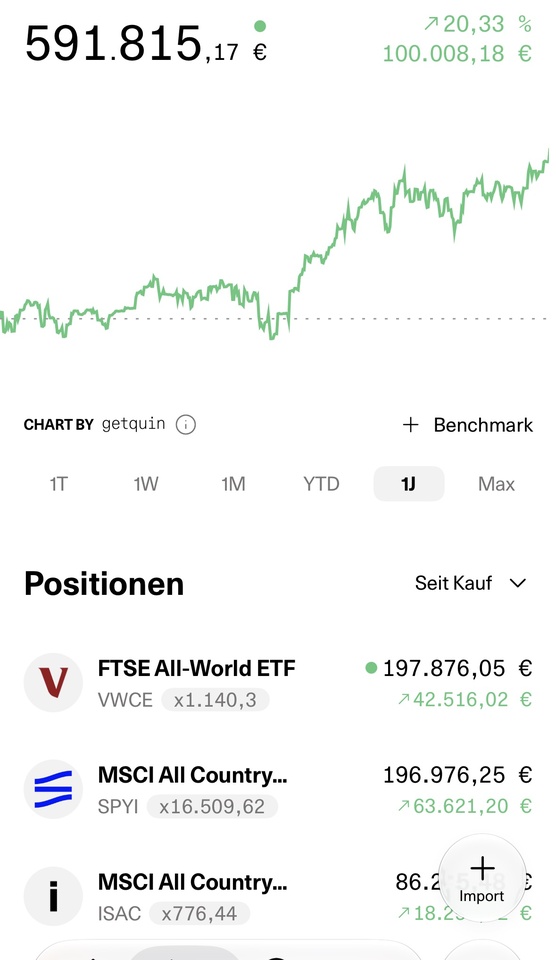
Over the past 12 months, our portfolio has, for the first time, generated more income than my wife and I have earned through our jobs.

Of the 100,000 euros, 11,000 euros alone came from compound interest. Right now, its impact is really noticeable. I’m enjoying the moment and am curious to see where this tightrope walk between the AI revolution and the debt crisis will take us next.

Have a great Wednesday and stay on top of things ⚽️💪🏼
attachment
142
80 Commenti

immagine del profilo
1Settimana
Just wait until your portfolio loses your entire annual income. Then you'll feel like you've worked for nothing. 😈
•
69
•
immagine del profilo
@Epi I don't think I'll feel that way.
Once I've spent 200k, I'm going to treat myself to a nice steak 😉
•
5
•
immagine del profilo
@Epi However, this feeling can also arise for reasons related to the company's structure. ☺️
•
1
•
@Epi Here’s a little anecdote: I got a promotion in April 2025, which meant about 250 € more a month. Well, you all know what happened around that time. Keyword: Liberation Day. Within a short time, my portfolio plummeted by 140k at its peak, but I was expected to be happy about it.
That didn’t feel quite so good, but since I’m not really dependent on my portfolio, it didn’t bother me all that much.
•
4
•
immagine del profilo
@Solitair What really matters is having the resilience to stick it out.
I don’t think I’d have any trouble with that amount of volatility. But the small “dips” since 2020 have always been so brief that I can’t really imagine what it would feel like to be in the red for several years in a row.
That certainly isn’t exciting for anyone.
•
1
•
immagine del profilo
1Settimana
@Wealth-Accelerator Ich kann dir sagen, dass es ab drei Jahren kontinuierliche Verluste im Jahreslohnbereich psychologisch schwierig wird. Irgendwann hält man den Stress nicht mehr aus, verkauft alles und will nie wieder was mit Aktien zu tun haben.
•
9
•
immagine del profilo
@Epi With a 50-year investment horizon, that’s likely to happen more than once.
I’m really curious to see how it will feel. I think I’m prepared. But how would anyone really know? 😂
•
3
•
immagine del profilo
1Settimana
@Wealth-Accelerator Behavioral finance has an answer: Losses hurt about twice as much as gains of the same amount. So: Take your current joy, double it, and turn it into pain. 😏
•
4
•
immagine del profilo
@Epi I know the theory 😉
But I've also seen my balance drop by 50k in a short amount of time, and it didn't bother me one bit.
I get really excited about big jumps up. And I see temporary, high losses as just a relaxed part of the game.
Like I said, the length of time I’m “underwater” is what I find psychologically intriguing.
•
1
•
immagine del profilo
1Settimana
@Wealth-Accelerator Then you're already well-prepared. 👍
The underwater time itself isn't really the problem psychologically. What's much harder is the direction you're heading in during that time. When you keep going down and down, with no end in sight, that's when it gets tough.
•
2
•
immagine del profilo
@Epi That's what I'm assuming.
Then Getquin will be pretty empty, too 😅
•
2
•
Visualizza tutti 24 ulteriori risposte
Congratulations, all in all—including realized gains, dividends, and capital gains—I'm at 140k year-to-date. My meager civil servant's salary can't keep up with that.
•
4
•
immagine del profilo
@Solitair That's really intense. YTD, I'm also close to 100k. It feels a bit surreal, but that's why I got started in the first place.
I just thought it would take 15 years for something like this to happen, not 7. 🤯
•
1
•
I'm enjoying the calm before the big bang for as long as I can—I don't even understand why I'm still supposed to work 😆 This is the land of milk and honey.
•
3
•
immagine del profilo
1Settimana
@asset_sage_smmad The trick is simple: keep buying stocks when the market crashes. Then you'll profit twice as much when it rebounds. ;) That's what a real land of milk and honey looks like.
•
3
•
Stark - I like it !!!
•
3
•
immagine del profilo
1Settimana
One of the best feeling 🚀
•
2
•
For me, it's over €110,000 in 12 months. Crazy. It makes it hard to take my work even halfway seriously and to go out of my way because of the comparatively low average salary.
•
2
•
immagine del profilo
@Wehyernese I still think it's really nice when my living expenses are covered by my job.
But I'm open to that changing in the future 😅
••
immagine del profilo
Congratulations. Over the past 12 months, my portfolio has lost 2,703 euros 😅
•
2
•
immagine del profilo
@DonkeyInvestor Wow! What's the main reason for you? Bitcoin?
••
@DonkeyInvestor Don't spend it all at once
•
1
•
immagine del profilo
@DonkeyInvestor Well, I've made a start. That's already half a 400-euro job. And soon that'll double 👌🏻
•
1
•
immagine del profilo
@Wealth-Accelerator My incompetence 👍. And a little bit of Bitcoin, too
•
2
•
immagine del profilo
@Solitair I already did that
•
1
•
immagine del profilo
@Bezehgombjuderstimme Did you see the minus sign?
•
1
•
immagine del profilo
@DonkeyInvestor No! 😂 Okay, well, I still hope it turns positive soon. Were you speculating wildly, or what caused it to drop?
••
immagine del profilo
@Bezehgombjuderstimme The Bitcoin chart looks extremely unfavorable over a 12-month period. YTD, for example, my portfolio looks much better, up 55k. In March, my portfolio hit its low point so far.
•
1
•
immagine del profilo
A Portfolio Beats Stock Picking! 😊💪
•
1
•
immagine del profilo
@MozartsGeist I had to learn that the hard way, too. Luckily, though, I felt like I understood the stock market pretty early on—only to suffer a total loss on both a stock and a cryptocurrency, which then shrunk my confidence in the stock market down to ETF size 😊😂
••
Congratulations. That’s THE dream!! Four more years like this, and financial freedom is within reach. Knock on wood—let’s hope we’re not in some massive bubble like in 2000/2001. That really scares me. A 20% return on a global ETF, driven mainly by AI stocks. I hope this is just me panicking unnecessarily, like I do every year. 🙏🏽❤️


May I ask how old you are and at what age you could imagine stopping work?
•
1
•
immagine del profilo
@Therealbroka Thank you!
We’re a modest 34…
And I’ve already drafted—or rather, simulated—a sort of plan here:

https://getqu.in/F6Ytf0/

I can tell you that, in principle, I already feel financially free. The only thing holding me back is my home.
If I were to sell it tomorrow, I think I’d be very close to that goal. And the second thing is perhaps the issue of health insurance.

Over time, I’ve lost the desire to stop working.
My wife and I have both taken extended periods of parental leave. We’re both currently working part-time, and I’ve already taken three short sabbaticals.
And I just finished reading the book *Die with Zero*, which represents a complete contrast to the accumulation of wealth I’ve pursued over the last 10 years.

I’m at the point where I’m enjoying the moment, where I’m starting to “enjoy” spending money again, and so on.

Still, I’d like to reach a net worth peak of around 2 million by the time I’m 45.

I think that’s possible without having to give up any more things beforehand.

I share your fear of a bubble! I can easily imagine that a single domino could take everything away from us again. But I also believe I’m prepared for that.
•
1
•
@Wealth-Accelerator Interesting simulation. I agree with you—no job is a burden on the mind, but the type of work can be adjusted. From high-paced large corporations with hefty executive salaries to working part-time at a bar just for fun… that’s what I mean by quitting because of financial freedom.

I’m guessing the daily fluctuations in your portfolio have been outpacing your savings rate for quite some time now, right? Doesn’t it make more sense to just let the money work for you and use all the money from your savings rate for spending right here and now?
•
1
•
immagine del profilo
@Therealbroka I agree with you. That said, I’ve actually found a part-time program management role within the corporate group’s top management that works out really well for me.

And as you said, we kicked this off for ourselves pretty much exactly in September 2026, because that’s when we started getting things back on track. Our vacations have also reached a new spending level.
Still, I’m trying to keep some small savings plans going. Right now, to expand my exposure to gold. And even 250 euros a month makes a difference when I look at it in isolation.

But basically, we’re now at the point where we’re firmly allocating all our fixed income into our spending budget to upgrade our lifestyle or our freedom. And only “unplanned” income continues to go into our savings.
•
1
•
immagine del profilo
Damn, do you both work part-time (40%)?

Joking aside—congrats!! 🎉🎉 May the stock market continue to
be on your side 😎
•
1
•
immagine del profilo
@GeldGenie No joke 😉
Both are currently working part-time 😋

Thank you! 👍🏼💪🏼
••
immagine del profilo
@Wealth-Accelerator Not a bad decision, but it wouldn't be for me. The opportunity cost would simply be too high for me. If it works for you guys—great! :-)
••
immagine del profilo
@GeldGenie It's mainly because we're taking care of a one-year-old who isn't in preschool yet 😉
••
immagine del profilo
1Settimana
What a milestone! Having your portfolio out-earn your job must feel pretty rewarding. Happened for me in less than a month.
•
1
•
immagine del profilo
@KaiRock Sounds Amazing! Congratulations 💪🏼
••
immagine del profilo
Wonderfull feeling, deserved congratulations!
•
1
•
immagine del profilo
••
1Settimana
You should always expect a real return of 5% per year over the long term—that’s definitely achievable. Sometimes it’s higher, sometimes lower. No reason to quit or panic... ;-)
•
1
•
Mostra la risposta
immagine del profilo
Congratulations! May I ask why you have several global ETFs in your portfolio instead of just one? ☺️
•
1
•
Visualizza tutti 2 ulteriori risposte
immagine del profilo
THAT'S great—congratulations. Of course, you’d only benefit “directly” from it if you were to withdraw the profits—which, of course, you don’t do. The idea is to keep growing it “more and more.” That might turn out to be a trap, especially in old age—because, as the saying goes, you can’t take it with you. The saying “Always live first class—otherwise your heirs will” is also worth considering, at the very least. For myself, I have a vast number of dividend-paying stocks with strong diversification in my portfolio. Some of it certainly gets reinvested time and again, but some stays in my checking account for day-to-day expenses. The whole thing continues to grow, though—and that’s the point. As long as I’m still earning money and don’t need to supplement my pension in case of unexpected expenses—everything’s fine. But I like your approach. Spreading it across just two stocks without further diversification would be a little too risky for me, even if there’s certainly no need to fear a drastic “crash” with these stocks. Something like that usually happens gradually at first and then accelerates.
•
1
•
Mostra la risposta
Crazy Congratulations
•
1
•
Mostra la risposta
immagine del profilo
Good job!
•
1
•
Visualizza tutti 2 ulteriori risposte
immagine del profilo
Did you even take into consideration inflation? You probably didn’t earn as much as your think? Also maybe your not earning enough in your day job
••
Mostra la risposta
Partecipa alla conversazione