
Almonty Industries stock is under heavy pressure: At $8.22 (Nasdaq close on November 13, 2026), they are trading about 66% below their 52-week high of $24.41 set in April, even though the company’s core business is growing faster than ever. In the third quarter of 2026, revenue rose 382% to CAD 41.9 million, and adjusted EBITDA turned from −2.3 to 14.6 million CAD, and in September, tungsten concentrate was produced again at the Sangdong mine in South Korea for the first time since 1993. The catch: Revenue fell short of analysts’ expectations, shipments from Sangdong are arriving later than anticipated, and CAD 47.9 million of the CAD 50.2 million net profit consists of non-cash valuation gains. Stifel therefore lowered its price target from $21 to $18 but maintains its “Buy” rating. On average, analysts see the stock at around $23. From a technical analysis perspective, the correction remains intact: A new low below last week’s low of 7.41 USD is likely to drive the stock down to the next support level at 5.60 USD; the first positive signal would only emerge above 11.10 USD.
Key Points
- Price: $8.22 (Nasdaq close Nov. 13, 2026), 52-week high: $24.41, gap of approximately 66%
- Q3 2026: Revenue CAD 41.9 million (+382%), mining profit CAD 26.0 million, adjusted EBITDA CAD 14.6 million
- Net income: CAD 50.2 million, of which CAD 47.9 million were non-cash valuation gains
- Cash: CAD 1.15 billion; repurchased more than 3.6 million treasury shares
- Sangdong: first concentrate in September, first container shipped from Busan, Phase II planned for 2027
- Stifel: Price target $18 (previously $21), Alliance Global: $26.25, average price target around $23
- Chart levels (weekly chart, USD): below 7.41 USD, target 5.60 USD; first positive signal above 11.10 USD, then a move toward just under 20 USD
What are the current key metrics for Almonty Industries stock?
Almonty Industries stock is trading at $8.22 (+7.7% on November 13, 2026) and is thus about 66% below its 52-week high of $24.41, even though revenue rose 382% to CAD 41.9 million in the third quarter.
The price on the Nasdaq in U.S. dollars is the benchmark, as that is where the majority of trading takes place. In Frankfurt (ALI1), the stock is trading at the equivalent of approximately 7.20 to 7.30 EUR. Almonty does not pay a dividend; instead, the company repurchases its own shares.
- Price (Nasdaq: ALM): $8.22 (+7.7%) (Close Nov. 13, 2026)
- Price in Frankfurt (ALI1): approximately 7.20–7.30 EUR (Nov. 16, 2026)
- 52-week high: $24.41 (week ending April 17, 2026)
- 52-week low: $5.44 (week ending Nov. 21, 2025)
- Distance from the 52-week high: approximately −66% (November 13, 2026)
- Previous week’s low: $7.41 (week ending November 13, 2026)
- Revenue Q3 2026: CAD 41.9 million (+382%, prior year: CAD 8.7 million) (November 12, 2026)
- Q3 2026 mining profit: CAD 26.0 million (62% of revenue) (Nov. 12, 2026)
- Adjusted EBITDA for Q3 2026: CAD 14.6 million (previous year: CAD −2.3 million) (November 12, 2026)
- Net income for Q3 2026: CAD 50.2 million, of which CAD 47.9 million were non-cash valuation gains (November 12, 2026)
- Earnings per share Q3 2026: CAD 0.17 (diluted) (November 12, 2026)
- Revenue / Adjusted EBITDA for the first 9 months of 2026: CAD 110.3 million / CAD 38.3 million (November 12, 2026)
- Cash: CAD 1.15 billion (September 30, 2026)
- APT tungsten price (average in Europe): 2,800 USD per MTU (previous year: 615 USD) (Q3 2026)
- Share buyback: over 3.6 million shares, program up to $300 million (Nov. 12, 2026)
- Average analyst price target: 23.08 USD (12 analysts, range 7.98–32.93 USD) (November 16, 2026)
- Fair value (Aktienfinder, book profit): $20.15 at the end of 2026 (only 2 analyst estimates) (November 16, 2026)
- Dividend: none (—)
- Next Earnings Report (Q4 / Full Year 2026): expected late March / early April 2027 (estimate)
- WKN / ISIN / Ticker: A414Q8 / CA0203987072 / ALM (Nasdaq), ALI1 (Frankfurt) (—)
What news is currently driving Almonty Industries stock?
Almonty Industries stock is currently being driven primarily by the Q3 results released on November 12, 2026, which showed a 382% increase in revenue, the first shipment from the Sangdong mine, and Stifel’s reduction of its price target to $18.
Although the stock jumped 7.7% to $8.22 on November 13, it has lost about 40% since early October. The main headwinds are delays in shipments from Sangdong and rising costs. The tungsten story, on the other hand, is getting a boost from the defense sector: Starting January 1, 2027, new U.S. procurement rules regarding the origin of tungsten will take effect, making Western sources outside of China more important. My analysis of the Rheinmetall Aktie.
- November 13, 2026 – Stifel lowers price target, Alliance Global remains optimistic: Stifel lowers the price target from $21 to $18 (Buy rating maintained) due to higher costs and revenue below its own estimate. Alliance Global reaffirms its “Buy” rating at $26.25 and expects a larger contribution from Sangdong starting in the first quarter of 2027. The stock rises 7.7% to $8.22. (Mixed)
- November 12, 2026 – Q3: Revenue +382%, but below expectations: Revenue of CAD 41.9 million, adjusted EBITDA of CAD 14.6 million, net income of CAD 50.2 million (of which CAD 47.9 million were non-cash gains). Cash on hand: CAD 1.15 billion; administrative expenses rise to CAD 11.6 million. (Mixed)
- November 12, 2026 – First container shipped from Sangdong: Following the first concentrate production in September, the first container was loaded at the Port of Busan after the end of the quarter for an overseas customer. Over 90% of Phase I production has been contractually sold. (Bullish)
- October 20, 2026 – Stifel lowers its target price for the first time: Following the Investor Day, Stifel lowers the price target from $25 to $21 because shipments from Sangdong are being delayed. The “Buy” recommendation remains in place. (Bearish)
- October 2026 – Sell-off below $10: The stock falls from $13.40 (weekly close on Oct. 2) to $8.12 (weekly close on Nov. 6), losing about 40%. (Bearish)
- September 2026 – First tungsten concentrate since 1993, Phase II confirmed: Sangdong produces concentrate for the first time; equipment for Phase II, with a capacity of up to 1.2 million metric tons of ore per year, has been ordered, with completion scheduled for 2027. (Bullish)
- 2026 – New off-take agreements: Take-or-pay contract for at least approximately 1,720 metric tons of tungsten oxide from the Los Santos tailings (Spain); new subsidiary in Rwanda with purchase agreements for more than 100 metric tons of ore per month. (Bullish)
What does Almonty’s management say about the Q3 figures?
CEO Lewis Black calls the third quarter the moment when Sangdong became a commercial operation—now the focus is on ramping up the plant safely and steadily.
For Phase II, the same partner is supplying the equipment as for Phase I.
What went well: Revenue nearly quintupled, and mining profit rose to CAD 26.0 million, representing 62% of revenue. With CAD 1.15 billion in cash, Almonty is fully funded; during the quarter, the company repurchased approximately 2.9 million of its own shares at an average price of USD 16.58.
The catch: Revenue fell short of expectations because Sangdong did not begin production until September. Administrative expenses rose to CAD 11.6 million (previous quarter: CAD 8.9 million), and net income consists almost entirely of non-cash valuation gains. Almonty does not provide a specific financial forecast.
Outlook: Phase II of the Sangdong project is scheduled for completion in 2027. Starting January 1, 2027, new U.S. rules regarding the origin of tungsten in defense procurement will take effect, and at the same time, Almonty will transition to U.S. accounting standards (U.S. GAAP).
What does Almonty Industries do, and how does the company make money?
Almonty Industries generates revenue by selling tungsten concentrate to the cemented carbide, steel, and defense industries and aims to become the largest tungsten producer outside of China with its Sangdong mine in South Korea.
The company, headquartered in Dillon, Montana, is led by Lewis Black and is listed on the Nasdaq (ALM) and in Frankfurt (ALI1). Tungsten is used in tools, electronics, and semiconductors, as well as in armor and ammunition—and the global market is dominated by China.
Panasqueira (Portugal): The established mine is the company’s reliable mainstay. According to CEO Black, it continued to deliver strong margins in the third quarter.
Sangdong (South Korea): The centerpiece of the story and one of the largest and highest-grade tungsten deposits in the world. Concentrate was produced for the first time in September 2026; Phase I is designed for approximately 640,000 metric tons of ore per year, while Phase II is expected to produce up to 1.2 million metric tons starting in 2027. Over 90% of the Phase I output has been sold on a long-term basis to Global Tungsten & Powders (Plansee Group).
Los Santos (Spain): Tungsten recovery from old tailings, secured by a take-or-pay agreement for at least approximately 1,720 metric tons of tungsten oxide.
Rwanda and Projects: In Rwanda, Almonty has established a subsidiary in which the government holds a 25% stake. In addition, there are development projects in Spain and Montana, as well as a molybdenum project near Sangdong.
How Almonty Makes Money: Revenue is directly tied to the price of tungsten. The European APT price averaged $2,800 per MTU in the third quarter, up from $615 a year earlier. Those who benefit the most from this are defense and electronics companies that rely on Western supply chains—an example of this is my analysis of Hensoldt Aktie.
Almonty Industries Stock Fundamental Analysis: What Is the Growth Really Worth?
Fundamentally, Almonty is growing rapidly and is operationally profitable, but its valuation depends almost entirely on the ramp-up at Sangdong and the price of tungsten.
In the third quarter of 2026, revenue rose 382% to 41.9 million CAD, and to 110.3 million CAD in the first nine months.
Earnings Quality: Earnings from mining amounted to CAD 26.0 million, and adjusted EBITDA was CAD 14.6 million—compared to CAD −2.3 million in the prior year. Net income of CAD 50.2 million, however, is not a good measure: CAD 47.9 million of that amount stems from the revaluation of derivatives and warrants with no cash impact.
Tungsten Price: The European APT price averaged 2,800 USD per MTU in the third quarter, compared to 615 USD a year earlier and 3,075 USD in the second quarter. It is precisely this decline from the previous quarter that poses a risk to the stock: a large portion of revenue growth comes from price, not volume.
Balance Sheet: With CAD 1.15 billion in cash, Almonty is very well-capitalized. The funds come primarily from the USD 800 million convertible bond maturing in June 2026, which incurs interest and may result in new shares upon conversion. The KfW loan was repaid in full in July, and the share buyback program of up to $300 million is ongoing.
Fair Value: Based on reported earnings, the Stock Finder calculates a fair value of 20.15 USD for the end of 2026 and 58.69 USD for the end of 2027. However, both figures are based on only two analyst estimates—so their reliability is correspondingly limited. Stifel values the stock at 11.5 times the expected EBITDA for 2027.
Valuation Comparison: My analysis of Bloom Energy Aktie —there, the scandium issue became a price risk, while Almonty is selling precisely the opposite narrative.
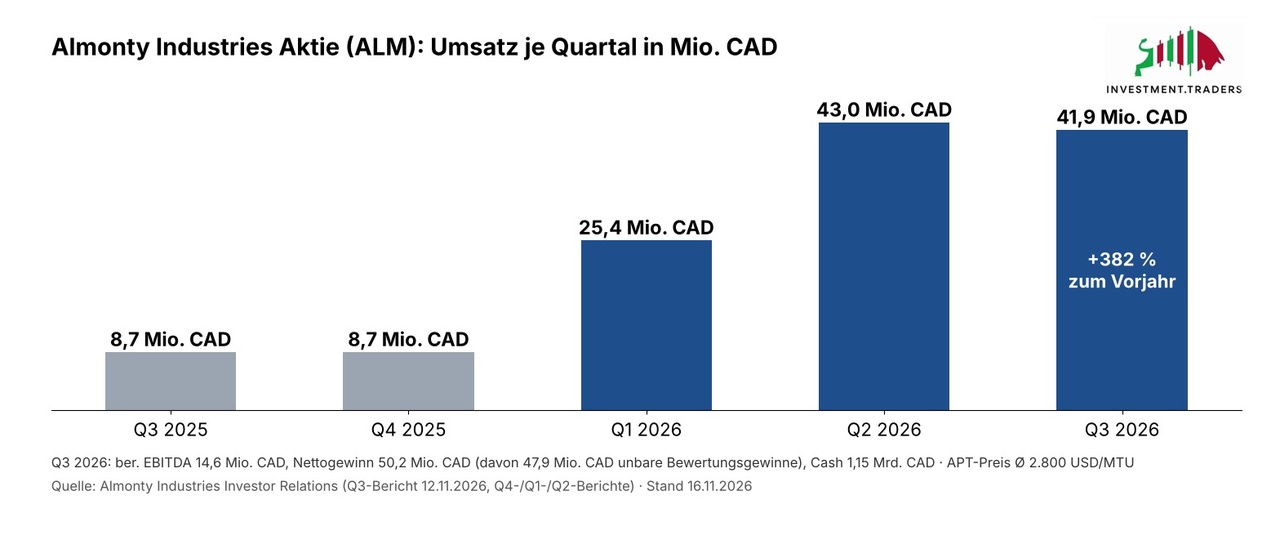
Almonty Industries Stock (ALM) Quarterly Revenue Q3 2025 through Q3 2026 (as of Nov. 16, 2026) – Source: Almonty Industries Investor Relations / Christian Lill
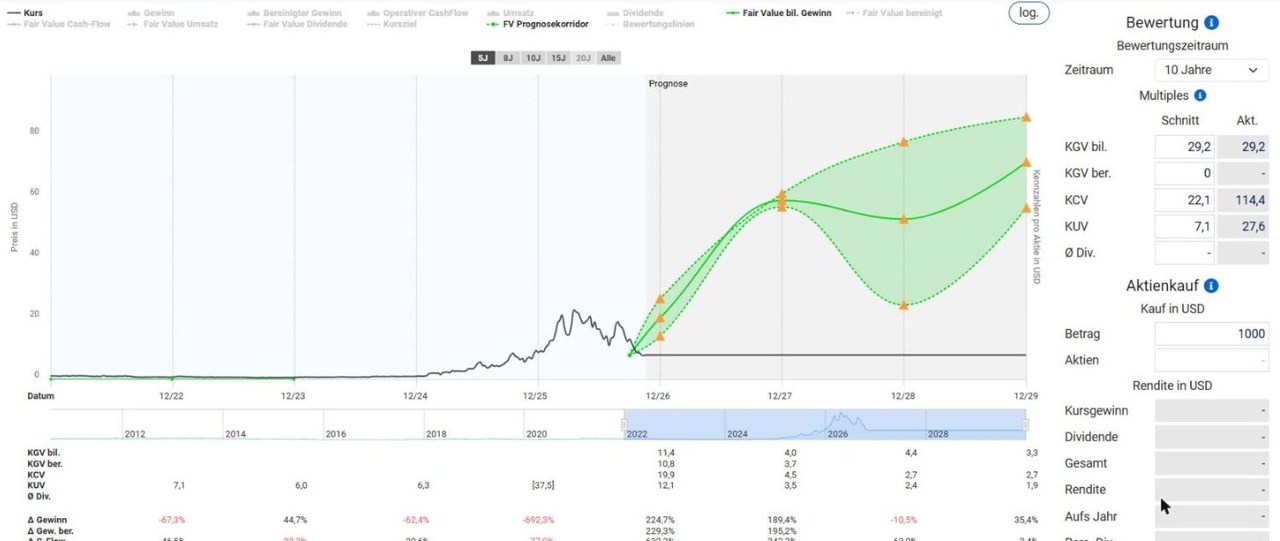
Fair Value Valuation of Almonty Industries Stock (ALM) for 2027 (as of November 16, 2026) – Source: Aktienfinder / Christian Lill
Almonty Industries Stock Price Targets and Forecast for 2027
On average, analysts see a price target of around $23 for Almonty Industries stock—nearly three times the current price—but from a technical analysis perspective, the correction remains intact: a drop below $7.41 could trigger a decline to $5.60.
Most firms are maintaining their “Buy” ratings but are lowering their price targets because shipments from Sangdong are being delayed. You know from the D-Wave Quantum Aktie: There, too, the stock fell by more than 60% at times despite unanimous “buy” recommendations.
Key price levels:
- 52-week high: $24.41 (April 2026)
- Current price: $8.22 (Nasdaq close on Nov. 13, 2026)
- Resistance and signal level: $11.10 (breakout = first positive signal)
- Next resistance: just under $20 (US$19.77 and upper trend channel line)
- Previous week’s low: $7.41
- Critical downside level: $5.60 (next support level if a new low is reached)
Analyst price targets:
- Average price target: $23.08 (12 analysts, range $7.98 to $32.93, as of Nov. 16, 2026)
- Alliance Global: Buy, $26.25 (November 13, 2026)
- Stifel: Buy, $18, previously $21 (November 13, 2026)
- Stifel: Buy, $21, previously $25 (October 20, 2026)
Chart Analysis:
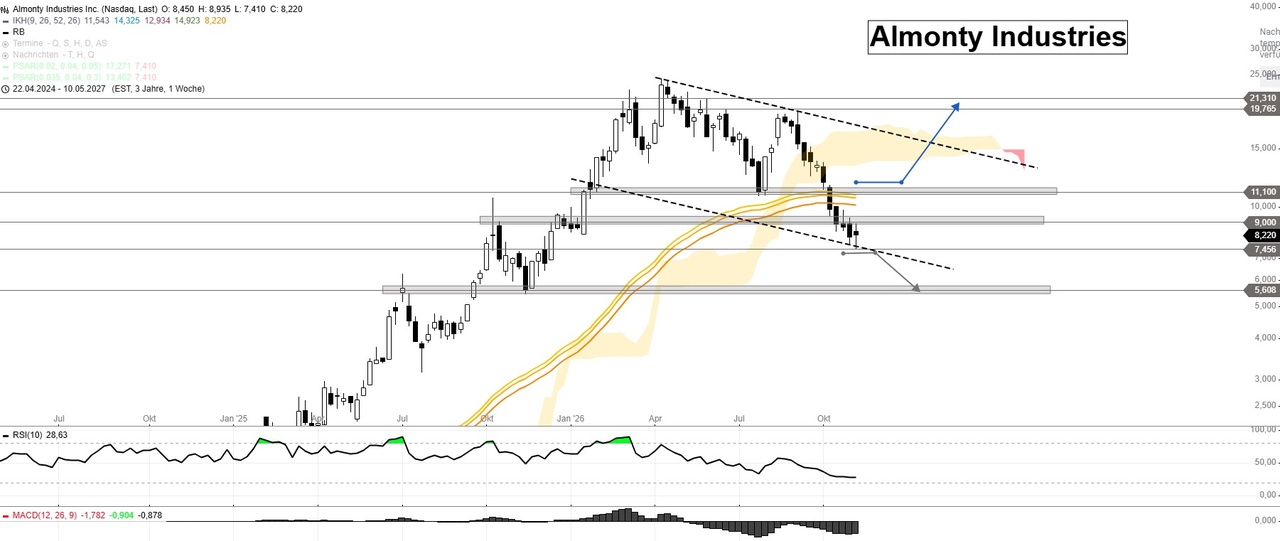
Almonty Industries Stock (ALM) Chart Analysis and Price Targets for 2027 (as of November 16, 2026) – Source: Stock3 / Christian Lill
Almonty Industries stock is under heavy pressure on the weekly chart. I am deliberately viewing the chart in U.S. dollars because the majority of trading takes place on the Nasdaq. Since hitting a high of $24.41 in April, the stock has been moving within a downward trend channel; in early October, it broke decisively through the support zone around $11.10, and the zone around $9 also failed to hold. The correction thus remains intact.
The key level now is last week’s low of $7.41. A new low below that would likely drive the stock down to the next support level at $5.60—which is exactly where the rally from the summer of 2025 began. The correction would thus extend accordingly, representing a further decline of about 32% from the current price. For me, this is the more likely scenario as long as buyers do not return.
A first positive signal would only emerge with a breakout above $11.10. Then the previous support level would be recaptured, and the stock could make a run toward just under $20, where the upper trend channel line and the resistance level at $19.77 are located. However, it’s a long way to go—about 35%—just to reach that trigger point.
Personally, I do not currently favor taking a position in Almonty Industries stock. Only when the stock either tests $5.60 and shows buying interest there or breaks above $11.10 will a new starting point emerge for me.
Conclusion: Almonty Industries Stock – Tungsten Bet Under Fire
Almonty is delivering on its operational promises—Sangdong is producing, and revenue is growing by 382%—but on the stock market, the only thing that matters right now is that everything is coming a bit later and at a higher cost than expected.
The balance sheet is strong at CAD 1.15 billion, over 90% of the Phase I volume has been sold, and starting in 2027, the new U.S. regulations on tungsten from Western sources will help. On the other hand, there’s a falling tungsten price compared to the previous quarter, rising costs, and a net profit that consists almost entirely of valuation effects.
From a technical analysis perspective, the correction remains intact: below last week’s low of $7.41, the stock is likely to fall to $5.60; only above $11.10 will a first positive signal emerge, with potential toward just under $20. Personally, I do not favor taking a position at this time. My analysis of RENK Aktie.
✅ Opportunities
- Q3 revenue up 382% to CAD 41.9 million, adjusted EBITDA positive
- Sangdong has been in production since September; first container shipped
- Over 90% of Phase I volume sold on a long-term basis
- Cash on hand: CAD 1.15 billion; share buyback of over 3.6 million shares
- New U.S. rules on tungsten origin effective January 1, 2027
- Average price target around 23 USD; a breakout above 11.10 USD opens the door to nearly 20 USD
⚠️ Risks
- Revenue below expectations; shipments from Sangdong delayed
- APT price fell from $3,075 to $2,800 per MTU compared to the previous quarter
- Net income at CAD 47.9 million (down from CAD 50.2 million, excluding non-cash valuation gains)
- Administrative expenses rise to CAD 11.6 million; Stifel lowers target to $18
- Convertible bond of over $800 million could be dilutive
- Correction intact; a drop below $7.41 could trigger a decline to $5.60
Sources
- Almonty Industries: Third Quarter 2026 Financial Results (Form 6-K, Nov. 12, 2026)
- Almonty Industries: Second Quarter 2026 Financial Results (Form 6-K)
- Almonty Industries Investor Relations
- Investing.com: Stifel lowers price target to $18 (November 13, 2026) · Finanztrends: Stifel cuts price target (November 13, 2026) and Stifel expects delayed deliveries (October 20, 2026)
- Capital Market Experts / Ad Hoc News: Alliance Global Confirms “Buy” Rating, $26.25 (November 13, 2026)
- TradingView: Analyst Consensus for Almonty Industries (as of Nov. 16, 2026)
- Nasdaq Quotes: Alpha Vantage (weekly and daily data through November 13, 2026), Stock3
- Stock3: Weekly chart for Almonty Industries (Nasdaq, USD), as of November 16, 2026
- Aktienfinder: Fair value calculation and Frankfurt price, as of November 16, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What are your current thoughts on $AII (-3,5%)?
