2Mes·

Hospitality Software Provider Announces 16th Consecutive Record in Revenue – AI Expands Competitive Advantage! Midnight Screening

Hello, everyone,

Now that Jensen Huang has helped stem the decline in software stocks a bit,

it might be worth taking another close look at this sector.


US-Softwarewerte erholen sich: Jensen Huang entkräftet Angst vor KI-bedingter Disruption

June 3, 2026


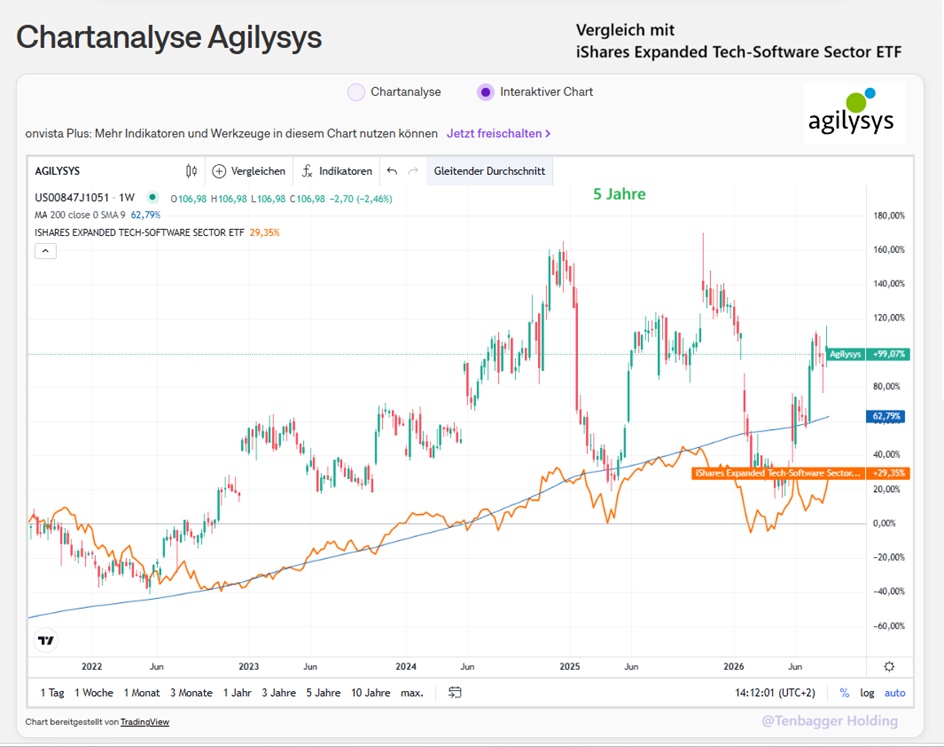
For a change, I’ll start today’s presentation with the chart. Here, I’ve included the

iShares Expanded Tech-Software Sector ETF

$IGV (+2,47%)

as a benchmark.

Here you can clearly see that, starting in late 2024, the software sector enters a bull market—and our stock is behaving exactly the same way.


My friends, please share your thoughts and those of our prompts in the comments.

(@Raketentoni , @Aktienhauptmeister )
attachment


$AGYS (+2,05%)

Agilysys Countered AI Concerns with Its 17th Consecutive Record Quarter

Agilysys (ISIN: US00847J1051) develops software for the hotel and leisure industries. The software offers solutions for reservations, point-of-sale systems, guest management, and digital ordering. The company generates recurring revenue through software subscriptions and service contracts. The company has been in existence since 1963. It went public on the NASDAQ in 1972.

On May 18, 2026, the company reported its Q4 2026 results. It posted its 17th consecutive quarter of record revenue and benefited particularly from growth in subscription-based software for hotels and casinos. Quarterly revenue rose 12% to $82.9 million. Earnings per share increased by 207% to $0.43.


In addition to the strong results, the company particularly impressed with its optimistic outlook for 2027. Management forecast significantly higher subscription revenue and sustained strong growth, even though many investors had feared that AI might put pressure on traditional hotel software. Of particular importance here is the long-term partnership with Marriott for cloud-based hotel software, as it promises recurring revenue for years to come.


Conclusion: Agilysys is a specialized software provider that has evolved into a long-term infrastructure partner for the hotel industry. Its business model is based on high customer retention, recurring revenue, and rising margins. The optimistic outlook gives investors hope that the business can continue to hold its own despite AI alternatives.

(Source: Traderfox)


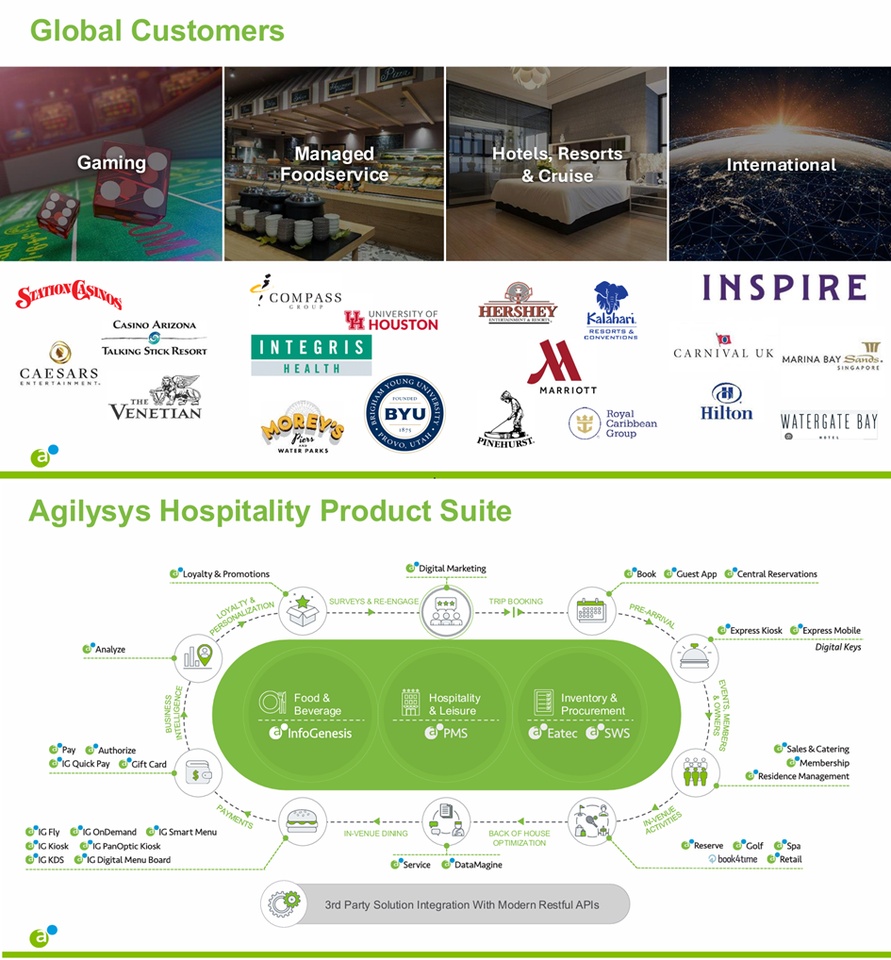
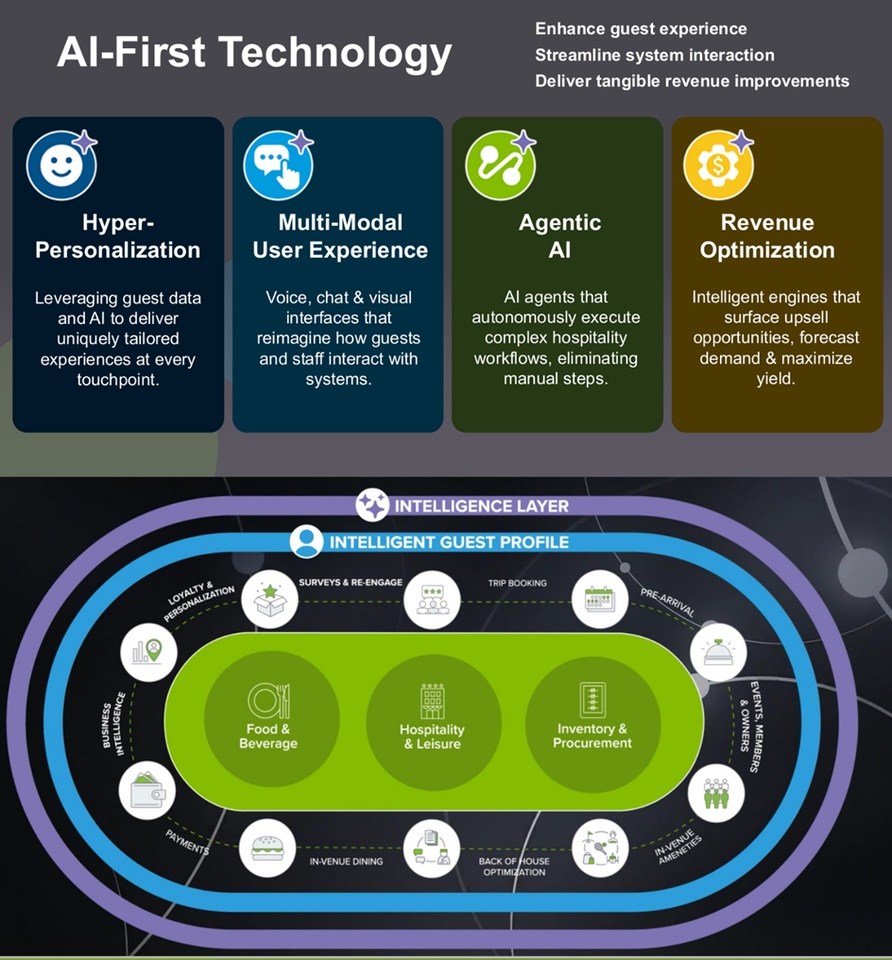
Agilysys (AGYS) could be the next software stock to stage a stronger recovery. The company provides software solutions for the hospitality sector, and CEO Ramesh Srinivasan is determined to position the company as an “AI disruptor.” High demand for AI is expected to shorten sales cycles. At the “INSPIRE Technology User Conference” in late April, over 30 new AI-powered features and software modules were unveiled. Plans also include AI agents integrated directly into the PMS to handle routine front desk tasks.


Agilysys (AGYS) provides leading software solutions for the hospitality industry and is benefiting from the fact that implementation times can be accelerated thanks to product modernization efforts carried out in recent years. Various processes—such as reservations, check-in procedures, room assignments, and guest communication—can be optimized in hotels, resorts, cruise ships, casinos, and restaurants.
attachment
attachment


INVESTOR PRESENTATION

Q4FY26-IR-Deck-V4-6.2.26.pdf

attachment
attachment


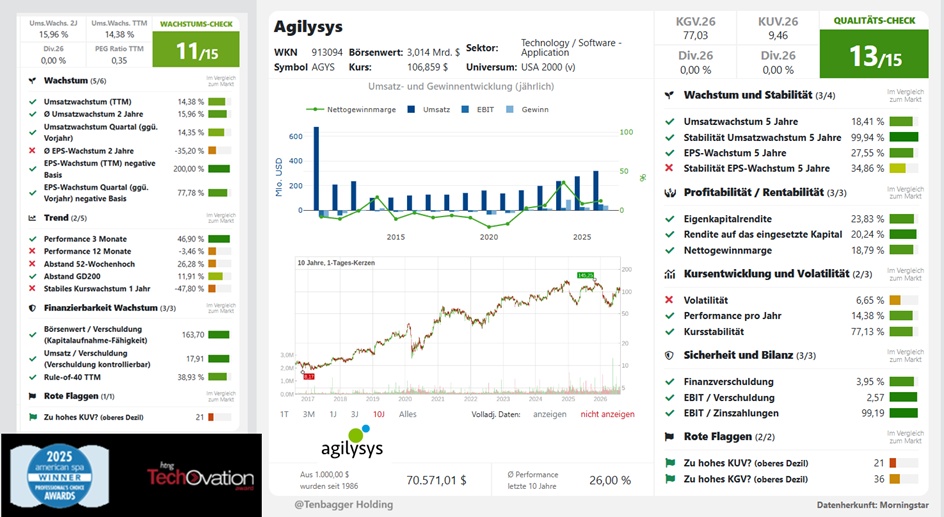
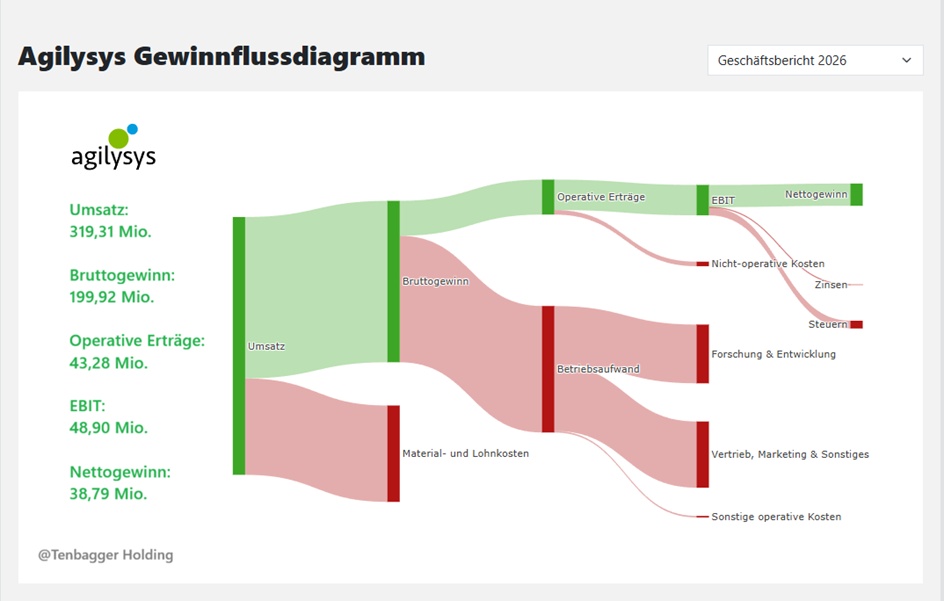
In the last fiscal year, Agilysys Inc.’s revenue rose by 15.9%, from $275.6 million to $319.3 million. Net income increased by 67.0%, from $23.2 million to $38.8 million. The net profit margin was thus 12.1%, compared to 8.4% in the previous year. On July 27, 2026, Agilysys Inc. reported its Q3 results for the quarter ending June 30, 2026. Revenue for the reporting period was $87.7 million (+14.3% compared to the same quarter last year), and net income was $9.0 million (+83.9% compared to the same quarter last year).
attachment
attachment


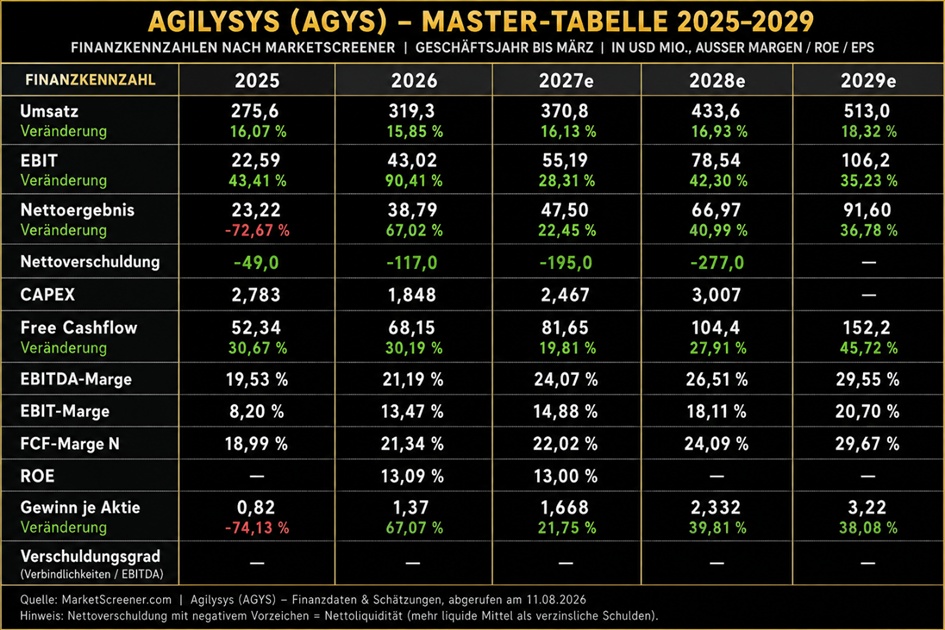
Particularly noteworthy:

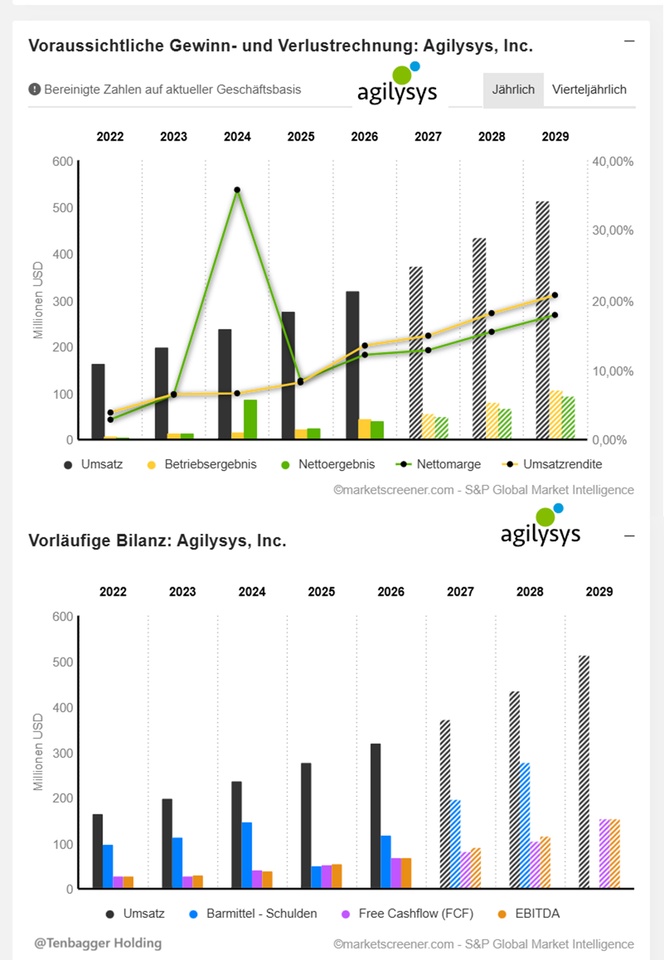
According to the consensus, revenue is expected to grow from $275.6 million (2025) to $513.0 million (2029), while the EBIT margin is expected to rise from 8.20% to 20.70% .

Free cash flow is expected to increase from $52.34 million to $152.2 million .
attachment
attachment


Brief summary:

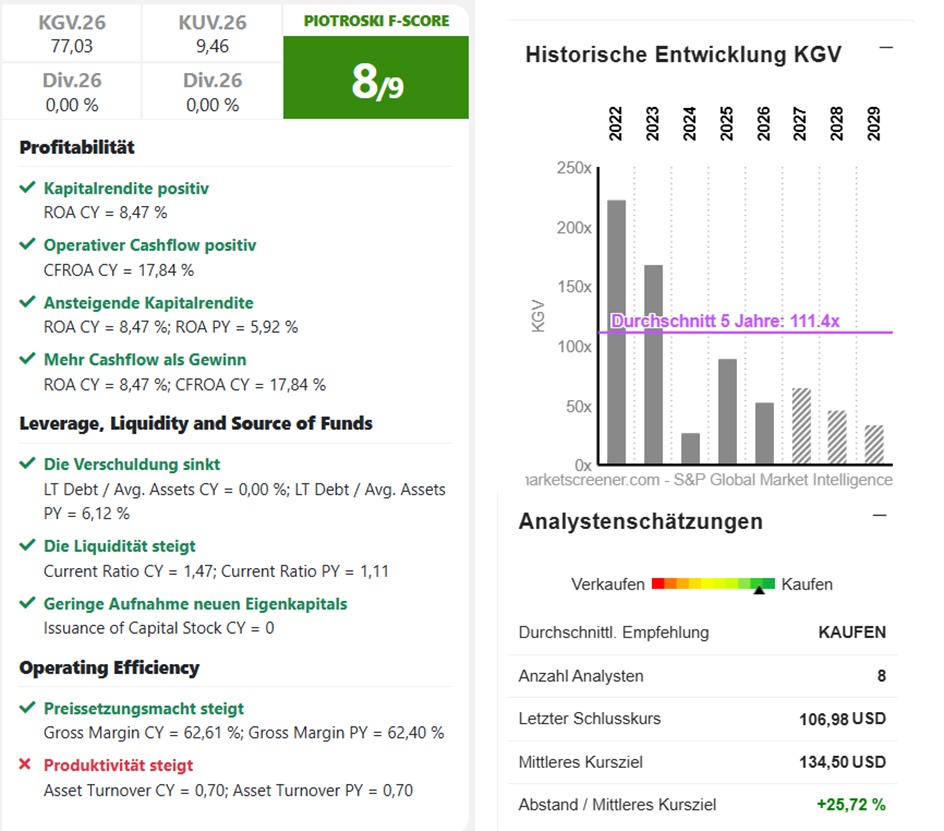
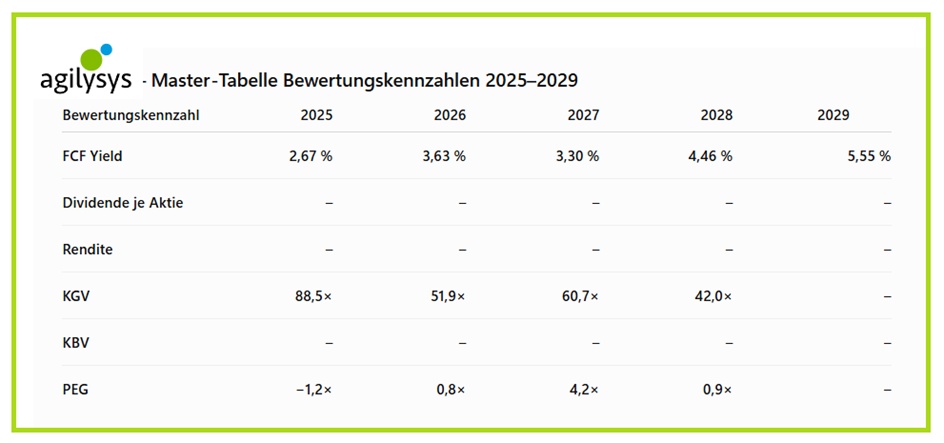
Based on the estimates presented, the valuation will become significantly more attractive by 2029:

The P/E ratio will fall from 88.5× to 33.2×, while the FCF yield rises from 2.67% to 5.06%.

The P/B ratio and the dividend metrics are not reported on MarketScreener for these years.


11/08/2026, 9:55:04 PM •

Lang & Schwarz (EUR)

92.00 EUR


$AGYS (+2,05%)

21
4 Commenti

immagine del profilo
At the beginning of your presentation—which, as always, is great—you linked to the wrong acronym. It takes you to a penny stock.😂 It was probably because it was midnight.😉
•
6
•
immagine del profilo
@Tenbagger2024 It's me again ✌️ your Grim Reaper—let's see what we're dissecting today.

The Digital Operating System for the Experience-Driven Hospitality Industry
Agilysys develops cloud-based enterprise software (PMS, POS, Inventory, Spa & Experience Management) exclusively for major hospitality brands, casinos, cruise lines, and resorts. Once deeply integrated into the operations of a luxury resort or casino complex, Agilysys functions like an irreplaceable nervous system with extremely high switching costs.

🛠️ DNA Check
• Gross Margin Strength: The company boasts a gross margin of approximately 62–63%, underscoring its transition to a high-margin software subscription business.

• Cash Flow & Profitability: Adjusted EBITDA reached a record high of 20.8% in the most recent Q1 of FY2027. Free cash flow generation is growing steadily as ARR scales.

• Rock-Solid Balance Sheet: Virtually debt-free with a solid net cash position—no interest rate risk, high financial flexibility for organic product development.

• Quality: 18 consecutive record quarters of revenue demonstrate operational consistency and excellent execution by management.

🚀 Growth Leverage & Catalysts
• SaaS Transformation: Subscription growth is accelerating rapidly (+26% to +32% YoY), with increasing recurring revenue (SaaS) mitigating cyclical risk.

• Major Enterprise Contracts: Contracts with global hotel chains and casino operators secure multi-year, predictable revenue streams.

• Guidance Upgrade: Following strong Q1 FY2027 results, the full-year revenue forecast was raised to $368–373 million.

⚠️ Valuation & Risks
• Ambitious valuation: With a forward P/E ratio of over 70x and an EV/sales multiple near 8–9x, the stock price already factors in an enormous degree of perfection.

• Industry trends: The business is indirectly dependent on IT budgets and the willingness of the travel and entertainment industries to invest.

• Niche Limitations: As a purely vertical hospitality software provider, the total addressable market (TAM) is smaller than that of horizontal software giants.

Conclusion for Agilysys (AGYS):
“Agilysys is a high-quality niche SaaS growth stock with extremely strong customer lock-in. The operational transformation is proceeding by the book, but the valuation (P/E ratio > 70x) leaves absolutely no room for operational missteps.

Reaper Rating: ⏳ WATCHLIST / WAIT FOR DIPs
Reaper Score: 7.1 / 10
•
5
•
immagine del profilo
Hey @Tenbagger2024! 🚀

You’ve gone and typed out another half-novel here! Kudos for the effort—it’s clear you’ve fallen in love with the story of **Agilysys ($AGYS)**. And yeah, a software company that’s digitizing casinos and hotels definitely has its charm.

But before we go popping the champagne corks here, I ran your claims through InvestingPro’s ruthless data scanner.

Here’s the no-holds-barred analysis: What **shines like gold** in your analysis—and where you’ve **skillfully swept facts under the rug**! 😉

---

### 1. Credit where credit is due: You’re absolutely RIGHT here! ✅

Let’s start with the praise, because when it comes to historical fundamentals, you’ve done your homework almost perfectly:

* **Historical growth:** Your numbers for the past fiscal year are spot on! Revenue climbed to $319.3 million and net income to $38.8 million. That’s extremely solid growth.


* **The Marriott partnership:** This is truly a game-changer. The large-scale rollout of the Property Management System (PMS) at Marriott promises massive recurring revenue for years to come.


* **The AI story:** It’s true that Agilysys is investing heavily in AI. Over 30 AI-based features are currently being rolled out, and AI-native modules (such as Revenue Intelligence) will soon enter the beta phase.


* **The valuation is becoming more attractive:** Your thesis that the P/E ratio will drop significantly in the long term is supported by the estimates. The forward P/E ratio is falling from a currently ambitious 44.5x (for FY27) to approximately 34.3x in FY28 and even to around 20.1x in FY29. Anyone thinking long-term here is buying into rapidly growing profitability.

---

### 2. The Reality Check: Where You Were Sloppy—and Daydreaming! ❌

Now let’s take off those rose-colored AI glasses. You got lost in the quarterly jungle on a few details—and you completely glossed over a major bombshell!

#### ❌ 1. Quarterly confusion and the 18th record (not the 17th!)

You’re talking about the Q3 figures as of June 30, 2026. **Wrong!** The quarter that ended in June was already **Q1 of fiscal year 2027** at Agilysys. And it wasn’t the 17th, but already the **18th consecutive revenue record**. However, the figures you cited (USD 87.7 million in revenue and USD 9.0 million in profit) for this quarter are spot on.

#### ❌ 2. The “visionary” CEO is cashing out!

You’re praising CEO Ramesh Srinivasan for positioning the company as an “AI disruptor.” But what you conveniently fail to mention to your community is: **It was this very CEO who dumped shares worth a whopping $21.3 million onto the market in early August 2026**! When the boss cashes out in a big way after such a record quarter, you should at least pause for a moment before dreaming of a major recovery rally.

#### ❌ 3. The valuation isn’t a bargain right now

You’re raving about the future valuation, but let’s take a look at the *present*. The stock is currently trading at a **P/E ratio of 71.2x and an EV/EBITDA of 60.5x**. InvestingPro rates the “Relative Value” as weak in its quality check, giving it only **2 out of 5 points**.

#### ❌ 4. Analyst Warning Signs & Margin Pressure

Despite the record-breaking performance, **six analysts have revised their EPS estimates downward** over the past 90 days. Furthermore, pricing in international markets (Europe/APAC) is currently the main reason why Agilysys is losing deals to the competition. So, achieving growth is still a real struggle.

---

### 3. Chart & Fair Value 📉

You mentioned the “kangaroo market” for software stocks. Looking at the current price of approximately $108.60 (or €92.33), the InvestingPro model tells us the following:

* **Fair Value:** The calculated fair value is **$108.30**. This means the stock is currently **fairly valued down to the cent** (upside of -0.28%). This isn’t exactly what you’d call a bargain.


* **Technical Analysis:** While technical indicators rate the stock as a “Strong Buy” in the short term, the current pricing means the fundamental upside potential is currently exhausted.

---

### Bottom line for you, my friend 🎯

Agilysys is a fantastic company with a rock-solid moat and impressive execution. Your fundamental research on growth is top-notch!

But: The stock is currently priced at perfection. When the CEO is selling shares worth tens of millions and the fair value has already been reached, this might be a great holding position for existing shareholders, but it’s certainly not a blind “all-in” buy for a quick rebound.

Let’s keep an eye on the next few quarters to see if the AI narrative really causes margins to skyrocket the way analysts are dreaming they will by 2029!

Best regards,

Your Raketentoni
•
2
•
immagine del profilo
@Raketentoni Thanks for another very detailed analysis—I'll need your help again in a minute. But don't be quite so hard on me 🙈😂
•
1
•
Partecipa alla conversazione