4Mes·

Company presentation: Tristel

Hello dear community,

Despite the sunshine 🌞 you still have to take care of your health somehow. In keeping with this, I would like to introduce you to a title from the health sector today.


Today it's all about Tristel $TSTL (+0,88%)
attachment


1. the business model: the "razor blade" model of medicine


Tristel $TSTL (+0,88%) has a worldwide monopoly on a patented disinfection chemistry based on chlorine dioxide (ClO_2). They clean medical instruments (such as ultrasound probes or endoscopes) that cannot be heat-sterilized.

Tristel $TSTL (+0,88%) does not operate as a traditional cleaning manufacturer, but as an undisputed niche monopolist for high-level disinfection in hospitals. With its patented chlorine dioxide technology (ClO_2), the company controls clinical workflows in the reprocessing of endoscopes and ultrasound probes. Following the extremely profitable "razor and blades" model, regulatory requirements force hospitals to continuously repurchase the proprietary foams and wipes - before and after every single patient treatment.


The trick: They make their money not on the one-time hardware, but on the consumables (wipes, foams, rinses). Hospitals are hooked on the needle: every single examination generates recurring revenue. Once in the system, nobody changes.


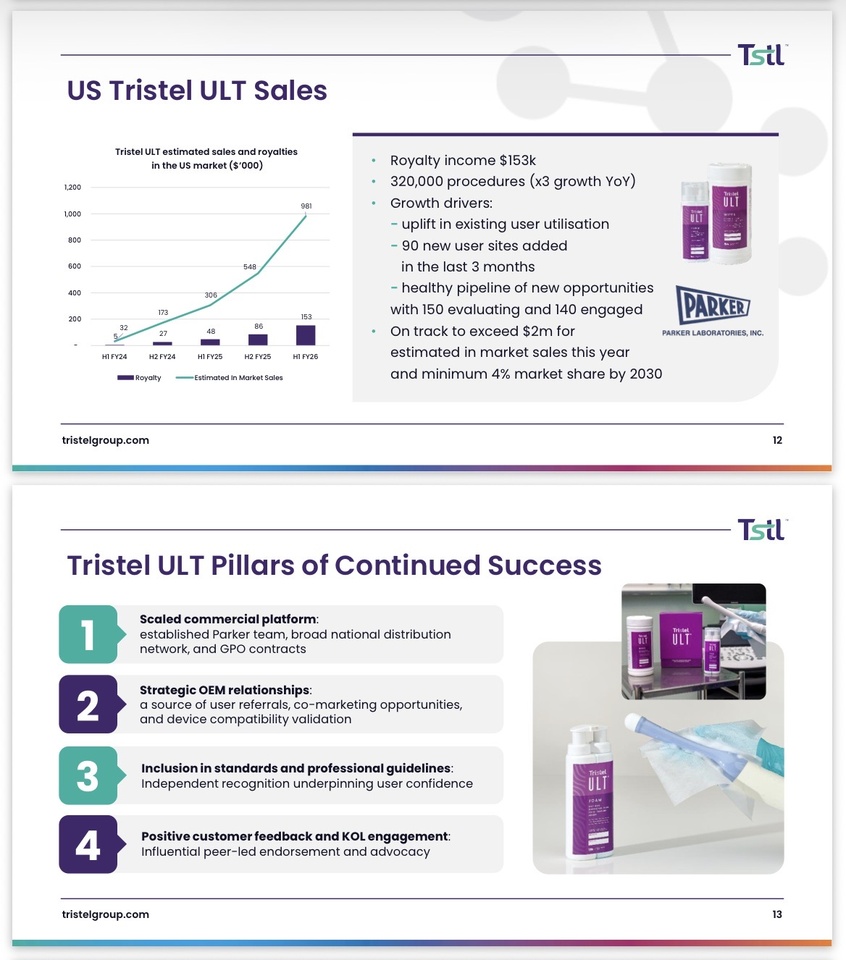
FDA validation: The most recent accolade was the official US approval by the FDA for its core product Tristel ULT. This opens up the largest and most lucrative healthcare market in the world via the US sales giant Parker Laboratories.
attachment


2. the numbers: Financial muscleman

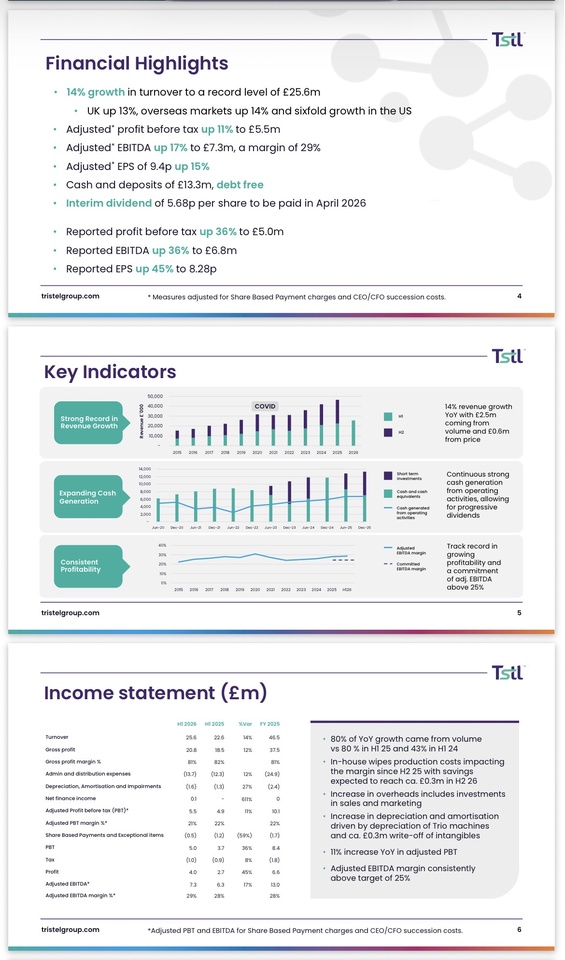
Margins from another world: With a gross margin of over 80% and a massive pre-tax profit expansion (+41% in the last six months), Tristel operates at the level of elite software companies - only with physical chemistry.


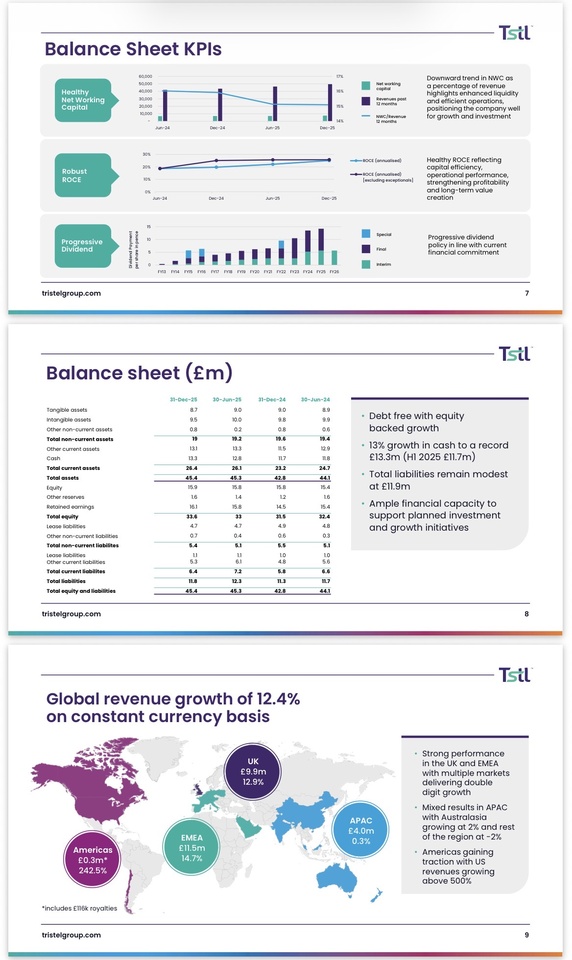
Cash flow & return on investment: They are brutally efficient at converting profits into cash (FCF margin of 21,4%) and achieve a physical ROIC of 25,8%. This is the absolute Champions League of capital efficiency.


Balance sheet from Titan: Tristel $TSTL (+0,88%) is completely debt-free and is sitting on a comfortable cash cushion of over GBP 11 million. The entire US growth is financed organically from cash flow - zero dilution risk for you.
attachment
attachment
attachment


3. 🚀 Why the share is exciting now


-Mispricing due to wrong label: The market often values Tristel $TSTL (+0,88%) superficially like a classic, boring chemical or industrial producer and stares in shock at the visually high P/E ratio of ~25x. In reality, it is a medtech SaaS equivalent with a subscription character.

-The US catalyst: The market is underestimating the leverage of FDA approval. The cost of approval is historic, the operating leverage is now in full effect. Every new bottle of chemical that goes over the counter in the USA goes almost one-to-one into net profit.

-Regulatory tailwind: Health authorities around the world are tightening guidelines for the disinfection of medical devices. Hospitals are structurally forced to upgrade from cheap alcohol to Tristel's high-level process.

-Resistant to the economy: Hospitals must disinfect. Regardless of inflation, recession or geopolitical crises - the volume of examinations remains stable.

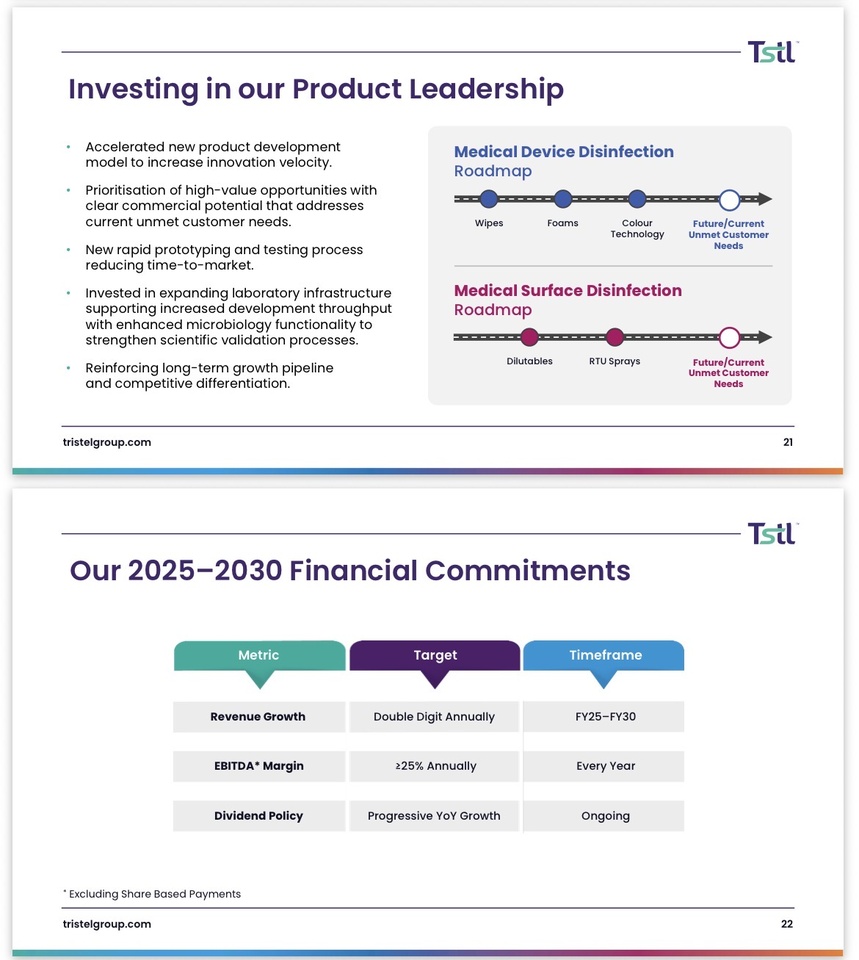
-Financial commitments 2025-2030: Management officially commits: Sustained double-digit sales growth per year and an EBITDA margin of ≥25% in every single year by FY30.

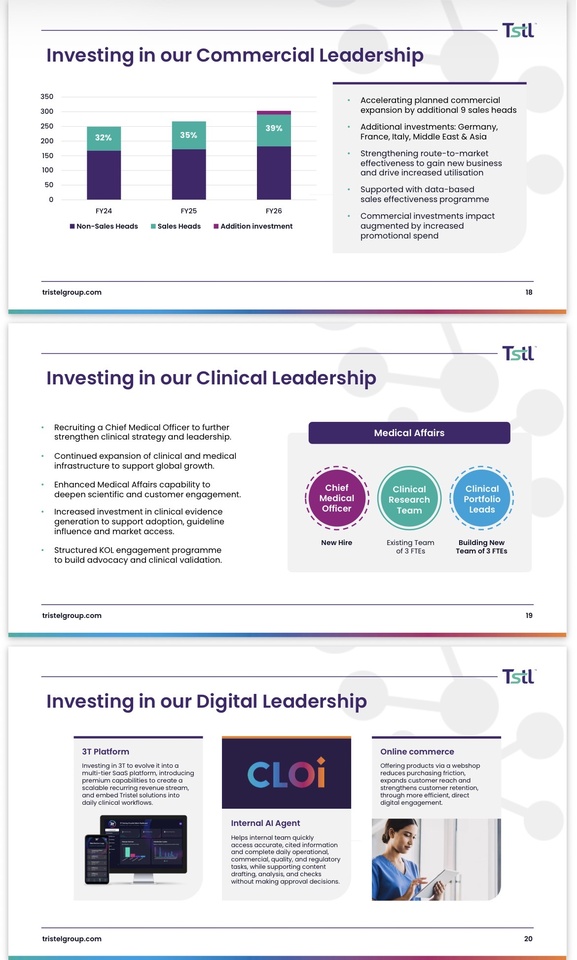
-Digital toll (3T platform & CLOì): Tristel $TSTL (+0,88%) invests massively in digitalization. The wipe system is being expanded into a multi-tier SaaS platform that generates recurring software revenue and drives switching costs for clinics to infinity. An internal AI agent (CLOì) also speeds up internal regulatory processes.
attachment
attachment


4.⚠️ Valuation & risks

-Premium price: Quality has its price. With a forward P/E ratio of over 25x, the company is permanently expensive and does not forgive any operational disappointments in the US rollout.

-Bureaucracy brake: Success stands or falls on the speed of clinical adoption in the US. If American hospitals are slower to change over than expected, the growth story will be delayed.

-Chemical cluster risk: If there is ever any proven chemical damage to the extremely expensive ultrasound machines from the major manufacturers (GE, Philips, etc.), the story will falter. (So far unfounded, as the top manufacturers have officially released Tristel).


5.my personal conclusion + Reaper Bonus 💀


Tristel $TSTL (+0,88%) is not a short-term hopeful bet for me like many overvalued hype stocks, but rather a rare quality stock with real substance. While other companies are still living on visions, Tristel is already delivering high margins, strong cash flows and an extremely robust business model and, in my view, the decisive factor: a profitable niche leader with a quasi-monopoly position, recurring revenues and enormous scaling potential.


BONUS MATERIAL 😂


Jack's conclusion:

Honestly? Tristel is exactly the band-aid you need if you're fed up with unprofitable hype shops that only live off shiny PowerPoint slides. Here you have a highly profitable, debt-free fortress with a gross margin of over 80% that earns its money in real life. Those who stare superficially at the supposedly high P/E ratio simply don't understand how rare real niche monopolies are.

The US expansion is no longer a hopeful bet, the engine is now clearly firing. If you fancy recurring sales, a cash fortress and software margins in a medical guise, then the situation is crystal clear: collect the shares, switch off the price ticker and put your feet up and relax.


Reaper rating: BUY ✅

Reaper Score: 7,5/10


@Get_Rich_or_Die_Tryin
@schlimmschlimm
@Tenbagger2024
@Multibagger
@Raketentoni and of course all other ✌️

24
25 Commenti

immagine del profilo
Bam! You've dug up something again, my dearest! Many thanks for that. As you know, of course, I like that😅🤷🏼‍♂️. That would be a component a little different from classic MedTech. Did you deliver it on purpose just now, after I revealed my current objective?

Okay, so much for that: I'll rethink my current planning after you've presented this value here.🤷🏼‍♂️ Thanks for the introduction.🫶🏻
•
7
•
immagine del profilo
@Dividendenopi Thank you for the introduction. Let's take a look. You really went to a lot of trouble. Thank you very much.
•
4
•
immagine del profilo
@Tenbagger2024 change that quickly, it wasn't me 🙄🤭
•
2
•
immagine del profilo
@Dividendenopi what were you not?
••
immagine del profilo
@Tenbagger2024 the introduction, but thanks for the flowers anyway 🙃
•
1
•
immagine del profilo
@Tenbagger2024 @Dividendenopi and what is your assessment gentlemen ? What do you think of the value? 🤔
•
1
•
immagine del profilo
@Aktienhauptmeister The boss hasn't really said anything yet. It's garden weather
•
2
•
immagine del profilo
@Tenbagger2024 in the garden with a cool glass of wine. Then later on at the computer. I find the stock very interesting. It's already on the watch list. And we have a shaky candidate in this sector at the moment. But I have to clarify that with the advisor first, I'm just the robo 🙃🤭
•
2
•
immagine del profilo
Top! Thanks for the introduction! :-)
•
4
•
immagine del profilo
@schlimmschlimm I'd love to 😬 is the share something for you?
•
2
•
immagine del profilo
Interesting small cap, I took a look at it straight away, as I would like to fish for my next position from the perhaps not so classic healthcare sector.
The figures look really good, there's really nothing to complain about, the quality component could even be something for me and there are even dividends 😅

During/after covid, however, it seems to have become painfully clear that the products are not so critical on a daily basis. Sentiment is still wavering and the promising growth story has been halted for the time being.
The FDA approval and successful US expansion could, of course, give the share a good boost again.
The niche moat looks interesting, they are performing really well and business relationships do not seem to fall apart so easily.

But I think the whole thing is less robust than it is portrayed, the hurdles don't seem really high for another established player to gain a foothold here. If the market seems attractive and margins remain stable, this could activate competitive pressure. But they are very well positioned to deal with this according to the balance sheet.

Solid stock and could certainly be a good long-term compounder if growth remains sustainable or picks up again through expansion 👍
•
3
•
immagine del profilo
@Stocktective For a company with such a low market cap, with such a margin, you don't find that every day. I was very surprised myself when I took a closer look at this stock. It sounds boring at first, because it's just "disinfection", but the fundamental data and key figures speak for themselves.
I'm not invested yet, but will definitely throw in a tranche in the next few days 😬
I'm glad if you find the company exciting 🤝
•
2
•
immagine del profilo
Nice! Very interesting value apart from the tech weight 🙏🏼
•
2
•
immagine del profilo
@Roccola601 would the value be something for your portfolio? 😬
•
2
•
immagine del profilo
@Aktienhauptmeister yes actually that fits really well! ✨🤗
••
immagine del profilo
Thanks for sharing and will be on the watchlist - the elephant in the room is that the CEO is leaving at the end of June and the successor is not yet in place. The current CEO is going to a US multi-corporation and that is exactly what the current growth strategy of this company may now be on the other side. Small companies in particular are dependent on a CEO. https://www.marketscreener.com/news/tristel-plc-announces-resignation-of-matt-sassone-as-chief-executive-officer-ce7e58d3dd89f627
•
2
•
immagine del profilo
@Cookiebug Sassone is moving to a major US multinational in a global presidential role. This is a career move, not a sacking. He is returning to the USA with his family, which is perfectly understandable from a human point of view and not at all uncommon among top managers with US connections. this is not a sign of a structural problem at Tristel 😬
•
1
•
immagine del profilo
Really a nice value. I like the margins. Growth is there. It's a shame that there's so little momentum in the stock so far
•
2
•
immagine del profilo
@Tenbagger2024 I'm glad you like the value 🤝 I hope the rocket ignites soon 👀🚀
•
2
•
immagine del profilo
@Aktienhauptmeister when the alarm clock rings, please let me know
•
2
•
immagine del profilo
@Tenbagger2024 but for sure 👍
•
2
•
immagine del profilo
I usually earn my high returns by constantly switching between various unprofitable hype shops 😂😂
Hence my two questions, which I always ask after such great ideas.
Are you invested yourself? And what prices do you think are realistic for the next 12-24 months? From the point of view of my investment strategy, this is almost a buy&hold scenario. 😉😎Do you think they will reach the old highs from the coronavirus era again in this period?
I know you don't have a crystal ball, but you do have an estimate.
•
1
•
immagine del profilo
@Multibagger I'm not invested yet, but I'll definitely throw in a tranche in the next few days. I definitely think it can reach the old highs from the coronavirus era and even more! The only question is when 😂 At the moment, the market is all about AI and space, so everything is very difficult to assess 👀
•
1
•
immagine del profilo
@Aktienhauptmeister So you mean I should stay invested in the unprofitable hype shops for a while and only switch when this hype is over? 😉😂 Then I'll put them on the watch for now.
•
1
•
immagine del profilo
@Multibagger you can say that 😂😂😂😂
•
1
•
Partecipa alla conversazione