August 25, 2026
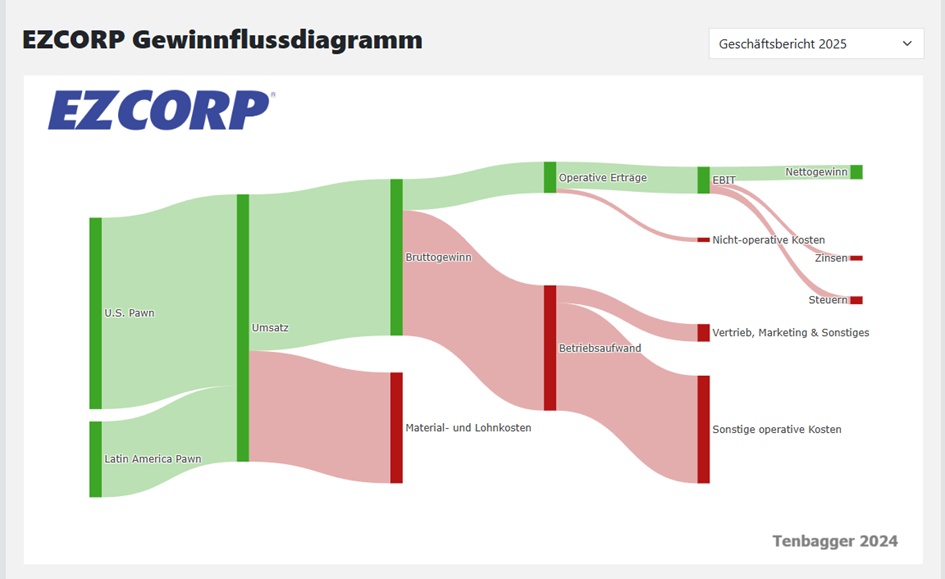
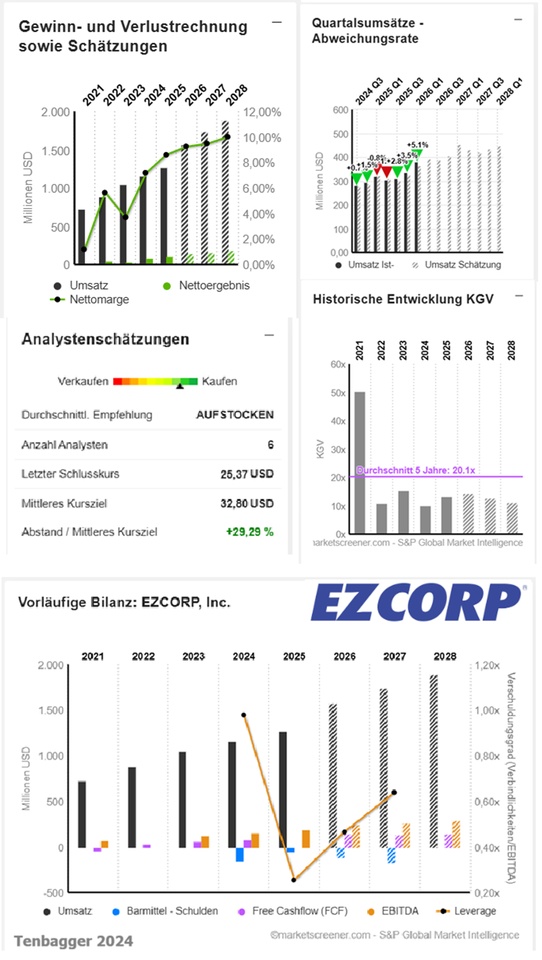
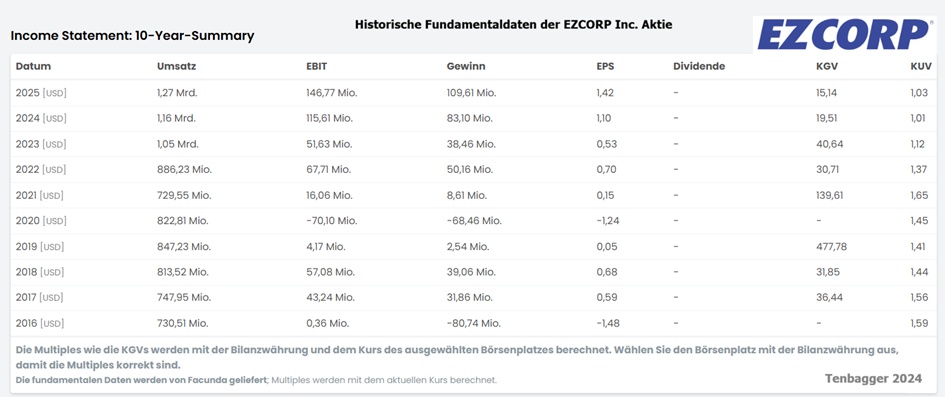
EZCORP (EZPW) significantly exceeded expectations in the third quarter of fiscal year 2026. The U.S. pawnshop group increased its adjusted EBITDA by 48% to $65.6 million, while adjusted diluted earnings per share climbed 47% to $0.47, exceeding analysts’ estimates by $0.06. Consolidated revenue grew by 31% to $408.4 million, while gross profit rose by the same margin to $240.3 million.
The core business was the driving force: Outstanding pawn loans (PLO) reached a record high, up 31%. Pawn fees rose by 29%, and growth in the branch network totaled 13%. The scrap gold contribution normalized as expected: After a gross margin of 38% in the second quarter, it fell to 26%, compared to 29% a year ago. The “scrap gold contribution” is the revenue or profit contribution from these specific scrap sales (i.e., the raw material from melted-down gold), separate from the actual core business (pawn loans and pawn fees) and from the sale of used goods in-store. This contribution is heavily dependent on the price of gold.
In the U.S. pawnbroking business, with 560 branches in 19 states, revenue rose by 14% and segment EBITDA by 23%. In Latin America, where EZCORP now operates 881 branches in four countries, revenue climbed to a record $114.1 million, with segment EBITDA rising by 40%. In April, the company acquired 33 stores in Guatemala, thereby expanding its market leadership.
Another milestone: In July, shortly after the end of the quarter, EZCORP acquired the remaining shares in Simple Money Group and now owns 100% of the chain, which has 108 branches in 12 countries. The balance sheet remains conservative: $311 million in cash, with the first bond maturity not due until December 2029, which provides a buffer against higher financing costs as interest rates rise. Under the $50 million share repurchase program launched in November 2025, EZCORP repurchased $4 million worth of shares during the quarter.
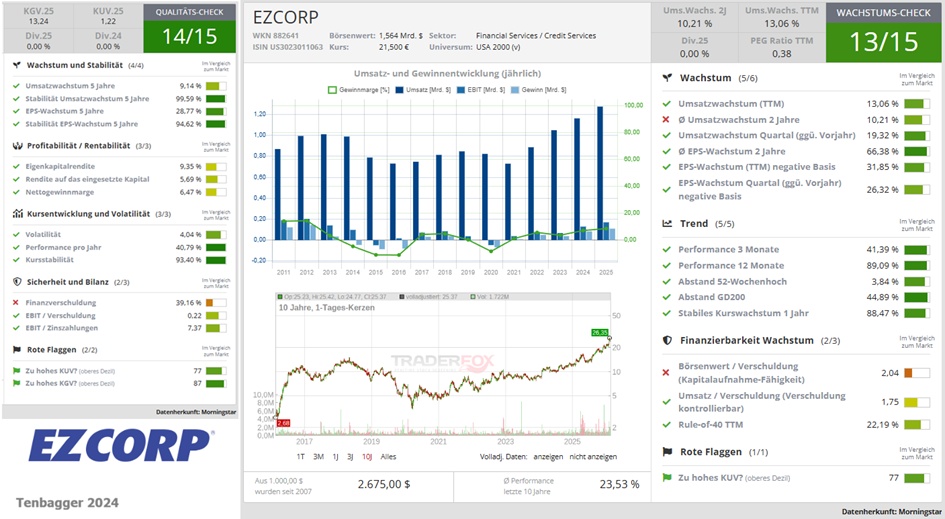
For investors, the stock remains an attractive investment with broad geographic diversification and a growing core business that is insulated from gold price volatility. The P/E ratio of 17 no longer appears cheap, but the stock remains an intriguing opportunity for trend followers.