
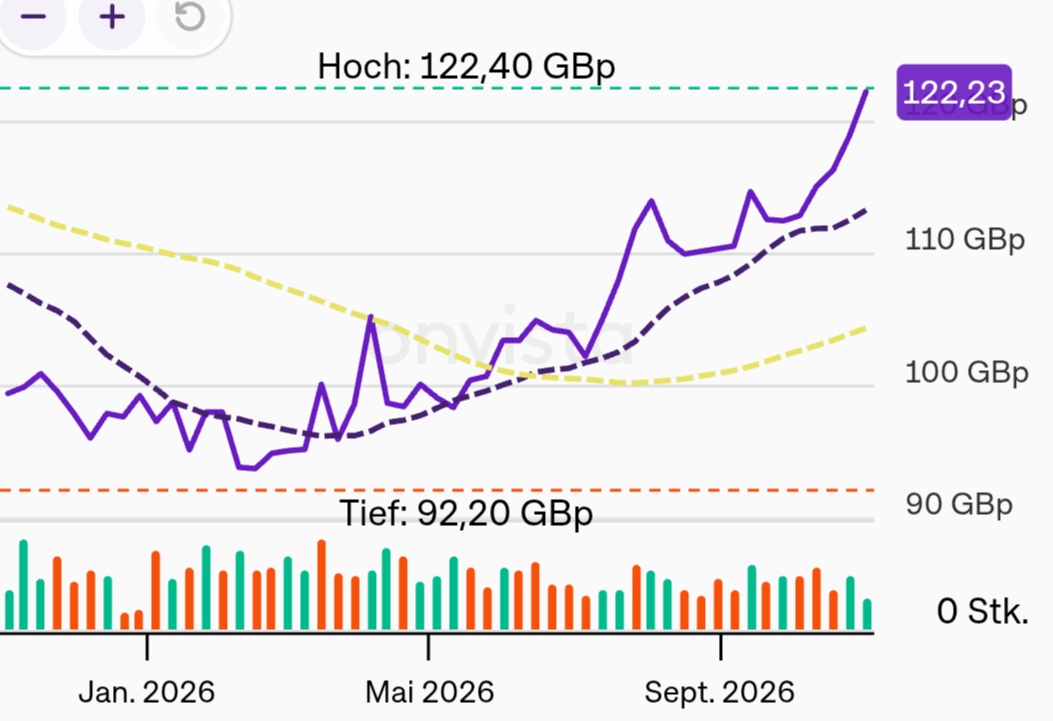
The company’s performance benefited from higher electricity prices, which increased the net asset value by 2.7% at the beginning of the period, as well as from higher short-term inflation forecasts, which contributed 2.2%. Net cash generation contributed 1.6% to the growth, while mark-to-market gains on liabilities accounted for 0.8%.
These gains were offset by a 25-basis-point increase in discount rates, which reduced the net asset value by 2.1%. In addition, write-downs had a negative impact of 1.6%, and an increase in the EGL liability had a negative impact of 0.4%.
In the third quarter, the company generated net cash flow of GBP 45 million, compared to approximately GBP 25 million in the same period of fiscal year 2025.
Electricity generation in the third quarter was 2% below budget. The company announced that for the full year 2026, it is targeting the upper end of the respective forecast ranges of GBP 560 million to GBP 660 million for EBITDA and GBP 350 million to GBP 410 million for net cash generation.
As of September 30, 2026, total consolidated liabilities amounted to GBP 2,047 million, corresponding to a debt-to-gross-asset-value ratio of 41.1%. After the end of the quarter, the company refinanced short-term liabilities totaling 150 million GBP with its existing banking syndicate; these liabilities would have matured in 2027.


