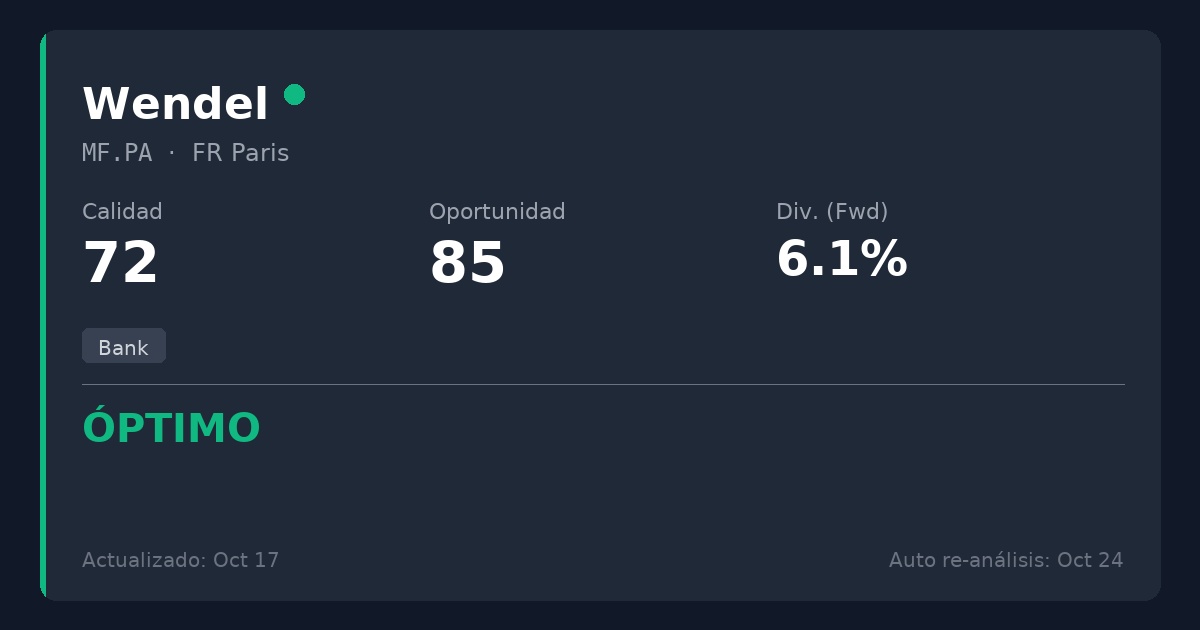
$MF (-0,27%) (wendel) • Optimal 72/85 • Pays 4.5% today and 6.3% forward. Cash payout ratio: 24%. Trades at a 31.9% discount to its NAV and a P/FFO of 3.2x. The market sees accounting losses; I see asset sales (Stahl, IHS) translated into returns for shareholders.
My issue with Wendel: GAAP losses are part of the model, not an anomaly. Portfolio turnover = messy accounting forever. Either you factor it in via FFO or you don’t.
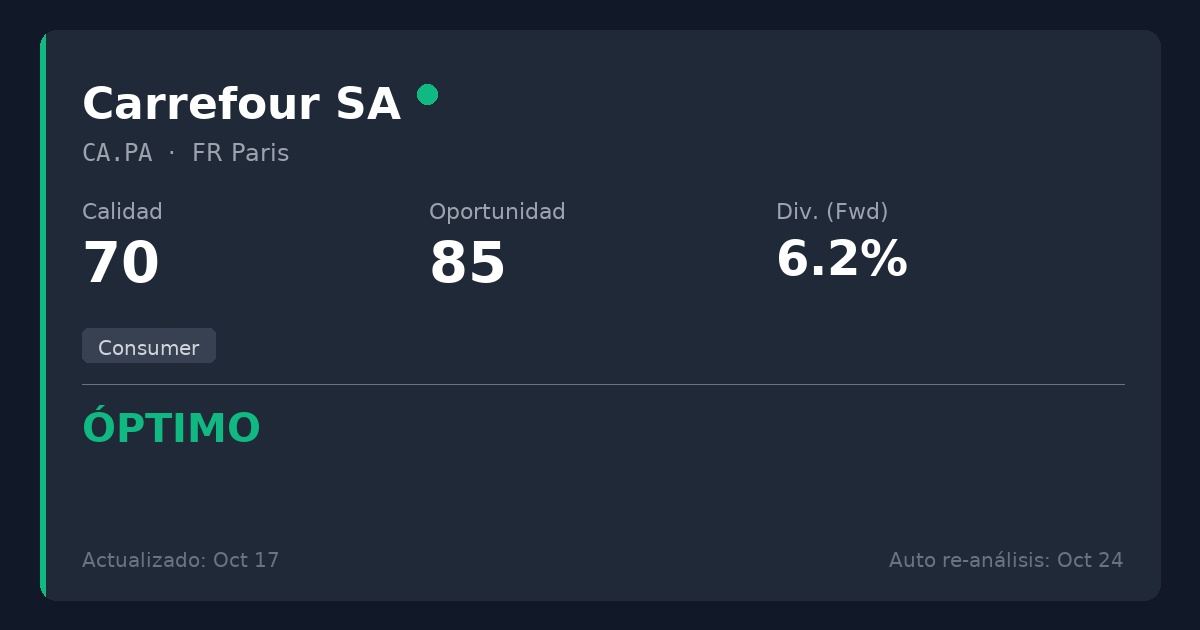
$CA (+0,52%) (Carrefour) • Optimal 70/85 • 6% yield with the dividend covered 2.5 times by free cash flow (payout ratio 23%) and a P/E of 14.9x. The recent loss is due to restructuring and the integration of Cora and Match, not the supermarket losing customers.
My concern with Carrefour: extremely thin margins (0.4% average net margin) and two dividend cuts in its history (2018 and COVID). It’s been rising for 5 years since then, but it doesn’t have a perfect track record.
Two positives, two temporary issues, two ways to collect in France.