

Hello my dears,
I personally see dependence on China as a slightly underestimated problem in some areas.
With Russia's attack on Ukraine, we have seen the problems we face as a result of excessive dependencies.
And we are experiencing it again these days.
That's why I'm focusing on the chemical sector today. A sector that most people don't associate with China.
And therefore rather boring and not yet on the radar.
But the stock I have picked out for you today is not boring at all.
Because:
- A player in several growth sectors
- Improves its strategic position through targeted acquisitions
- Low dependence on China
My dears, I look forward to your conclusions in the comments.
🌏 Dependence on China in the global chemicals sector
The global chemical industry is massively dependent on China - structurally, not cyclically. The most important dependencies:
1) Raw materials & primary products
- China dominates >50 % of the global production of many basic chemicals (e.g. intermediates, solvents, additives, specialty chemicals).
- Particularly critical: Rare earths, catalysts, electronic chemicalsfluorine and bromine chemicals.
2) Electronics and semiconductor supply chain
- China is the largest production location for PCBs, smartphones, displays, automotive electronics.
- Chemical companies that supply electronics are heavily dependent on Chinese manufacturing clusters.
🧪 How is Element Solutions (ESI) positioned?
ESI is not a traditional chemical producerbut a supplier of high-quality specialty chemicals for:
- Electronics manufacturing
- printed circuit boards
- semiconductor packaging
- surface treatment
This is crucial, because:
1) ESI is not dependent on raw materials → low dependence on raw materials from China
ESI produces formulations, no base chemicals. → Less exposure to Chinese basic raw materials.
2) ESI supplies know-how, not mass
- Customers buy Process chemistry + technical services.
- These are difficult to copy and cannot simply be replaced by Chinese suppliers.
3) ESI is globally diversified
Production and service centers in:
- USA
- Europe
- Japan
- South East Asia → China is important, but not dominant.
4) ESI benefits from the "China+1" trend
Electronics manufacturers relocate capacities to :
- Vietnam
- Malaysia
- India
- Mexico
ESI supplies chemicals for precisely these new locations → The company moves with its customersinstead of being tied to China.
5) ESI is in high-reliability segments
- automotive
- 5G
- Advanced Packaging
- Server / Data Center
These segments require certified, western specialty chemicals. → Chinese low-cost alternatives hardly play a role here.
🎯 Overall conclusion: Is ESI helping to overcome dependence on China?
Yes - ESI is one of the specialty chemicals players that are structurally helping to reduce dependence on China.
Why?
- Low dependence on raw materials
- Global production network
- Focus on high-tech electronics instead of bulk chemicals
- benefits from the "China+1" shift
- supplies know-how-intensive chemicals that China cannot simply substitute
ESI is therefore a "China resilience play" in the chemical sector - not a China risk play.
No AI without Element Solutions! Specialty chemicals star with record year 2025!
No high-end products such as smartphones or wearables can be manufactured without the necessary basic materials. Specialty chemicals in particular play an important role. Element Solutions is the current frontrunner in this sector with a share price increase of over 43% YTD. Element Solutions develops chemicals for electronics and semiconductors Acquisitions of MicroMax and EFC Gases completed Record year 2025 achieved despite fluctuating metal prices.
Element Solutions Inc. is a global and diversified specialty chemicals company whose businesses offer a broad range of solutions. The company's segments include Electronics and Industrial & Specialties. The Electronics segment researches, formulates and distributes specialty chemicals and process technologies for all types of electronic hardware, from complex printed circuit board designs to advanced semiconductor packaging. The Industry & Specialties segment researches, formulates and distributes specialty chemicals and process technologies that enhance surfaces or improve industrial processes in various industry sectors, from automotive trim to transcontinental infrastructure and from high-speed printing to advanced valves. The company's solutions enable customers' manufacturing processes in several key industries, including consumer electronics, power electronics, semiconductor manufacturing, communications and data storage infrastructure, automotive systems, industrial surface finishing and others.
Number of employees: 5,200
Element_Solutions_25AR-hr-Final.pdf
Element Solutions Inc schließt die Übernahme von Micromax® ab
February 02, 2026
Element Solutions Inc schließt die Übernahme von EFC-Gasen und fortschrittlichen Materialien ab
January 05, 2026
Element Solutions Inc gibt Vereinbarung zur Übernahme von EFC Gases & Advanced Materials bekannt
November 04, 2025
📌 Investor assessment of the three ESI acquisitions
(Micromax®, EFC Gases & Advanced Materials - 2025/2026)
The three transactions are strategically clean, growth-oriented and fit perfectly ESI's positioning as a high-tech specialty chemicals supplier for electronics, semiconductors and surface treatment.
1) 🎯 Strategic logic
Micromax® (02/2026)
- Focus: Electronic materials, printed circuit boards, packaging
- Strengthens ESI's core segment "Electronics Solutions"
- Increases dependence on high-reliability end markets (automotive, 5G, servers)
Strategic value: High Why: Micromax is a "sticky business" - customers rarely change, margins are stable.
EFC Gases & Advanced Materials (01/2026 & 11/2025)
- Focus: Specialty gases, advanced materials for semiconductor manufacturing
- Very attractive market with structural growth (AI chips, packaging, foundries)
- ESI expands its portfolio in the direction of semiconductor process chemistry - a premium segment.
Strategic value: Very high Why: Semiconductor Chemicals is one of the highest-margin specialty chemicals segments worldwide.
2) 📈 Financial impact
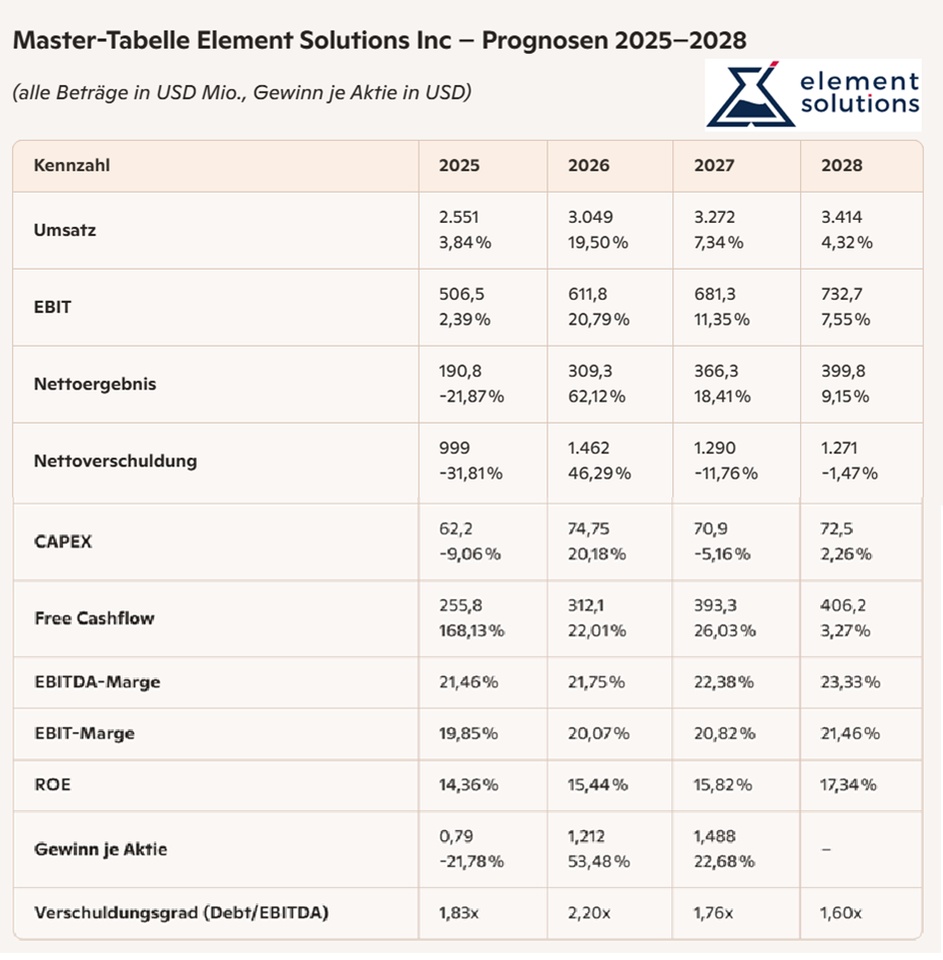
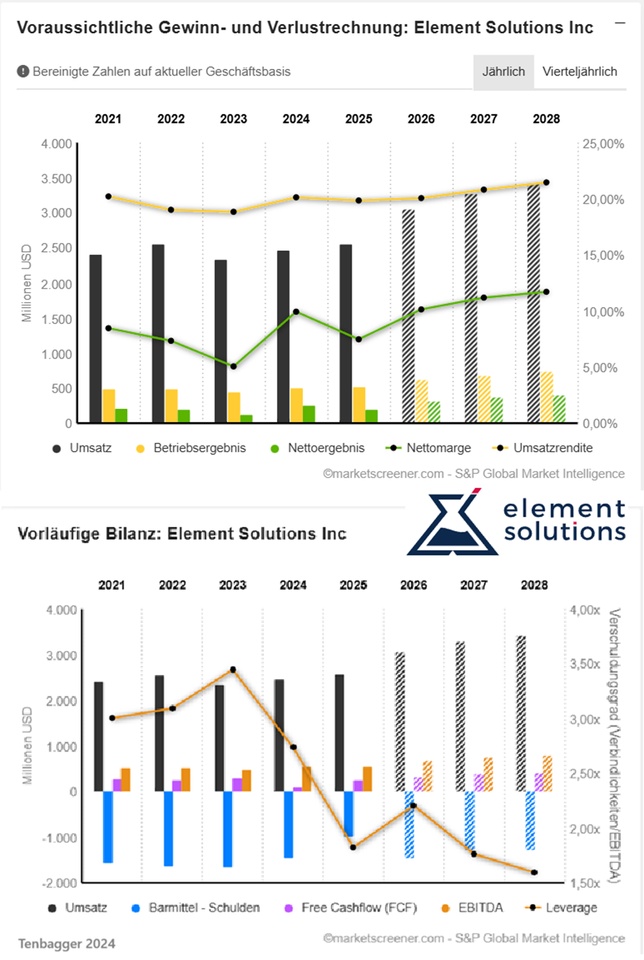
(based on ESI's 2025-2028 forecasts from MarketScreener)
Positive
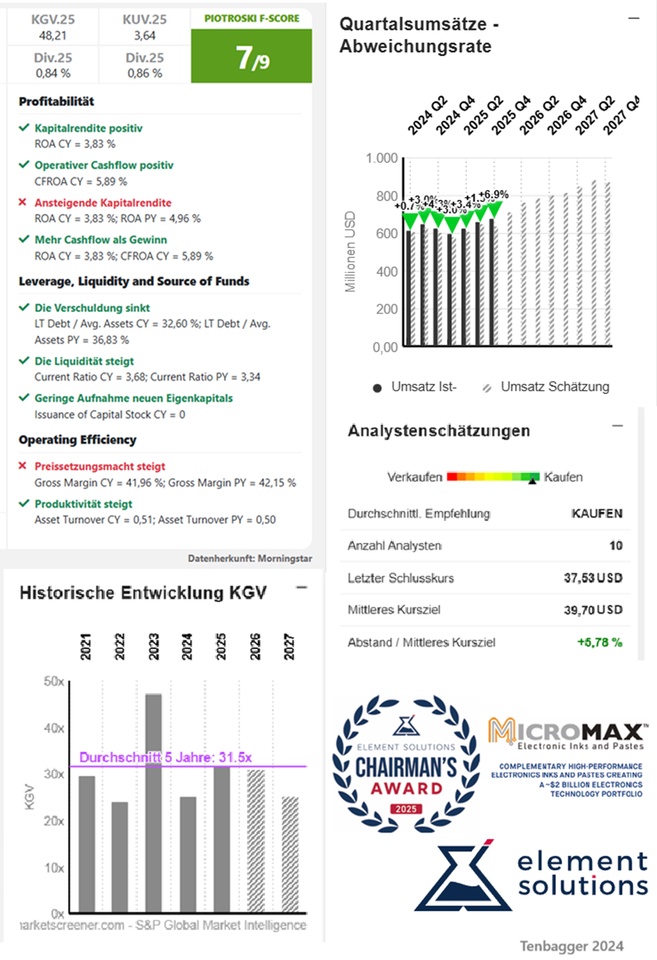
- ESI already shows increasing margins (EBITDA margin 21.5% → 23.3%).
- The acquisitions are high-margini.e. margin-accretive.
- Free cash flow increases significantly in 2025-2028 → acquisitions can be financed.
- Leverage decreases until 2028 → no balance sheet risks.
Neutral / Observe
- ESI traditionally pays fair, but not cheap multiples for high-tech assets.
- Integration needs to run smoothly, but ESI has historically good M&A discipline.
Financial conclusion: The deals are FCF-positive, margin-enhancing and strategically valuable - exactly the kind of M&A you want to see as a shareholder.
3) 🧪 Market position & competitive advantage
The acquisitions strengthen ESI's position in three structurally growing markets:
1) Semiconductor manufacturing
EFC strengthens ESI's role in a market that is growing through AI chips, packaging and foundry expansion (TSMC, Samsung, Intel).
2) Electronics materials
Micromax expands ESI's portfolio in an area that has high barriers to entry.
3) Independence from China
The deals help ESI to become geopolitically more robust position:
- Specialty Gases & Advanced Materials are not easily substituted by China.
- Customers relocate production to Vietnam, Malaysia, India → ESI follows them.
Competitive conclusion: The acquisitions increase ESI's pricing power, customer loyalty and technological relevance.
🎯 Overall conclusion for you as a shareholder
The three acquisitions are clearly positive. They strengthen ESI's strategic position, increase margins, improve cash flow quality and reduce dependence on China.
In short: 👉 ESI is buying exactly the right assets at the right time. 👉 For you as a shareholder, this is a value add, not a risk.
Element Solutions Inc berichtet über Rekordergebnisse im dritten Quartal 2025
October 28, 2025
- Wichtige Märkte
- Automobil
- Computing & Telekommunikation
- Konsumgüter
- Energie & Ressourcen
- Militär, Luft- und Raumfahrt und Medizin
- Mobil & Wearables
THE PILLARS OF OUR STRATEGY
As a results-driven company focused on innovation and service, our strategic pillars guide our behavior and priorities towards long-term success and continuous high performance.
🤝 COMMERCIAL EXCELLENCE:
- TOP CLASS SERVICE:
WINNING THE VIVO MOBILE EXCELLENCE AWARD IN 2025 AND BEST DELIVERY AWARD FOR THE SIXTH CONSECUTIVE YEAR, HIGHLIGHTING THE COMPANY'S CONSISTENTLY HIGH ON-TIME DELIVERY PERFORMANCE, FAST ORDER CONFIRMATION AND RESPONSE SPEED, AND A ROBUST DELIVERY MODEL SUPPORTED BY DIVERSIFIED PRODUCTION AND CAPACITY STRUCTURES.
- LONGSTANDING PARTNERSHIP:
RECOGNIZED WITH THE SUPPLIER AWARD 2025 BY SYRMA SGS, ONE OF THE LARGEST ELECTRONICS MANUFACTURING SERVICE PROVIDERS IN INDIA, FOR EFFECTIVE INNOVATION THAT OPTIMIZED PRODUCTION PROCESSES AND OPERATIONS ACROSS ITS NATIONWIDE OPERATIONS. THE AWARD RECOGNIZES A COLLABORATION AND PARTNERSHIP THAT SPANS MORE THAN 20 YEARS, WITH RECENT CONTRIBUTIONS TO THE INTRODUCTION OF AN ALTERNATIVE PORTFOLIO OF BRAZING ALLOYS AND A LARGE-SCALE TRAINING PROGRAM AT ALL SYRMA SGS SITES.
- LEADING TECHNOLOGY EXPANSION:
OUR NOVAFAB FINE GRAIN COPPER PRODUCT FOR SEMICONDUCTOR CUSTOMERS WAS AWARDED THE 2025 TECHNOLOGY ENHANCEMENT AWARD BY 3D INCITES MAGAZINE. DESIGNED FOR VARIOUS WAFER-LEVEL PACKAGING APPLICATIONS, THIS PRODUCT EXCELS IN HYBRID BONDING AND ENABLES CONTROLLED GRAIN GROWTH DURING ANNEALING, ENSURING DEFECT-FREE BOND FORMATION AND SIGNIFICANTLY IMPROVING QUALITY AND RELIABILITY FOR HIGH-DENSITY BONDING APPLICATIONS AND ADVANCED MECHANICAL AND ELECTRICAL REQUIREMENTS.
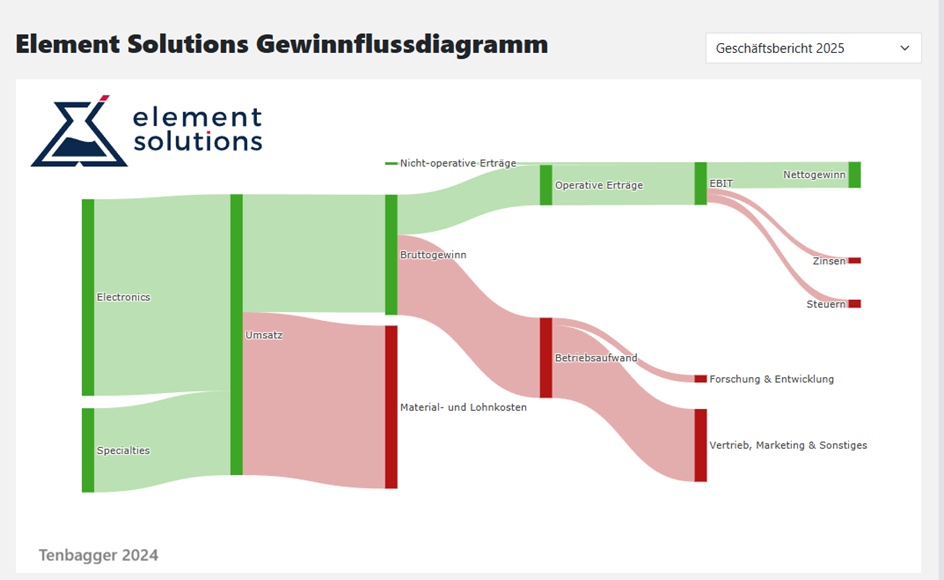
Geographical sales distribution:
(USD 2025)
Other Countries 1.47 billion
China 558 million
USA 524 million
🔹 What is convincing
- Steady sales growth 2025-2028 (USD 2.55 → 3.41 billion) - clean, predictable.
- EBIT + free cash flow increase continuouslyFCF particularly strong 2025-2027.
- Margins improve (EBITDA margin 21.5 % → 23.3 %).
- ROE increases to 17% - good quality feature.
- Leverage ratio decreases by 2028 (1.83x → 1.60x) - financially solid.
🔹 Summary
ESI is a stable, defensive quality stock with solid margins, increasing cash flow and decreasing debt. For a high-growth, momentum-driven portfolio like yours, ESI is is not a core investmentbut as a stable addition quite justifiable.
🔹 Quality
This is where ESI scores the highest.
- ROE rises to 17% - good quality feature.
- EBIT margin 20%+ - stable and slightly increasing.
- Debt-equity ratio decreases by 2028 - financially clean.
- Cash flow consistency is a clear plus point.
Quality conclusion:
High operating quality, stable margins, good return on capital.
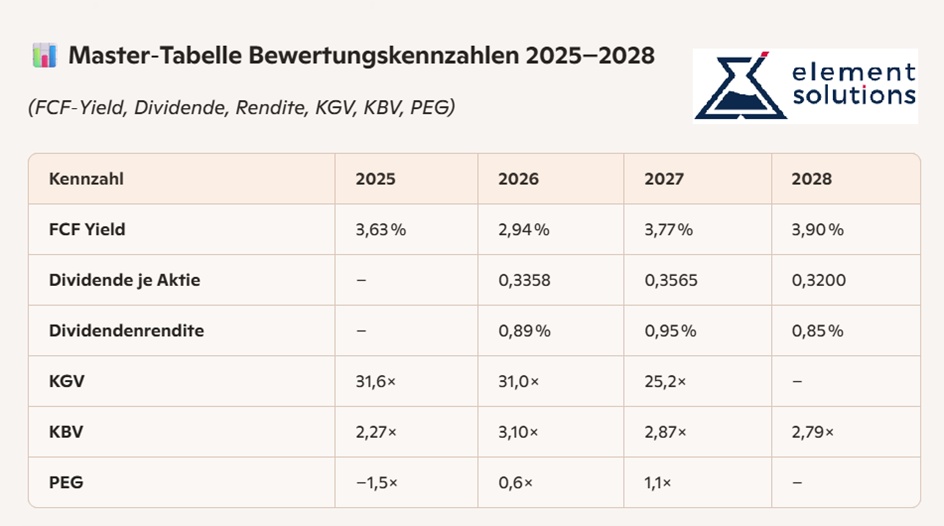
Market value 9,142
Number of shares (in thousands) 243,595
Date of publication 17.02.2026
🎯 Overall valuation (short & honest)
ESI is a quality stock with a fair valuation and moderate growth. Not a value play, not a growth play - but a solid, defensive compounder.
Performance
1 week +10.38 %
1 month +23.23 %
6 months +51.25 %
1 year +102.38 %
3 years +107.44 %
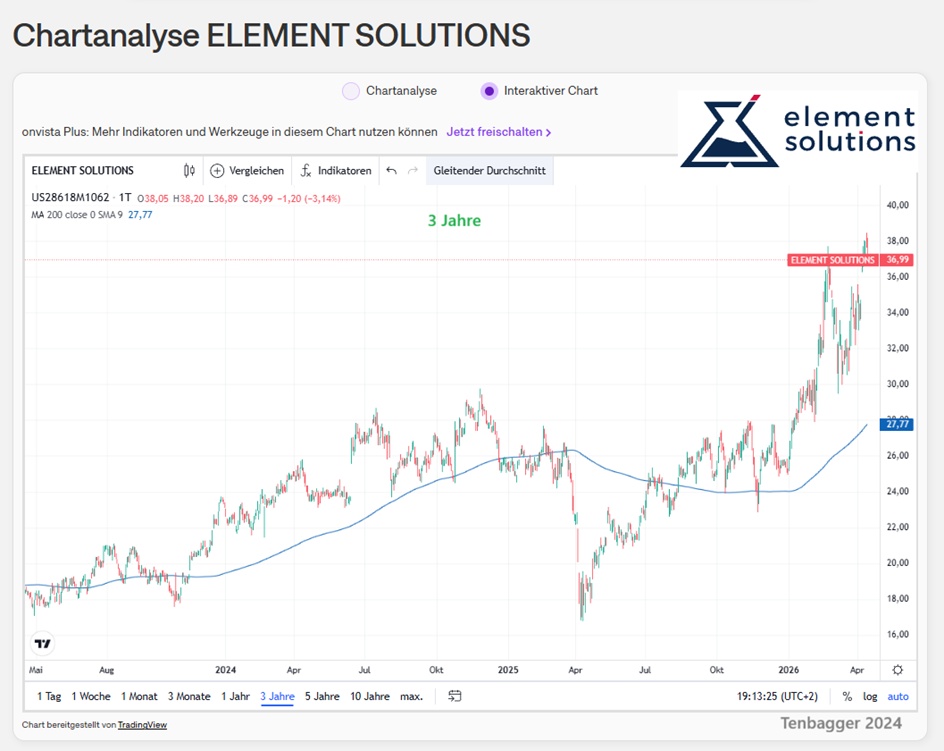
Share price € 32.20. (16.04.2026 at 16:38)


