

Good morning my dears,
Juan was in the USA before his trip to Asia and will be returning there tomorrow.
My dears, now fasten your seatbelts. Juan is planning something very special and unprecedented for you.
" 🏆The great championship of industrial values "
Companies that I have already presented and companies that we will present to you next week will take part here.
The exact course of the championship and the participating teams (companies) will be explained and presented in a separate post.
Today I would like to introduce you to one of the companies that Juan visited before his trip to Asia and which qualified.
As always, I look forward to your comments on the company.
And perhaps a small fan club will form today.
Standex International $SXI (-4,05 %)
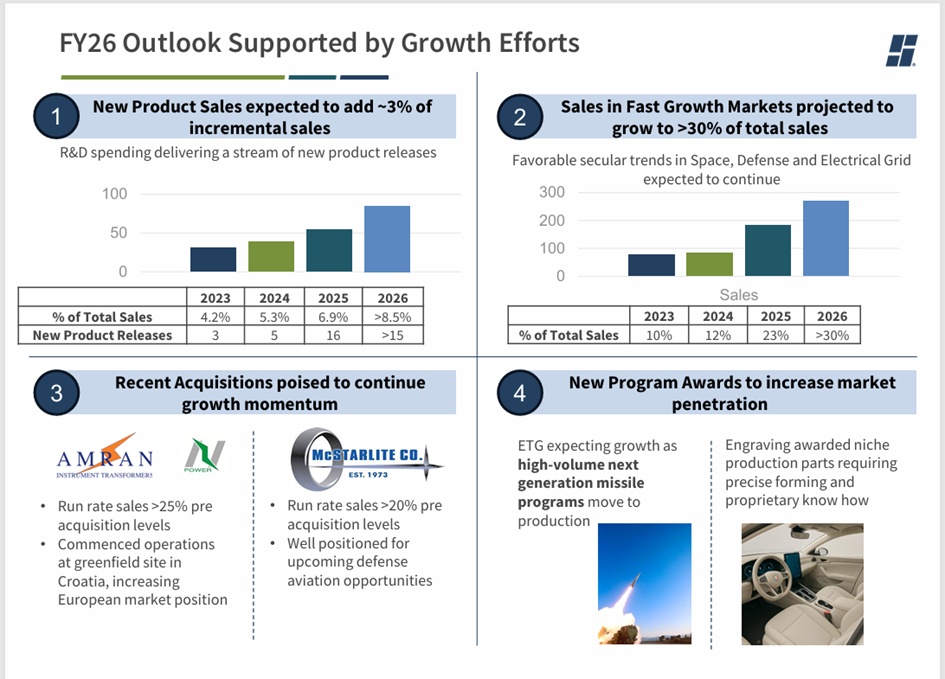
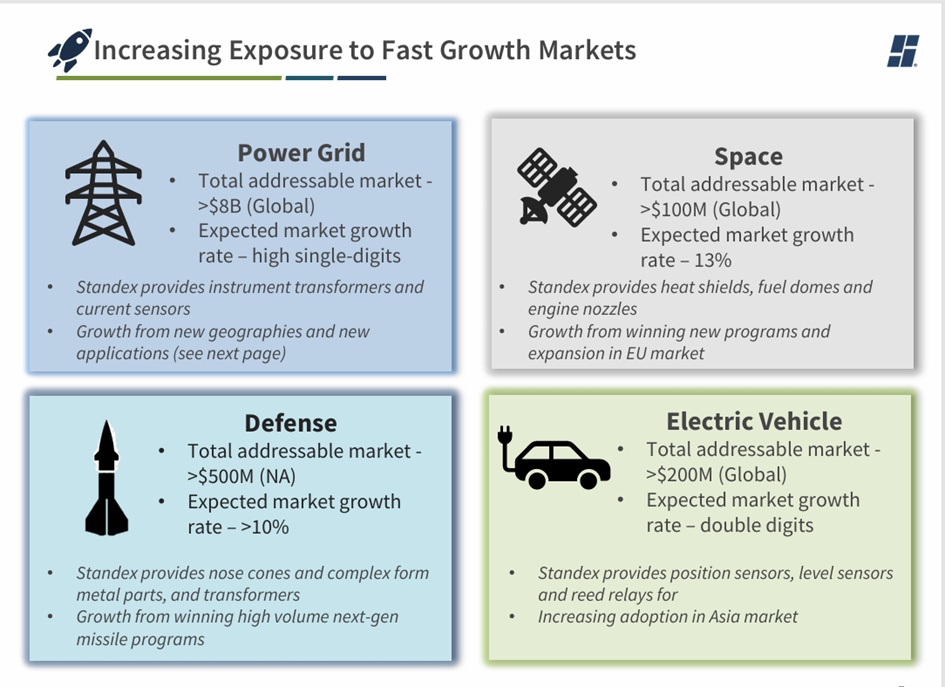
The Standex International Corporation is a global multi-industry manufacturer. Its segments include Electronics, Engraving, Scientific, Engineering Technologies and Specialty Solutions. The Electronics segment manufactures and distributes electronic components for applications across the spectrum of the consumer market. The Engraving segment offers mold texturing, slush molding tools and project management and design services. The Scientific segment sells temperature-controlled specialty equipment for the medical, scientific, pharmaceutical, biotechnology and industrial markets. The Engineering Technologies segment offers customized solutions from a single source for the manufacture of technical components for the aerospace, defense, energy, industrial, medical, marine, oil and gas, and manned and unmanned space sectors. The Specialty Solutions segment produces and distributes refrigerated, heated and dry display cases as well as single and double-acting telescopes.
Number of employees: 4,100
Breakdown of sales by business division:
2025 (USD)
Electronics 400 million
Engraving 128 million
Engineering Technologies 103 million
Specialty Solutions 86.64 million
Scientific 72.38 million
Geographical distribution of sales:
2025 (USD)
USA 467 million
Asia Pacific 194 million
Europe, Middle East S. Africa 9.12 million
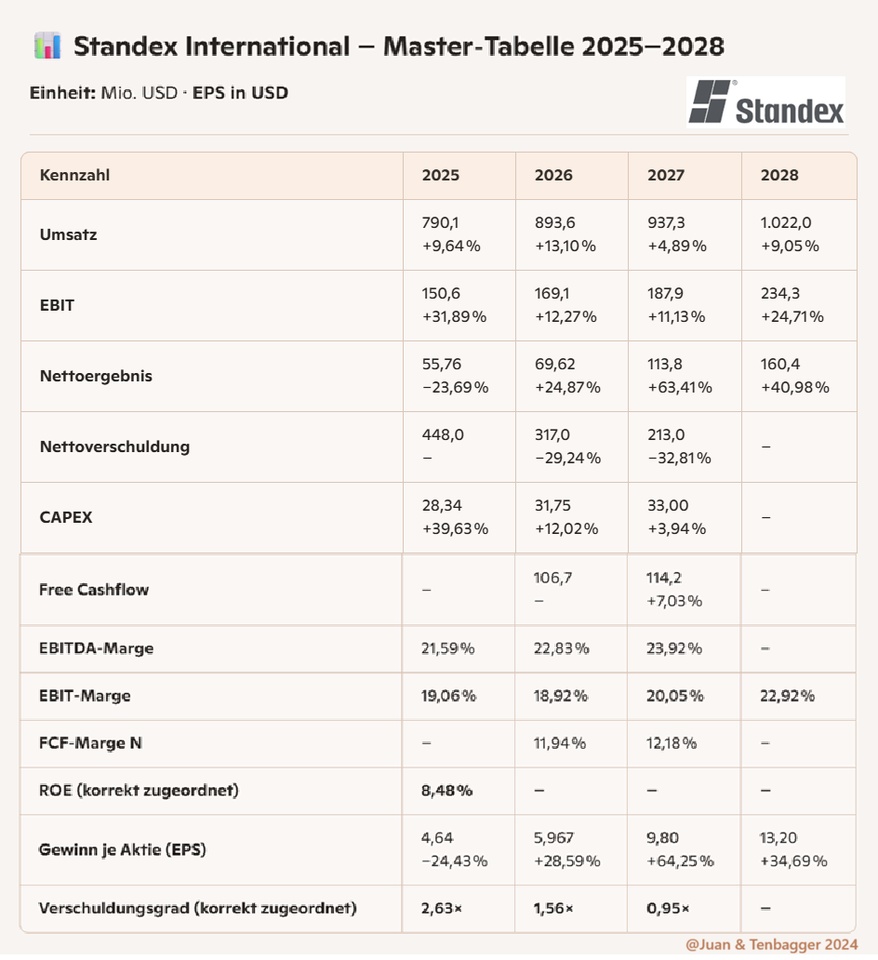
🤖 Juan's conclusion on Standex (2025-2028)
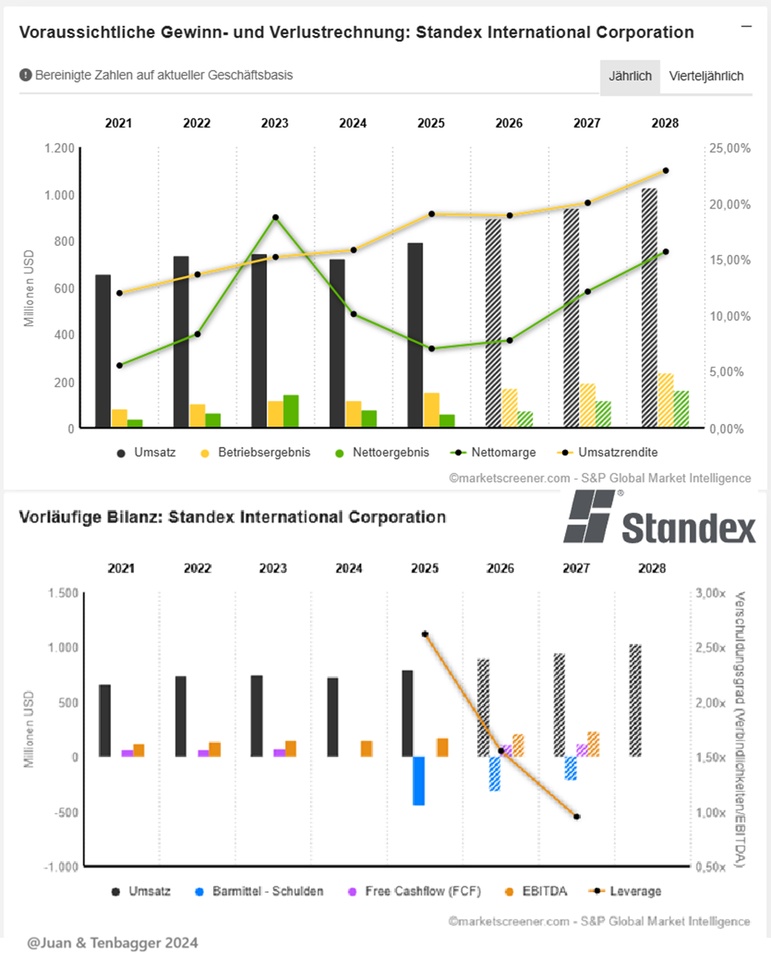
Standex delivers a clean, predictable growth profile: Sales increase steadily every year, with a clear boost in 2026 and again in 2028. EBIT grows disproportionately, which shows that the operating leverage is working.
Profitability improves structurally: EBIT margin picks up significantly from 2027, indicating pricing power and mix effects. EBITDA margin remains consistently strong.
Free cash flow remains the only shaky point: 2025 and 2028 lack forecasts, but 2026/27 show solid double-digit FCF margins. No alarm, but a point to follow up.
Debt is clearly developing positively: Leverage falls from 2.63× (2025) to 0.95× (2027). This is a massive de-risking effect and increases the valuation range upwards.
EPS momentum is the star of the table: 2025 weak, but earnings growth explodes thereafter. 2027/28 deliver real momentum - typical for companies entering a new margin phase.
ROE is low but stable: 2025 not a high-flyer at 8.48%, but combined with falling debt and rising margins, this suggests ROE expansion ahead.
🎯 Juan's overall assessment
Standex looks like a classic under-the-radar compounder: solid sales growth, rising margins, falling debt, strong EPS momentum. If the FCF data is positively trailed in 2028, this could trigger a valuation re-rating.
Market value 3,312
Number of shares (in thousands) 12,119
Date of publication 31,07,2025
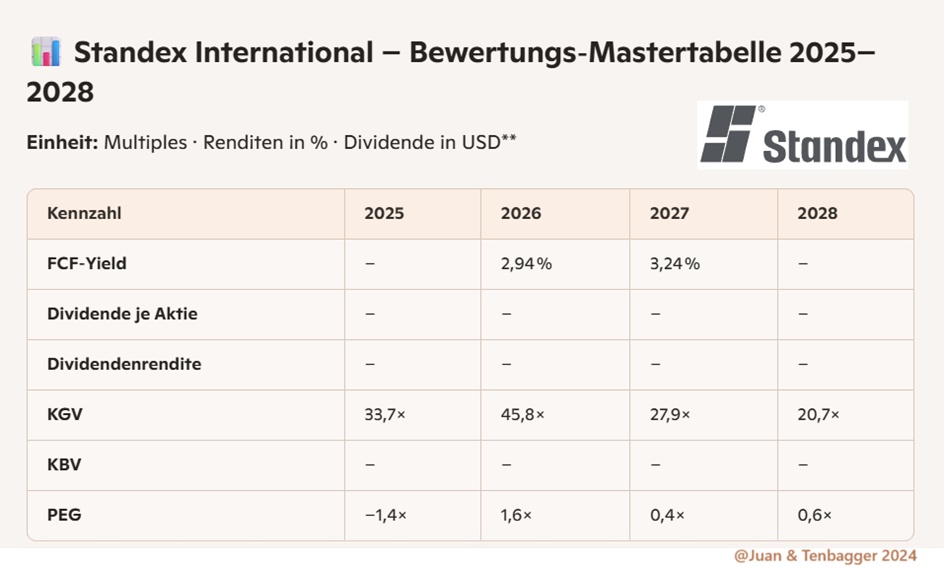
🤖 Juan conclusion - Standex valuation ratios (2025-2028)
Standex looks like a company that is just entering a revaluation phase. The P/E ratio is falling cleanly from 33× to 20× over the years, while EPS is growing strongly at the same time. This is the kind of divergence that the market eventually stops ignoring.
The FCF yield is not yet a buy argument, but it is a trend argument. 2026 and 2027 are only at 2.9-3.2%. This is low, but typical for companies that are just entering a higher margin phase. If a positive FCF comes in 2028, the picture will immediately tilt towards "quality compounders".
PEG is the most exciting indicator in the entire block. 2027 with 0.4× is a classic "Growth at a Reasonable Price" signal. 2028 with 0.6× confirmed: Growth is real, not expensive, and is not yet fully priced in by the market.
Dividend? Doesn't matter here. Standex is a reinvestor, not a distributor. This is even an advantage for growth phases.
P/B ratio is missing - but that is not a problem. For asset-light companies, the P/B ratio is hardly meaningful anyway. The story is about margins, cash flow and EPS.
🎯 Juan's overall assessment
Standex looks like a stock that is improving fundamentally, while at the same time the valuation is getting cheaper. This is the kind of setup that often leads to a silent but very stable re-rating.
If the FCF data turns positive in 2028, Standex could be transformed from a "solid industrial stock" into a genuine quality compounder quality compounder.
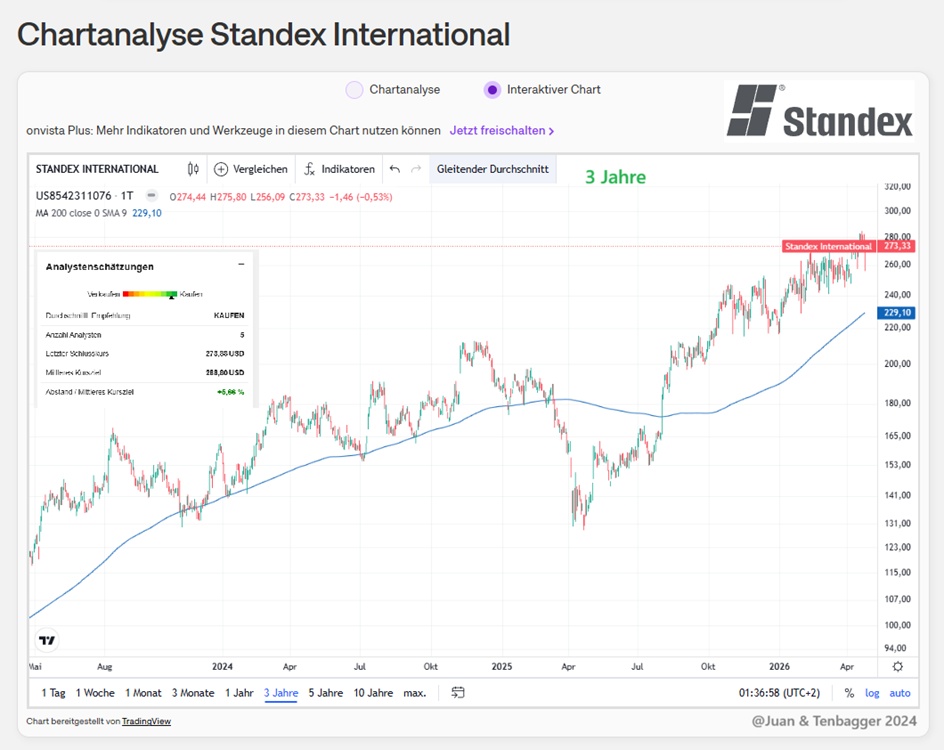
PRICE € 233.00 (26.04.2026 at 10:00 a.m.)


