
McDonald's delivered strong earnings in the third quarter of 2026 but fell short on revenue. Adjusted earnings per share rose 11% to $3.57, well above analysts’ estimates of $3.38; revenue, however, fell short of the consensus estimate of approximately $7.28 billion, coming in at $7.157 billion. Globally, comparable sales rose by 1.5%; in the U.S., however, comparable sales declined slightly by 0.2%—the first such decline in over a year—due to lower customer traffic. The dividend increased by 4% to $1.93 per quarter. On November 4, 2026, the stock jumped by about 5% to approximately $277, moving significantly away from its 52-week low of $229.20. From a technical analysis perspective, there is strong resistance at $286—I expect a pullback toward $261 before the next rally.
Key Points
- Adjusted earnings per share for Q3: $3.57 (+11%), consensus $3.38
- Q3 revenue: $7.157 billion (+1%), missing the consensus estimate of approximately $7.28 billion
- Comparable sales: global +1.5%, U.S. −0.2%, IOM +1.4%, IDL +4.2%
- Dividend up 4% to $1.93 per quarter; loyalty revenue exceeded $11 billion for the quarter
- Analysts: Average price target around $289, range $230 to $390
- Chart levels: resistance at $286, target at $325, support levels at $261.78 and $247.18
What are the current key figures for McDonald’s stock?
On November 4, 2026, McDonald’s stock traded on the NYSE at around $277, up a solid 5% from the previous day’s close of $263.04. With an adjusted P/E ratio of around 22, the stock is below its 10-year average of 23.5; the dividend yield is approximately 2.8%. However, it is still about 19% below its 52-week high of $341.75.
- Price (NYSE: MCD): approx. $277 (approx. +5%) (November 4, 2026)
- Previous day’s closing price: $263.04 (November 3, 2026)
- 52-week high (all-time high): $341.75 (spring 2026)
- 52-week low: $229.20 (October 2026)
- Q3 2026 revenue: $7.157 billion (+1%, consensus approx. $7.28 billion) (November 4, 2026)
- Adjusted earnings per share for Q3: $3.57 (+11%, consensus $3.38) (November 4, 2026)
- Reported earnings per share for Q3: $3.51 (+10%) (November 4, 2026)
- Operating income for Q3: $3.595 billion (+7%, adjusted +8%) (November 4, 2026)
- Comparable sales, global / U.S.: +1.5% / −0.2% (November 4, 2026)
- Comparable sales IOM / IDL: +1.4% / +4.2% (November 4, 2026)
- System-wide revenue for Q3: over $38 billion (+4%) (November 4, 2026)
- Revenue from loyalty members: over $11 billion for the quarter, $41 billion over 12 months (November 4, 2026)
- Q3 restructuring costs: $56 million ($0.06 per share) (November 4, 2026)
- Quarterly dividend: $1.93 (+4%, $7.72 annually, yield approx. 2.8%) (Nov. 4, 2026)
- P/E ratio (adjusted): approx. 22 (10-year average 23.5) (Nov. 4, 2026)
- Average analyst price target: approx. $289 (November 4, 2026)
- Next Earnings Report (Q4 and Full Year 2026): expected in early February 2027 (not yet confirmed)
- WKN / ISIN / Ticker: 856958 / US5801351017 / MCD
What news is currently driving McDonald’s stock?
McDonald’s stock is currently being driven primarily by the mixed third-quarter results: a clear earnings beat, but revenue that fell short and weaker U.S. customer visits. The market celebrated nonetheless—the stock rose about 5% on the day the results were released because management reported an improvement in the U.S. business over the course of the quarter. Added to this are the 4% dividend increase and a series of lowered price targets in the run-up to the earnings release. A strong brand, but consumers aren’t keeping pace? Investors are all too familiar with this very tension from Adidas Aktie — at McDonald’s, it’s now up to the value-driven strategy to bring customers back.
- November 4, 2026 – Earnings well above expectations: Adjusted earnings per share of $3.57 (+11%) instead of the expected $3.38; reported $3.51. (Very bullish)
- November 4, 2026 – Revenue misses consensus: Revenue of $7.157 billion (+1%) instead of approximately $7.28 billion; same-store sales −3%. (Bearish)
- November 4, 2026 – U.S. sales decline: Comparable sales in the U.S. down 0.2%; fewer customer visits only partially offset by higher average check; first decline in over a year. (Bearish)
- November 4, 2026 – Dividend +4%: Quarterly dividend rises to $1.93 per share. (Bullish)
- November 4, 2026 – Stock jumps by about 5%: From the previous day’s close of $263.04 to around $277. (Bullish)
- November 4, 2026 – TD Cowen maintains its “Hold” rating: Price target of $270; Q4 comparable sales in the U.S. are expected to be −2%. (Neutral)
- November 3, 2026 – Questions about algorithmic pricing: U.S. Senator Elizabeth Warren and other lawmakers question McDonald’s about its use of pricing algorithms (according to Reuters). (Bearish)
- November 3, 2026 – Bernstein: Market Perform: Price target lowered to $250. (Neutral)
- September 23, 2026 – Investor Day: NEXT Plan: $8.5 billion in support for franchisees through 2036; targeting an operating margin in the low to mid-50% range by 2030. (Neutral)
What does McDonald’s management have to say about the Q3 results?
CEO Chris Kempczinski sees one key signal emerging from the third quarter: The value initiative in the U.S. is working. According to a press release, the U.S. business showed improvement “over the course of the quarter” following measures to enhance value for money, and the focus is now on building on that and investing in the next chapter of growth.
What went well: Internationally, things went smoothly—led by Germany, Australia, and Japan. System-wide revenue grew by 4% to over $38 billion, and McDonald’s generated over $11 billion in revenue from loyalty members during the quarter. Franchise revenue rose by 3%.
The catch: In the U.S., fewer guests visited, and the decline was only nearly offset by higher average check sizes. France and China posted declines. In addition, operating income was supported by higher other operating income, which rose from $37 million to $139 million. Without this effect, operating income would have grown by only about 4% instead of 7%, according to my calculations.
Outlook: No new forecast was provided. The targets set at Investor Day remain in effect: approximately $3 billion in annual investments starting in 2027, an operating margin in the low to mid-50% range by 2030, and a growth contribution from new restaurants of just under 2.5% to system-wide revenue in 2027. For 2027, McDonald’s is testing additional entry-level offers in the value segment.
What does McDonald’s do—and how does the company make its money?
McDonald’s makes its money primarily as a franchisor and real estate owner—not by selling burgers in its own restaurants. The company operates over 45,000 restaurants in more than 100 countries, about 95% of which are run by independent franchisees.
Franchise revenue: Rent, licensing fees, and revenue shares from franchisees are at the heart of the business. In the third quarter of 2026, these revenues rose by 3% to $4.487 billion—this is the high-margin core of the business model.
Company-Owned Restaurants: McDonald’s generated $2.480 billion in revenue from company-owned restaurants, down 3% from the previous year. This segment is significantly less profitable and is directly affected by customer traffic and costs.
Regions: McDonald’s reports in three segments—the U.S., International Operated Markets (IOM, such as Germany, France, and Australia), and International Developmental Licensed Markets (IDL, licensed markets such as Japan and China). In the third quarter, IDL posted the strongest growth at +4.2%, IOM rose by 1.4%, and the U.S. was down slightly at −0.2%.
The NEXT Plan Sets the Course: At Investor Day in September 2026, McDonald’s presented its plan for the coming years. By 2036, approximately $8.5 billion is to be invested in supporting franchisees, with $5 billion of that allocated by 2030. At the same time, management is targeting an operating margin in the low to mid-50% range by 2030. For investors, the key question is: Will this investment bring U.S. customers back—or will it weigh on profits in the short term, as some analysts fear?
Fundamental Analysis: Is McDonald’s Stock Undervalued Following the Q3 Results?
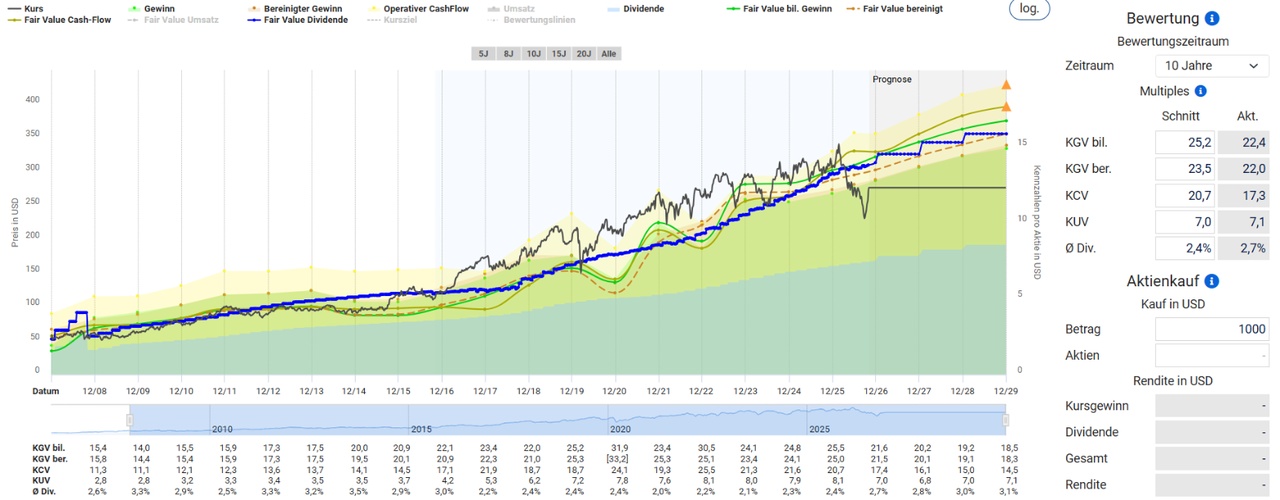
Based on the Q3 results, McDonald’s stock, with an adjusted P/E ratio of around 22, is valued slightly lower than its 10-year average of 23.5—but it’s not a bargain. According to Aktienfinder, the price-to-cash-flow ratio of 17.3 is also below the long-term average of 20.7, while the dividend yield of about 2.7% is above the average of 2.4%.
Earnings Quality: Adjusted earnings per share rose 11% to $3.57 in the third quarter, while revenue increased by only 1% to $7.157 billion. Part of the jump in earnings stems from higher other operating income ($139 million instead of $37 million) and a lower number of outstanding shares. The core operating business is thus growing more slowly than the headline suggests.
Margins: Operating income of $3.595 billion, on revenue of $7.157 billion, corresponds to an operating margin of approximately 50%. With its NEXT plan, McDonald’s aims to raise this figure to the low to mid-50% range by 2030—the franchise model makes such margins possible.
Cash Flow and Investments: Starting in 2027, McDonald’s plans to invest approximately $3 billion annually, plus an additional $1.5 to $2 billion in support for franchisees through 2030. This ties up capital but is intended to secure growth in the coming years. Today’s Novo Nordisk Aktie has shown today just how powerful a profit beat can be—but the key question remains whether the recovery in the core business is sustainable.
Dividend: The quarterly dividend is rising by 4% to $1.93, which amounts to $7.72 per share on an annualized basis. At the current price of around $277, this corresponds to a yield of about 2.8%. McDonald’s has been one of the most reliable dividend payers in the S&P 500 for decades.
McDonald’s Stock Price Targets and Forecast for 2026
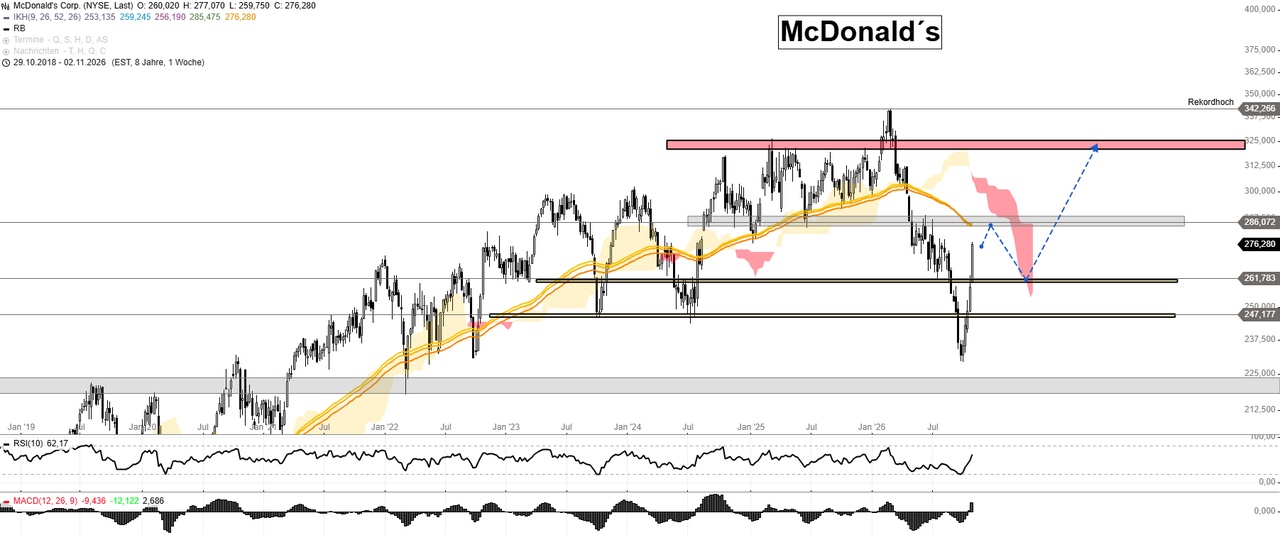
Analysts see an average price target of around $289 for McDonald’s stock, which is only about 4% above the current price of around $277. According to StockAnalysis, the range extends from $230 to $390. From a technical analysis perspective, the outlook is clearly defined: strong resistance lies at $286; only once this level is breached does the probability of follow-on buying increase, potentially pushing the price up to $325.
Defensive quality stocks with stable dividends will experience a volatile year in 2026—if you’d like to compare McDonald’s with another dividend stock, you’ll find Telekom Aktie Analyse a similarly defensive profile with its own unique price levels.
Key price levels:
- 52-week high: $341.75 (all-time high, spring 2026; $342.27 on the Stock3 chart)
- Current price: approx. $276–$277 (Nov. 4, 2026; previous day’s close $263.04)
- First resistance: $286 (gray resistance zone)
- Second resistance: $325 (red resistance zone)
- First support: $261.78
- Second support: $247.18
- Critical support level: 247.18 USD (below this, the 52-week low of 229.20 USD comes into focus)
Analyst price targets:
- Average price target: approx. $289 (StockAnalysis: $291.75 based on 33 analysts; TipRanks: $285.91)
- Bank of America: Hold, $343 (October 26, 2026)
- UBS: Buy, $320 (as of November 4, 2026)
- Citi: Buy, $295 (end of October 2026)
- BTIG: Buy, $295 (October 27, 2026)
- RBC Capital: Sector Perform, $285 (November 3, 2026)
- KeyBanc: Overweight, $280 (as of November 4, 2026)
- TD Cowen: Hold, $270 (November 4, 2026)
- Mizuho: Neutral, $260 (October 30, 2026)
- Bernstein: Market Perform, $250 (November 3, 2026)
]
Chart Analysis:
On the weekly chart, McDonald’s stock is showing a strong rebound: From its low of $229.20, the stock has climbed vigorously, and the third-quarter results are adding to the momentum. However, resistance awaits at $286, which won’t be easy to break through. The gray resistance zone runs precisely through this area, where the stock has bounced off multiple times in the past.
If the stock does manage to break above $286, the likelihood of further buying momentum up to $325 increases significantly—that’s where the red resistance zone lies, just below the record high of $342.27. My most likely scenario, however, calls for a detour first: From the resistance at $286, I expect a pullback to the support level at $261.78 before the next push toward $325 begins. I would definitely factor this detour into my plans. Below that, $247.18 forms the next key support level.
To me, this means one thing very clearly: I would wait to buy. After a rise of about 20% from the low, the risk-reward ratio just below the $286 resistance level isn’t attractive—patient investors should let the stock come to them.
Conclusion: McDonald’s Stock—A Predictable Rebound or a Bull Trap?
Following the Q3 results, McDonald’s stock is a rebound that was on the horizon, but not an immediate buy—I’m waiting for the pullback. Earnings per share came in at $3.57, well above expectations; the dividend is rising by 4%; and business is performing solidly internationally. At the same time, revenue of $7.157 billion fell short of the consensus; U.S. customer traffic declined, and operating income was propped up by other income.
With a P/E ratio of around 22, the stock is fairly valued, but not cheap, and analysts’ average price target of around $289 leaves little room to run. From a technical perspective, resistance at $286 stands in the way. My plan: A pullback from the resistance level down to $261 is likely; only after that do I expect the next upward move. If the stock breaks above $286, the likelihood of follow-on buying up to $325 increases.
The fact that strong quarterly results can really give a stock a boost was recently SAP Aktie —for McDonald’s, the decisive break above $286 has yet to materialize.
Opportunities and Risks of McDonald’s Stock
✅ Opportunities
- Earnings beat: adjusted earnings per share of $3.57 instead of the expected $3.38
- Improvement in U.S. business over the course of the quarter following the value initiative
- Strong international business: IDL +4.2%, IOM +1.4%
- Loyalty revenue of over $11 billion for the quarter
- Dividend up 4% to $1.93 per quarter (approx. 2.8% yield)
- A breakout above $286 opens the door to $325
⚠️ Risks
- Revenue of $7.157 billion fell short of the consensus estimate of approximately $7.28 billion
- U.S.: Comparable sales down 0.2% and fewer customer visits
- Operating income supported by other income (139 million USD instead of 37 million USD)
- High capital expenditures: approximately $3 billion per year starting in 2027, plus franchise support
- Limited upside potential to the average price target of approximately $289
- A pullback to $261.78 is likely; a move below $247.18 could signal further weakness
Sources
- McDonald’s press release: McDonald’s Reports Third Quarter 2026 Results (Nov. 4, 2026, Form 8-K, SEC; identical to PR Newswire)
- McDonald’s Investor Day 2026: Financial Targets (Form 8-K, SEC, September 23, 2026)
- McDonald's Investor Relations
- CNBC: McDonald's Earnings Beat, but Traffic to Its U.S. Restaurants Falls (November 4, 2026)
- 24/7 Wall St.: McDonald's Rises 5% as Earnings Beat Outweighs U.S. Sales Dip (November 4, 2026)
- MoneyCheck: McDonald's Stock Rises as Profit Beat Outweighs Revenue Miss (November 4, 2026)
- Investing.com: TD Cowen Maintains Price Target of $270 (November 4, 2026)
- StockAnalysis: Price, 52-Week Range, Analyst Price Targets for McDonald's
- TipRanks: McDonald's Analyst Price Targets
- Alpha Vantage: Weekly Prices for McDonald’s (NYSE: MCD)
- Stock3: Weekly Chart for McDonald’s (NYSE, USD), as of Nov. 4, 2026
- Aktienfinder: Fair value calculation and valuation metrics for McDonald’s, as of November 4, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What are your current thoughts on $MCD (+0,04 %)?