
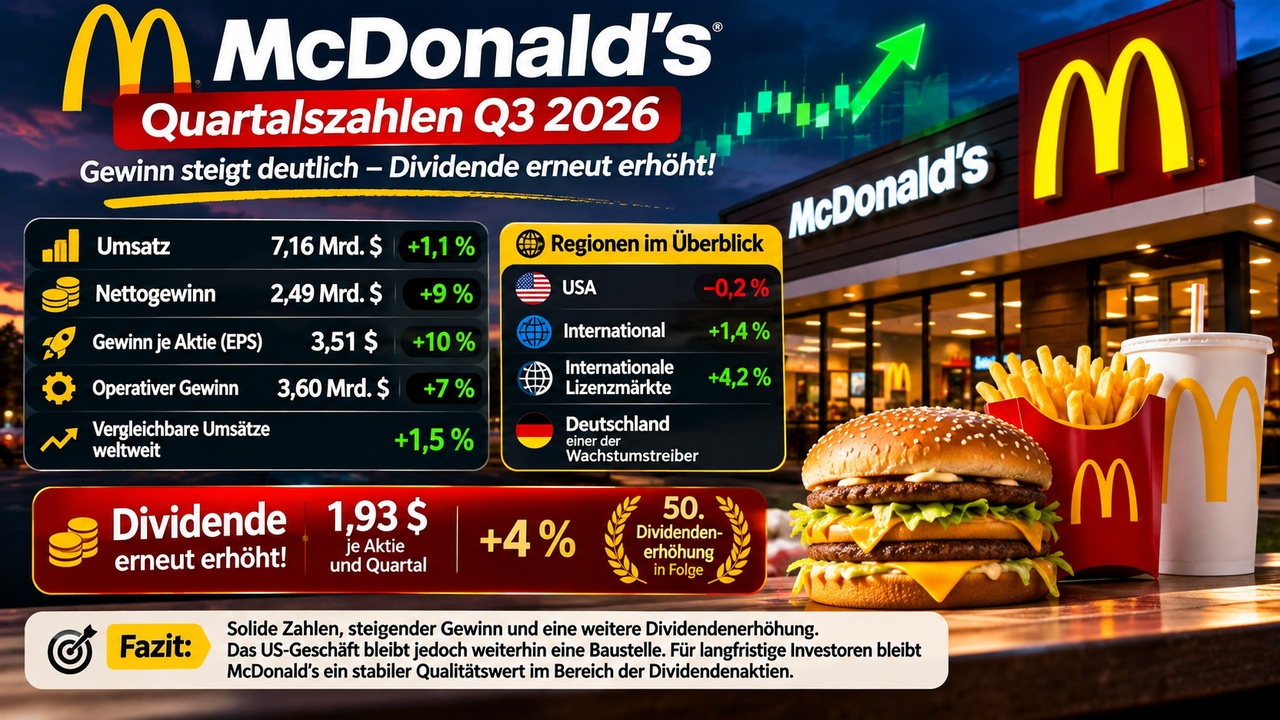
McDonald’s released its third-quarter 2026 financial results today. And the results are quite interesting for long-term investors and dividend investors.
Key figures:
● Revenue: $7.16 billion (+1.1%)
● Earnings per share: $3.57 (previous year: $3.22)
● Operating profit: +7%
● Global comparable sales: +3.6%
● Dividend: $1.93 per share per quarter
McDonald’s exceeded analysts’ expectations in terms of earnings. However, the company’s revenue fell slightly short of forecasts.
What particularly stands out to me:
While earnings are growing significantly faster than revenue, the U.S. business remains challenging. Comparable sales in the U.S. declined by 0.2%.
Internationally, on the other hand, things are going much better. The international franchise markets, in particular, delivered strong results.
Customer loyalty is also an interesting development: The loyalty program generated more than $11 billion in revenue worldwide last quarter.
For dividend investors:
McDonald’s has increased its dividend for the 50th consecutive time. The company thus remains an attractive candidate for long-term income strategies.
However, one should not overlook the valuation. Quality comes at a price, and even with a dividend aristocrat, you shouldn’t buy blindly.
My conclusion:
McDonald’s remains a strong global corporation with enormous brand power. Earnings growth is solid, but the weaker U.S. business and the valuation remain important factors.
What’s your take on McDonald’s right now? Do you see the stock as a long-term buy, or would you rather wait for a cheaper entry point?
#McDonalds
#Aktien
#Dividenden
#Quartalszahlen
#LangfristigesInvestieren
