
$MC (+0,54 %)
$MBG (-0,18 %)
$ULVR (+2,65 %)
$PYPL (+0,99 %)
$NBIS (-4,55 %)
$SPGI (+2,49 %)
$UPS (+2,6 %)
$KO (+1,58 %)
$GLW (-9,9 %)
$BA (+0,24 %)
$KER (+0,23 %)
$ENPH (+0,69 %)
$NXPI (-4,43 %)
$STX (-2,1 %)
$BE (-5,89 %)
$V (+1,74 %)
$MDLZ (+0,34 %)
$000660
$P911 (+0,64 %)
$BN (+1,35 %)
$RMS (+1,16 %)
$BAS (+0,73 %)
$AG1 (-4,41 %)
$LMND (+1,4 %)
$SOFI (+2,21 %)
$NDX1 (-3,23 %)
$TER (-12,14 %)
$GD (+0,39 %)
$APH (-5,81 %)
$AIR (-2,28 %)
$SBUX (+0,66 %)
$CMG (+2,41 %)
$META (+3,04 %)
$FTNT (+9,84 %)
$QCOM (-0,15 %)
$LRCX (-7,31 %)
$HOOD (+2,32 %)
$ARM (-8,76 %)
$MSFT (+2,35 %)
$CVNA (+2,62 %)
$005930
$SU (-5,92 %)
$INGA (-0,61 %)
$OR (+1,29 %)
$BMW (-0,89 %)
$BATS (+3,7 %)
$MA (+1,3 %)
$ADS (+1,02 %)
$SHEL (+0,32 %)
$RACE (-0,71 %)
$RDDT (+3,69 %)
$TEM (+5,6 %)
$COIN (+9,38 %)
$AAPL (+0,48 %)
$AMZN (-0,69 %)
$CCO (-3,01 %)
$LIN (-0,27 %)
$ABBV (+2,49 %)
$PUM (+1,08 %)
$HAG (+0,67 %)
$XOM (-0,13 %)
$CVX (-0,41 %)
Cameco
Price
Discussion sur CCO
Postes
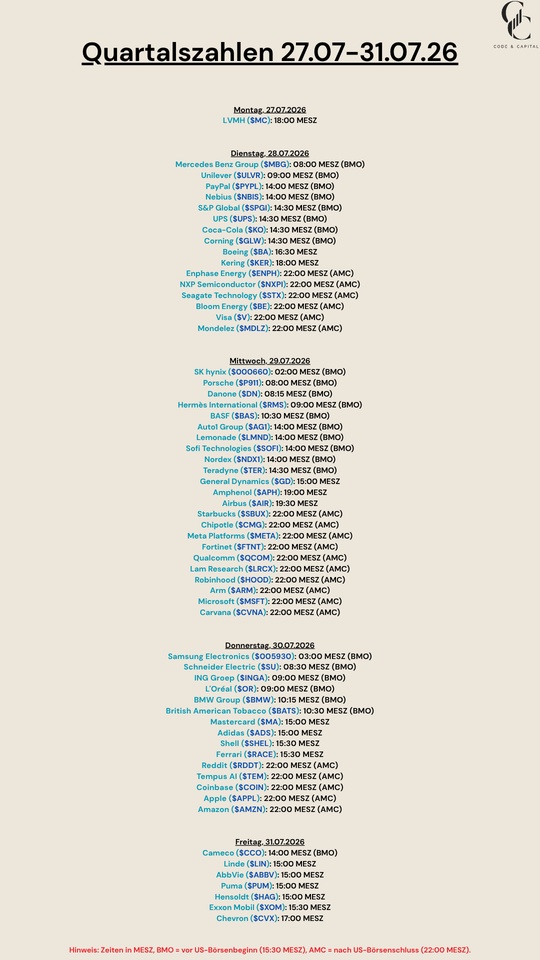
49Quartalszahlen 27.07-31.07.26

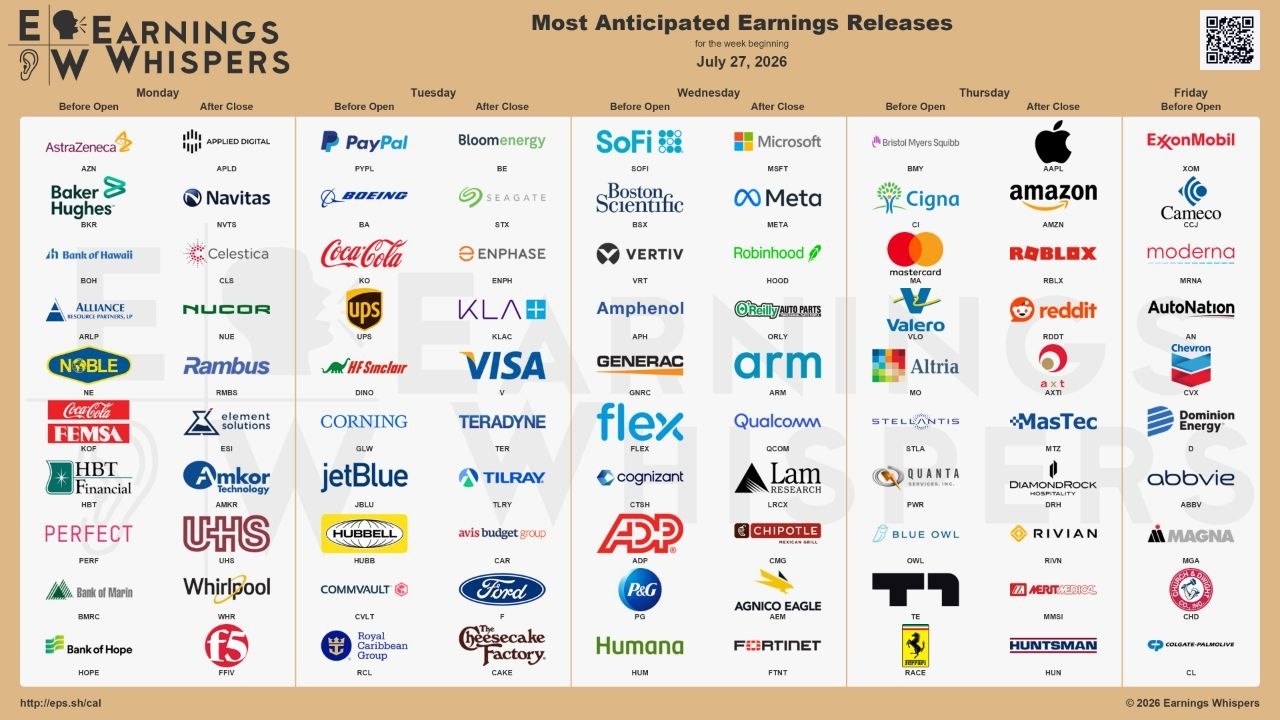
Die Woche voraus
Montag, 27. Juli
10:00 Uhr: DE Ifo-Geschäftsklimaindex (Wichtigstes deutsches Konjunkturbarometer)
14:30 Uhr: US Auftragseingänge langlebiger Güter
16:00 Uhr: US Dallas Fed Index (Verarbeitendes Gewerbe)
Dienstag, 28. Juli
16:00 Uhr: US CB Verbrauchervertrauen (Juli)
16:00 Uhr: US JOLTS (Offene Stellenangebote – wichtig für US-Arbeitsmarkt)
Mittwoch, 29. Juli
20:00 Uhr: US Fed Zinsentscheid 🌶
20:30 Uhr: US Fed Pressekonferenz
Donnerstag, 30. Juli
10:00 Uhr: DE Bruttoinlandsprodukt (Q2)
14:00 Uhr: DE Inflationsrate (Juli) 🌶
14:30 Uhr: US PCE-Kernrate (Bevorzugter Fed-Inflationsindikator) & Erstanträge Arbeitslosenhilfe 🌶
Freitag, 31. Juli
11:00 Uhr: EU Inflationsrate & BIP (Q2) 🌶
15:45 Uhr: US Chicago Einkaufsmanagerindex
$PYPL (+0,99 %)
$KO (+1,58 %)
$BA (+0,24 %)
$MSFT (+2,35 %)
$V (+1,74 %)
$AZN (+2,3 %)
$META (+3,04 %)
$HOOD (+2,32 %)
$AAPL (+0,48 %)
$MA (+1,3 %)
$XOM (-0,13 %)
$CVX (-0,41 %)
$CCO (-3,01 %)
$ARM (-8,76 %)
$QCOM (-0,15 %)


Trades of the day
$GOOGL (+3,32 %) slipped on a stop loss then I bought more $AMZN (-0,69 %) and more $CCO (-3,01 %)
Still looking everyday at my $MU (-4,53 %) for the time to sell this gains but it doesn’t stop 🚀


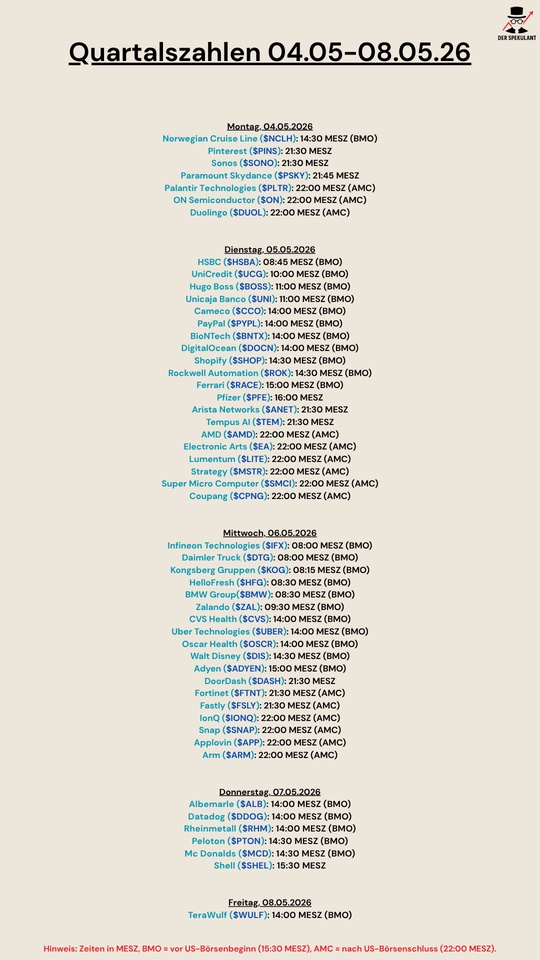
Quartalszahlen 04.05-08.05.26
$NCLH (+0,11 %)
$PINS (+4,29 %)
$SONO (+3,53 %)
$PARA (+4,61 %)
$PLTR (+4 %)
$DUOL
$HSBA (-0,83 %)
$UCG (-0,88 %)
$BOSS (+0,34 %)
$UNI (-0,52 %)
$CCO (-3,01 %)
$PYPL (+0,99 %)
$BNTX (+2,18 %)
$DOCN (-2,73 %)
$SHOP (+4,04 %)
$ROK (-1,81 %)
$RACE (-0,71 %)
$PFE (+0,42 %)
$ANET (-4,85 %)
$TEM (+5,6 %)
$AMD (-3,54 %)
$EA
$LITE (-9,11 %)
$MSTR (+4,8 %)
$SMCI (-7,15 %)
$CPNG (+0,94 %)
$IFX (-6,93 %)
$DTG (-0,21 %)
$KOG (+1,56 %)
$HFG (+2,07 %)
$BMW (-0,89 %)
$ZAL (+1,48 %)
$CVS (+1,36 %)
$UBER (+1,52 %)
$OSCR (+3,62 %)
$DIS (+2,48 %)
$ADYEN (+2,41 %)
$DASH (+1 %)
$FTNT (+9,84 %)
$FSLY (+8,11 %)
$IONQ (+2,38 %)
$SNAP (+3,17 %)
$APP (+3,54 %)
$ARM (-8,76 %)
$ALB (-1,66 %)
$DDOG (+3,86 %)
$RHM (+0,21 %)
$PTON (+0 %)
$MCD (+2,32 %)
$SHEL (+0,32 %)
$WULF (-7,24 %)
Der Bullenmarkt als Tarnung — Warum Strukturprobleme so lange unsichtbar bleiben
Lesedauer: ca. 3 Minuten
Es gibt einen Fehler, den ich für einen der teuersten im Investieren halte: einen zyklischen Rückgang mit einem strukturellen Problem zu verwechseln. Oder umgekehrt. Beides kostet Geld, aber auf sehr unterschiedliche Weise.
Der zyklische Rückgang ist temporär. Ein Unternehmen verdient weniger, weil die Nachfrage gerade schwach ist. Das Geschäftsmodell ist intakt, die Wettbewerbsposition auch. Der Gewinn erholt sich, wenn der Zyklus dreht. Wer in dieser Phase verkauft, verbucht einen Verlust und verpasst die Erholung.
Das strukturelle Problem ist etwas anderes. Hier verändert sich etwas Fundamentales am Geschäftsmodell selbst. Ein Wettbewerber macht das Produkt überflüssig, oder die Nachfrage verschwindet dauerhaft. Der Gewinn erholt sich nicht, weil es nichts zu erholen gibt. Wer in dieser Phase hält, wartet auf eine Normalisierung, die nicht kommt.
Die Schwierigkeit: Beide sehen im Chart identisch aus. Kurs fällt, Stimmung dreht. Das Unterscheidungsmerkmal liegt nicht im Kursverlauf, sondern in der Ursache.
Ich beginne deshalb mit einer einfachen Frage: Hat das Unternehmen ein Problem, oder hat die Branche ein Problem? Und wenn die Branche ein Problem hat: Löst es sich von selbst auf, weil es aus Überangebot oder temporärer Nachfrageschwäche entsteht? Oder ist es dauerhaft, weil ein Wettbewerber oder eine Technologie die Grundlage des Geschäftsmodells verändert?
$MU (-4,53 %) , also Micron Technology, ist das vielleicht reinste Lehrbuchbeispiel für den ersten Fall. Der Speicherchip-Markt läuft in ausgeprägten Überangebots- und Knappheitsphasen. Wenn die Preise fallen, sehen Microns Zahlen katastrophal aus. Wenn sie steigen, explodiert der Gewinn. 2022 war brutal. Die Nachfrage brach ein, Lagerbestände türmten sich auf, Analysten überboten sich mit Kurszielsenkungen. Wer damals verkaufte und 2023 wieder kaufte, hat zweimal Transaktionskosten produziert und die Erholung trotzdem verpasst. Das Kerngeschäft geriet dabei nie grundsätzlich in Frage.
$CCO (-3,01 %) folgt einer ähnlichen Logik, mit einer wichtigen Überlagerung. Der Uran-Zyklus ist langsamer und politisch getrieben. Nach Fukushima hat der Markt jahrelang gebraucht, um die strukturelle Nachfrage von der politischen Stimmung zu trennen. Reaktoren wurden abgeschaltet, der Uranpreis kollabierte. Für viele sah das wie ein strukturelles Problem aus. War es nicht. Der Strombedarf blieb. Kernkraft als Technologie blieb. Was sich änderte, war die Wahrnehmung. Als die sich drehte, drehte auch der Zyklus. Wer den Unterschied verstand, hat die Neubewertung mitgenommen.
$CVS (+1,36 %) ist das Gegenbeispiel. Das Apothekenmodell steht seit Jahren unter Druck: Pharmacy Benefit Manager drücken die Margen, der stationäre Einzelhandel verliert Frequenz, das Kerngeschäft schrumpft. CVS operiert noch immer in großem Maßstab und liefert Umsätze. Aber der Markt preist zunehmend strukturelle Margenerosion und regulatorische Risiken ein, und das aus gutem Grund. Trotzdem wurde CVS jahrelang als günstiger Dividendenwert gehandelt. Die hohe Dividendenrendite galt als Kaufargument. Dabei ist eine ungewöhnlich hohe Dividendenrendite oft eher ein Hinweis darauf, dass der Markt an der Nachhaltigkeit der Ausschüttung zweifelt. Bei CVS hat sich das bestätigt. Wer auf die zyklische Erholung wartete, wartete auf etwas, das strukturell nicht kommen konnte.
$VOW (+0,06 %) ist der schwierigere Fall, und deshalb lehrreich auf andere Weise. Der Marktanteilsverlust in China an BYD und andere lokale Hersteller hat einen strukturellen Kern: chinesische Anbieter sind inzwischen in Qualität und Preis konkurrenzfähig, das ist kein temporäres Phänomen. Gleichzeitig überlagert zyklischer Nachfragerückgang im Premiumsegment die Strukturfrage kurzfristig. Beides lässt sich nicht sauber trennen. Das macht VW zum Mischfall: struktureller Kern, zyklisches Overlay. Das ist kein Versagen der Analyse, das ist die Realität vieler Unternehmen in Transformationsphasen. Und genau deshalb muss ich bei einem solchen Fall zumindest wissen, welchen Anteil ich dem Zyklus zuschreibe und welchen dem Strukturwandel. Ohne diese Trennung ist eine Positionsgröße kaum zu rechtfertigen.
Was ich vermeide: einen Zykliker mit Strukturargumenten zu halten, wenn der Zyklus sich gerade erholt. Das ist die häufigste Form der Selbsttäuschung. Die Story klingt überzeugend, der Kurs steigt, und irgendwann merkt man, dass man nicht die Branche verstanden hat, sondern nur den Bullenmarkt mitgemacht hat.
Das Instrument, das mir bei dieser Unterscheidung am meisten hilft, sind Gewinnrevisionen. Darum geht es im nächsten Artikel.


Belgien möchte die Kernenergie verstaatlichen
Sehr viel grün heute unter anderem geht es auch im Uran-Sektor wieder steil nach oben. Heute gab es News bezüglich der Kernkraft in Belgien, scheinbar steckt die Regierung in intensiven Verhandlung mit dem Betreiber die 7 Blöcke auf 2 Standorten zu verstaatlichen. Der Rückbau der Reaktoren wurde so wie es aussieht erstmal gestoppt ☢️ Scheinbar möchte jeder die Situation der deutschen Leitkultur vermeiden.
$CCO (-3,01 %)
$UEC (-2,06 %)
$YCA (-2,94 %)
$NXE (-4,5 %)
$KZAP
https://www.bbc.com/news/articles/c4g05jg87wko

Podcast episode 138 "Buy High. Sell Low." Iran war winners and losers, buy the dip, oil.
Subscribe to the podcast so that there will soon be peace.
00:00:00 Oil and government bonds
00:37:50 Liberty Energy $LBYE
00:48:30 Cheniere Energy $LNG (-0,94 %)
00:56:35 Kinder Morgan $KMI (+0,38 %)
01:00:52 Iran war losers / Buy The Dip
01:19:20 Bitcoin
Spotify
https://open.spotify.com/episode/7jouQHLiEbfg5QGyZOdZWJ?si=Du2whTFIR7WOE8AFD1RICA
YouTube
Apple Podcast
$TKA (-1,66 %)
$SZG (-7,26 %)
$SZGPY (-4,52 %)
$HLAG (+1,19 %)
$VNA (-0,57 %)
$CCL
$AAL (+1,07 %)
$SMSD (-6,26 %)
$005930
$CONTININS
$TUI1 (-0,46 %)
$IFX (-6,93 %)
$MC (+0,54 %)
$BA (+0,24 %)
$2330
$CCO (-3,01 %)
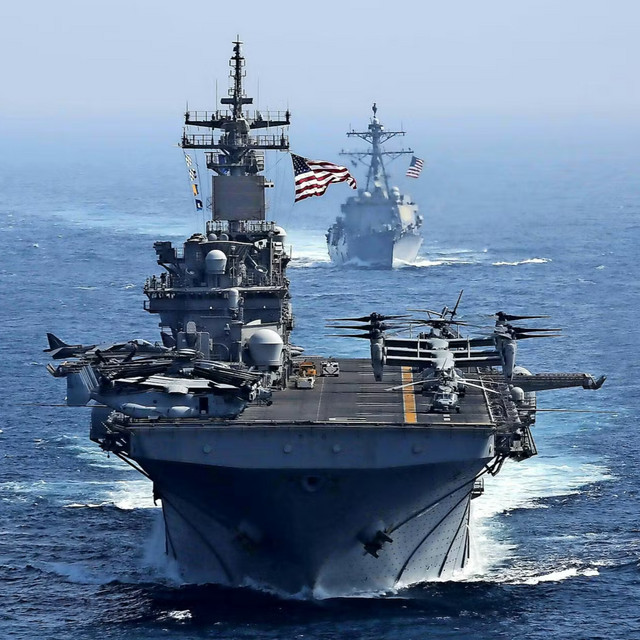
The three sources of equity returns - Why it makes a difference where a return comes from
Reading time: about 4–5 minutes
Anyone who buys a stock and later sells it at a profit has generated a return. That’s the simple version. The more interesting question is: Where did this return actually come from?
Depending on the source of a return, it varies in terms of reliability, repeatability, and risk. If you don’t distinguish between these sources, you’ll make poorer decisions about when to hold a position and when not to.
Essentially, there are three sources of stock returns.
The first is earnings growth. The company is earning more than before. Revenue is rising, margins are improving, and profits are growing. The stock price follows suit because a company that earns more is simply worth more.
The second is multiple expansion. The company isn’t necessarily earning more, but the market is paying a higher price for the same profit. The price-to-earnings ratio rises. The valuation expands.
The third is capital return. The company distributes profits or repurchases its own shares. Dividends and buybacks increase the value per share without requiring operational growth.
In practice, these three sources rarely operate in isolation. They overlap, reinforce one another, or work against each other. Nevertheless, it is worth distinguishing between them.
In the long term, earnings growth is the most robust of the three sources. A company that increases its earnings over many years is highly likely to see its stock price rise as well. Markets may react irrationally in the short term. Over five, ten, or fifteen years, however, stock prices almost always follow earnings growth.
$GOOGL (+3,32 %) (Alphabet) is a good example. Anyone who bought the stock ten years ago achieved a return of well over 500 percent. The vast majority of that return did not come from changes in valuation. It came because Alphabet systematically earned more. Revenue has multiplied, operational levers have improved margins, and the cloud segment has grown from zero to billions.
Earnings growth is sustainable because it’s based on operational realities, not market psychology. At the same time, it’s harder to achieve. Not every company grows. And even good companies don’t grow at high rates forever.
Multiple expansion is the source that can generate the highest returns in the short term. But it is also the most unreliable.
Here’s a simple example. A company earns ten euros per share. The market values it at a P/E ratio of 15, and the share price is 150 euros. If the P/E ratio rises to 22 without any change in earnings, the share price suddenly stands at 220 euros. That’s a return of nearly 47 percent, even though the company hasn’t earned a single additional euro from operations.
Periods of falling interest rates favor higher multiples. Improved sentiment, new narratives, or capital inflows into an industry can drive valuations higher. Those who are well-positioned can achieve rapid and impressive gains.
The problem is reversibility. What has been created by valuation expansion can disappear just as quickly through valuation contraction.
$CCO (-3,01 %) (Cameco) and other uranium producers did not just benefit from rising spot prices between 2020 and 2024. A significant portion of their share price gains resulted from multiple expansion. The market began to take the structural supply deficit seriously and paid higher valuations for it. Those who positioned themselves early benefited from both sources simultaneously: rising profits and rising multiples. Those who entered late were already paying for the narrative.
In my portfolio, this is one of the lessons I’ve internalized from the uranium sector. The structural arguments remain intact. But returns driven by multiple expansion should be evaluated differently from returns driven by operational improvements. The first source can reverse quickly. The second is more fundamentally anchored.
The third source is most often underestimated, especially by investors focused on growth.
When a company repurchases its own shares, the number of outstanding shares decreases. This increases earnings per share, even if total earnings remain constant. Over many years, this effect can be significant.
$HON (+0,72 %) (Honeywell) is an example. The company is growing at a moderate pace. But over the past few years, Honeywell has systematically returned capital to shareholders through dividends and buybacks. Part of the return on this position did not come from spectacular growth, but from this mechanism: a high-quality company that uses its free cash flow in a disciplined manner.
If a company can find no better use for its capital than repurchasing its own shares, that is often a rational decision—provided the stock is not massively overvalued. A buyback at an inflated valuation destroys value; at a fair or undervalued price, it creates it.
The most attractive investments are often those where all three sources are at work simultaneously. A company that is growing, fairly valued, and also returning capital offers a structurally favorable opportunity profile. $GOOGL (+3,32 %) Alphabet is another good example. Growth has been the dominant source for many years. In recent years, Alphabet has also begun repurchasing significant amounts of its own shares. The return of capital has become a complementary source, without replacing the growth narrative.
The reverse pattern is just as important. If a return has stemmed almost exclusively from multiple expansion, the position is more vulnerable to shifts in sentiment, even if nothing has changed operationally.
That’s why I regularly ask myself this question regarding my positions: Where did the return to date come from? And what source will drive future returns?
In hindsight, stock returns often look the same. A stock rises by 80 percent. But that 80 percent can come from completely different sources. From earnings growth, which is likely to continue. From valuation expansion, which can reverse at any time. Or from capital returns that are structurally embedded. Earnings growth unfolds its value over time. Valuation expansion unfolds it quickly and takes it away just as quickly.
Capital returns work quietly but reliably in the background.
The next post will examine the second of these sources in detail. Valuation expansion is the phenomenon that generates the highest returns in the short term and is, at the same time, the least understood. What really drives changes in valuations? And when do investors pay for it without even realizing it?

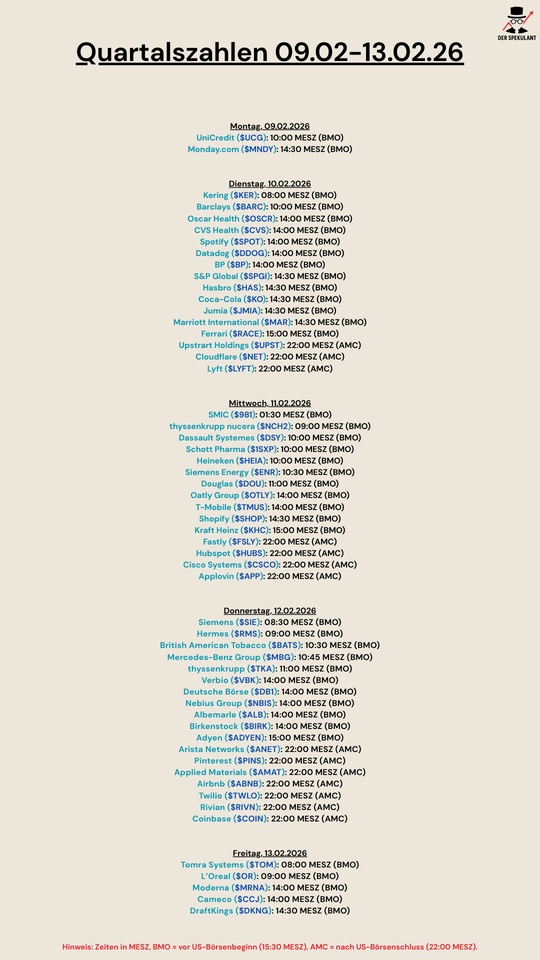
Quarterly figures 09.02-13.02.26
$UCG (-0,88 %)
$MNDY (+10,99 %)
$KER (+0,23 %)
$BARC (-2,99 %)
$OSCR (+3,62 %)
$CVS (+1,36 %)
$SPOT (+5,95 %)
$DDOG (+3,86 %)
$BP. (-0,11 %)
$SPGI (+2,49 %)
$HAS (+0,51 %)
$KO (+1,58 %)
$JMIA (-1,25 %)
$MAR (+1,7 %)
$RACE (-0,71 %)
$UPST (+2,4 %)
$NET (+8,18 %)
$LYFT (+3,79 %)
$981
$NCH2 (-0,69 %)
$DSY (+4,94 %)
$1SXP (-2,28 %)
$HEIA (+2,6 %)
$ENR (-7,27 %)
$DOU (+0,2 %)
$OTLY (+2,97 %)
$TMUS (+0,88 %)
$SHOP (+4,04 %)
$KHC (-1,03 %)
$FSLY (+8,11 %)
$HUBS (+10,23 %)
$CSCO (-1,31 %)
$APP (+3,54 %)
$SIE (-0,66 %)
$RMS (+1,16 %)
$BATS (+3,7 %)
$MBG (-0,18 %)
$TKA (-1,66 %)
$VBK (-0,39 %)
$DB1 (+1,85 %)
$NBIS (-4,55 %)
$ALB (-1,66 %)
$BIRK (-0,93 %)
$ADYEN (+2,41 %)
$ANET (-4,85 %)
$PINS (+4,29 %)
$AMAT (-6,24 %)
$ABNB (+0,72 %)
$TWLO (+3,08 %)
$RIVN (-0,79 %)
$COIN (+9,38 %)
$TOM (-1,86 %)
$OR (+1,29 %)
$MRNA (+1,99 %)
$CCO (-3,01 %)
$DKNG (+0,7 %)


Infrastructure and waste disposal: The profiteers of the nuclear boom
Dear Community,
Where the hunger for energy is being met by nuclear power and the new generation of Small Modular Reactors (SMRs), a massive growth market for downstream services is inevitably emerging.
This applies above all to nuclear waste disposal, the professional dismantling of old plants and the recycling of fuels and water.
Since there is currently no pure "nuclear waste ETF" (at least that I am aware of), we investors must focus on specialized individual stocks that are global leaders in the disposal of uranium and contaminated components (including water).
1. the operational heavyweights for dismantling and disposal
- Veolia ($VIE (+0,05 %)
): Although Veolia is primarily perceived as a global environmental services provider, it also operates a nuclear power plant with Veolia Nuclear Solutions a highly specialized division. As the global market leader in robot-assisted cleaning and the dismantling of highly radioactive sites (such as Fukushima), they are indispensable. They offer technologies for the vitrification of waste ("vitrification", the transformation of liquid or solid nuclear waste into a solid glass body) and for water treatment in contaminated areas. Veolia thus bridges the gap to the traditional water business and covers two key areas in its portfolio at the same time.
- Fortum ($FORTUM (-2,78 %)
): The Finnish energy group is a hidden champion of nuclear aftercare. In addition to operating power plants, Fortum offers specialized services for the purification of radioactive liquids (NUKEM technology) and final disposal. They are a key player in European waste management standards.
- Jacobs Solutions ($J (+1,63 %)
): The US engineering services giant manages major government nuclear sites such as Sellafield (UK) and Hanford (USA). Its focus is on program management for the long-term storage of fuel elements. The SMR connection is particularly exciting: Jacobs is already advising numerous developers on planning the entire life cycle, including disposal.
- Perma-Fix Environmental Services ($PESI (-2,19 %)
): Perma-Fix is regarded as one of the few genuine "pure plays". The company operates its own facilities for the treatment of nuclear and mixed waste. Its core competence lies in massively reducing the volume of nuclear waste before it is transferred to a final repository.
2 The fuel cycle: Cameco and Westinghouse
Cameco ($CCO (-3,01 %)
) is primarily known as a uranium producer, but together with Brookfield Asset Management holds a majority stake in Westinghouse Electric Corporation (electrical engineering). The company thus covers the entire cycle:
- Operations: Cameco produces uranium concentrate (yellowcake), while Westinghouse supplies the reactor technology and maintenance.
- Disposal expertise: Through Westinghouse, Cameco covers the lucrative "back end". This includes the decontamination of process water as well as the conditioning and volume reduction of of radioactive waste.
- Dismantling service: As a technological market leader, the team offers solutions for the dismantling (D&D) of old plants, using specialized filter systems to clean contaminated liquids.
- Market model: Sales are stable through long-term supply contracts. The service division makes the company less dependent on fluctuations in the uranium price, as maintenance and waste treatment are permanent tasks required by law.
Energy Fuels ($UUUU (-4,42 %)
): This company occupies a strategic niche. In its White Mesa Mill they recover uranium from residual materials and waste from other industries. This positions Energy Fuels as a pioneer in "uranium recycling", which reduces dependence on primary extraction and makes waste streams economically viable.
3. specialty materials and water technology
In the nuclear industry, water is not only a coolant, but often also a transport medium for contaminants. This is where the technology leaders come into play:
- Xylem Inc. ($XYL (+0,95 %)
): As a pure water technology company, Xylem supplies the heavy-duty pumping and filtration systems that are essential for the cooling circuits of modern reactors and subsequent wastewater treatment.
- Danaher Corporation ($DHR (+2,03 %)
): Via the divested environmental division Veralto Danaher offers high-precision analytical instruments for monitoring water quality - a critical component for detecting leaks and contamination in real time.
- Umicore ($UMI (-4,55 %)
): The materials technology group is pursuing a "closed-loop" model. In the long term, its expertise in recovering metals from complex industrial waste could play a role in the recycling of power plant components.
The new generation of reactors: SMR specialists in detail
When it comes to direct energy supply for the AI sector, two companies are in the spotlight:
- NuScale Power ($SMR
): The conservative pioneer relies on proven light water reactor technology (VOYGR™). As NuScale traditionally relies on water, the need for water technology (pumps, filters from suppliers such as Xylem) is extremely high. This makes NuScale an ideal partner for traditional infrastructure investors.
- Oklo Inc.$OKLO
): The radical innovator (supported by Sam Altman) develops "fast reactors". The key feature: these can be fueled with recycled nuclear waste (HALEU). Oklo transforms a disposal problem directly into an energy source and thus addresses the waste problem at its root.
Strategic conclusion
If you want to bridge the gap between water cooling and waste disposal, you will find in Veolia the most stable connection.
Jacobs Solutions and Perma-Fix are the most direct options for physical dismantling.
Energy Fuels offers an exciting bet on the recycling of uranium residues, while Xylem and Danaher provide the indispensable technological basis for water management in a nuclear renaissance.
However, the decisive strategic winner of the current nuclear renaissance could be the team of Cameco & Westinghouse ($CCO) (-3,01 %) could be:
By merging uranium mining and reactor technology, they have created a vertically integrated business model. They not only profit from the sale of the fuel, but also control the entire downstream value chain via Westinghouse - from the purification of the process water to the final storage preparation.
As a result, Cameco has risen from a pure mining player to an indispensable infrastructure partner for the energy and AI economy.
In addition, the 80 billion dollar agreement with the US government agreed at the end of 2025 is likely to have cemented Cameco's long-term market leadership in the West (https://de.marketscreener.com/boerse-nachrichten/westinghouse-electric-cameco-und-brookfield-starten-80-milliarden-dollar-offensive-fuer-atomkraft-in-ce7d5ddcd88cf127).
Risk analysis
The nuclear renaissance is more real today than it was ten years ago, but as investors we need to look at two sides of the coin:
Opportunities through regulatory certainty: Waste disposal and dismantling are not "optional services", but permanent tasks prescribed by law. Financing is often already secured by existing provisions of the groups, which makes the service providers (Veolia, Jacobs, Perma-Fix) crisis-resistant.
Risks: Political risks remain. A change of government can delay approval processes for final storage facilities. In addition, the sector is highly emotional; ESG ratings often (still?!) determine how much capital actually flows into the shares.
Could water and waste management technology end up being the safer investment than the actual SMR builders, because it makes money from every technological outcome? How do you see the risk/reward ratio?
Best regards and thank you very much for the positive response and all the feedback on my previous and very first post ✌🏼
Anderlé

Personally, I am currently still playing the hype cycle around the manufacturers, as I expect a greater return here in the short term. In the long term, however, the music is at least as strong here.
Titres populaires
Meilleurs créateurs cette semaine