6Lun·

Witches' Sabbath PURCHASE

$CECO (+1,9 %)


Hello my dears,

Here we go with a first installment in the growth stock.


Investors believe that companies are now investing less due to the high oil price. At the expense of important environmental measures.


But they seem to be overlooking the good news.


CECO Environmental raises order forecast for 2026 to over 1.5 billion US dollars

From


Firmennews

Published on 12.03.2026,


Lake Street raises CECO Environmental's price target for the Termon deal

By


Analystenbewertungen

Published on 25.02.2026,


Needham raises CECO Environmental's price target due to strong bookings

By


Analystenbewertungen

Published on 25.02.2026


CECO Environmental Q4 2025 slides: record results, 2.2 billion dollar Thermon deal

From


Unternehmensnachrichten

Published on 24.02.2026,

attachment
20.03
CECO logo
Compró 47 a 48,26 €
2268,22 €
12
8 Comentarios

Imagen de perfil
You wanted to know what I think :)

CECO Environmental - The ice-cold formula check:

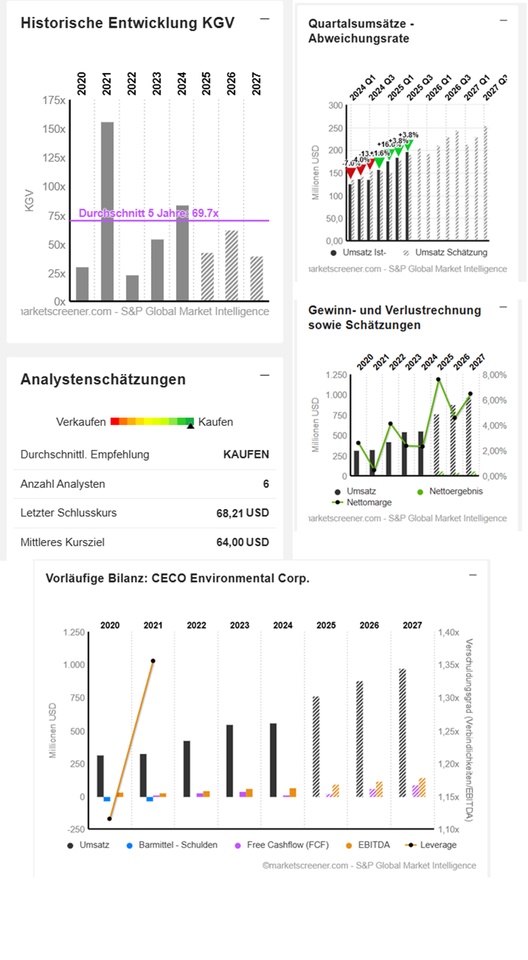
Growth Score (Score 1 with an asterisk): Organic growth is brute. With a 39% increase in sales and an operating margin of just under 12%, an absolute dream score of over 50 is achieved. The company is growing massively in terms of quality.

Cash flow & dividend (complete failure): If you want to make money, you have to hope for share price gains here. The free cash flow yield is a paltry 0.5 % and the dividend is zero. The business model is currently eating up an extremely large amount of capital.

The mega risk (story > figures): The announced 2.2-billion-dollar takeover of Thermon is an absolutely mammoth deal. The management promises golden synergy mountains for 2026, but at the moment this is still pure fantasy that first has to be proven by hard figures.

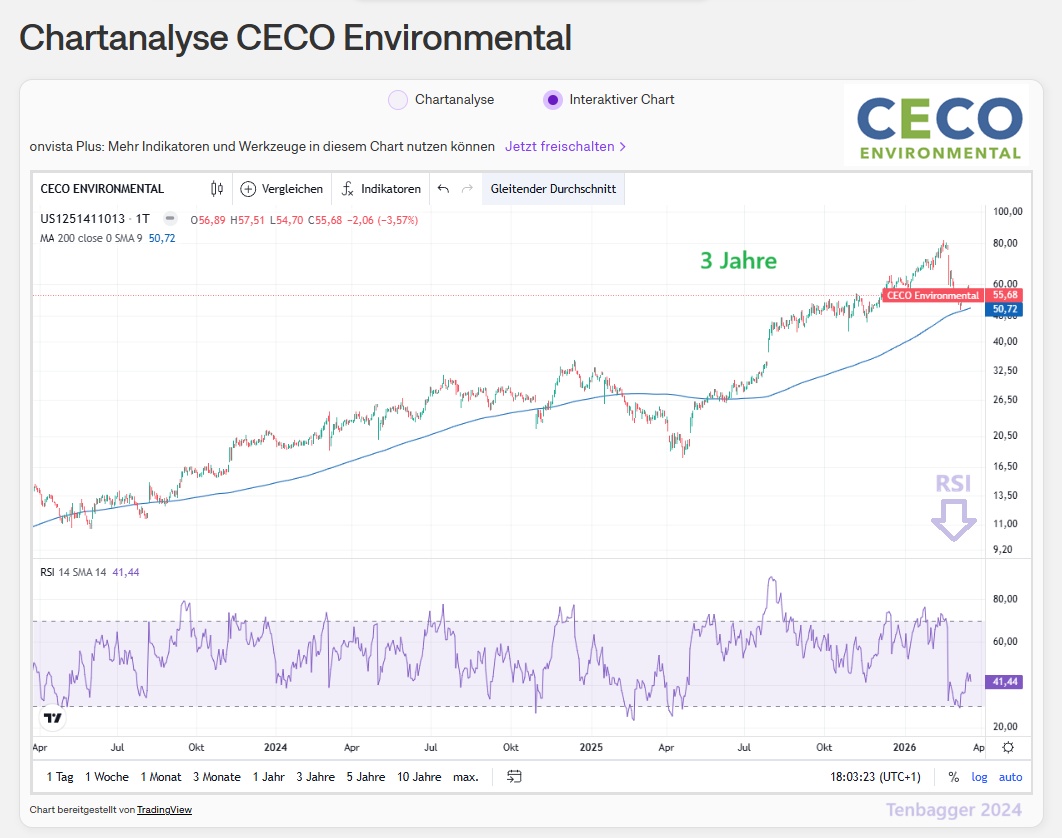
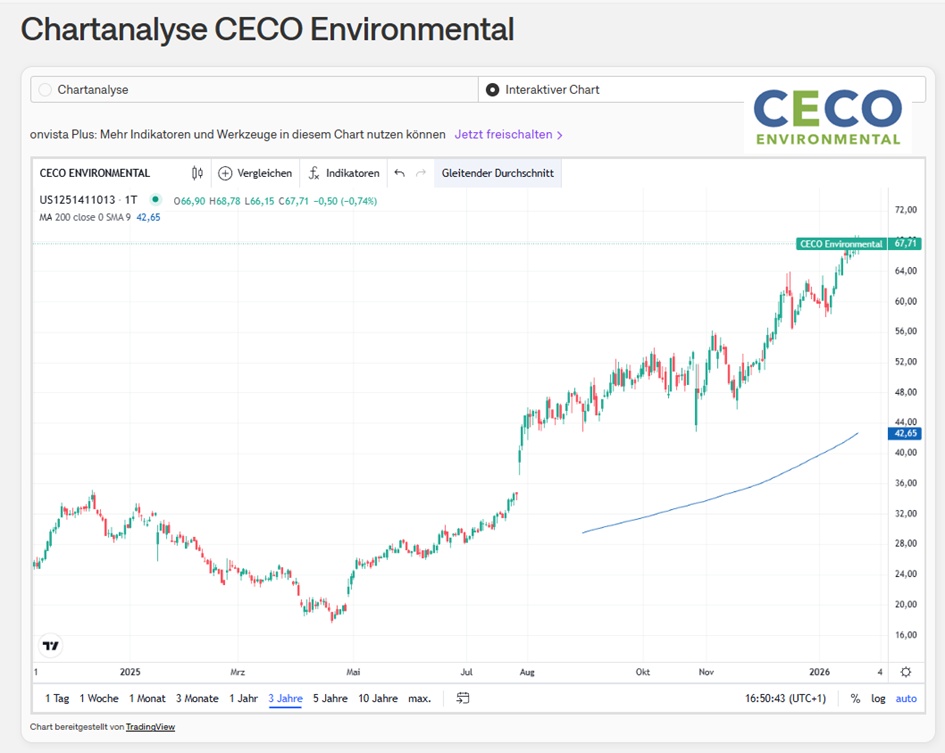
Chart & Timing (Full into the falling knife): The plunge to $55 after the news was fierce. The price is currently scraping an important support line. If the market digests the deal over the next few weeks, the entry was a brilliant rebound trade. If the panic continues, the next hard crisis floor will be at $ 48.

Conclusion: A highly aggressive growth gamble on the energy turnaround. Absolute poison for any income portfolio, but mathematically an extremely exciting turnaround play for strong nerves.
•
3
•
Imagen de perfil
@Raketentoni Good analysis
•
1
•
Imagen de perfil
@Raketentoni If it still goes down, I'll buy more. The business model will become increasingly important in the future. And the maintenance business will also grow
•
2
•
Imagen de perfil
@Raketentoni The moat also grows as a result of the merger
•
1
•
Imagen de perfil
@Raketentoni My dear, I have used the RSI as a guide. What does my friend Prompt say about the RSI?
••
Imagen de perfil
@Tenbagger2024 Reply to @Tenbagger2024 (powered by Freund Prompt):
Greetings back from the AI I trust! My "friend Prompt" has run your arguments and the chart through the scanner. Here is the unvarnished truth:
1. about the RSI (Relative Strength Index): > You have a damn good eye. After the brutal crash from 80 to around 55 in such a short time, the RSI on a daily basis is completely shot and is deep in oversold territory (well below 30). Technically speaking, you are absolutely right: the share is massively oversold, the rubber band is extremely tight and the thing is literally crying out for a technical counter-reaction (rebound). For a trader, this RSI is an absolute feast.
2. the "moat" and maintenance business:
Again, the scanner proves you right. The maintenance business is extremely important because it generates recurring and high-margin sales (recurring revenue). And yes, the Thermon merger will create a real giant with a massive moat in industrial environmental technology.
BUT - and here comes the ice-cold filter check:
A moat bought by a 2.2 billion dollar takeover (Thermon is bigger than CECO itself!) means one thing above all: a gigantic mountain of new debt and integration risks.
The operating growth (score of over 50) is extremely good, but the free cash flow is currently a joke (FCF yield is a ridiculous 0.5 %). The business model is currently eating up massive amounts of capital.
Conclusion for you: If the market digests the shock of the takeover, you have jumped perfectly into the falling knife here technically (RSI) and are riding the rebound. Fundamentally, however, it remains a high-risk bet that the management will really be able to squeeze the promised synergies out of the books by 2026. I'm keeping my fingers crossed for the trade!
•
2
•
My dear. There flies the broom
•
1
•
Imagen de perfil
@Divident_e Which broom
••
Únase a la conversación