
Novo Nordisk significantly outperformed analysts' expectations in the third quarter of 2026 and raised its full-year forecast for the third time this year. Revenue rose to 79.2 billion DKK (+6% in DKK, +4% at constant exchange rates), while adjusted operating profit jumped 34% to 31.7 billion DKK. The biggest source of optimism is the new Wegovy pill, which already contributed DKK 5.39 billion in revenue during the quarter. The reported earnings were weighed down by impairment charges of DKK 8.7 billion. The stock reacted with a gain of about 3% to DKK 278.45, but remains about 29% below its 52-week high of DKK 391.30. From a technical analysis perspective, Novo Nordisk remains in a bear market: Only a breakout above 308 DKK would provide an initial positive signal.
Key Points
- Q3 2026 revenue: DKK 79.2 billion, adjusted operating profit: DKK 31.7 billion (+34%)
- Wegovy pill: DKK 5.39 billion in revenue in the third quarter
- 2026 forecast raised to −2% to +2% at constant exchange rates (previously 0% to −6%)
- Impairment charges of DKK 8.7 billion reduced reported EBIT to DKK 23.0 billion (−3%)
- Analysts: Average price target around 298 DKK; range from major firms: 225 to 332 DKK
- Chart levels: Signal above 308 DKK, support at 220–225 DKK, critical level at 200 DKK
What are the current key metrics for Novo Nordisk stock?
On November 4, 2026, Novo Nordisk’s stock price stood at 278.45 DKK on the Copenhagen Stock Exchange (NOVO B), up about 3% from the previous day. With a P/E ratio of around 10 and a dividend yield of about 4.2%, the stock is undervalued—but it is still about 29% below its 52-week high of 391.30 DKK.
- Price (Copenhagen: NOVO B): 278.45 DKK (approx. +3%)
- 52-week high: 391.30 DKK
- 52-week low: 214.05 DKK
- Revenue Q3 2026: 79.2 billion DKK (+6% in DKK / +4% at constant exchange rates)
- Adjusted operating profit for Q3: 31.7 billion DKK (+34% in DKK / +27% at constant exchange rates)
- Reported Q3 operating profit: DKK 23.0 billion (−3%)
- Impairments in Q3: DKK 8.7 billion
- Q3 revenue from the Wegovy pill: DKK 5.39 billion
- 2026 Outlook (Revenue and Adjusted EBIT, constant exchange rates): −2% to +2% (previously 0% to −6%)
- P/E ratio (trailing): approx. 10
- Dividend for 2025: 11.70 DKK (yield approx. 4.2%)
- Average analyst price target: approx. 298 DKK
- Next Earnings Report (Fiscal Year 2026): February 3, 2027
What news is currently driving Novo Nordisk stock?
The most important news regarding Novo Nordisk stock right now is the strong third-quarter results and the annual forecast, which has been raised once again. According to Reuters, revenue and adjusted operating profit were well above analysts’ estimates, driven by the Wegovy pill. On the flip side are significant impairment charges and a group of analysts who are largely maintaining a “hold” rating. Do you remember how long it Bayer Aktie took to rebuild confidence after setbacks? Novo Nordisk is currently waging this very tough battle for investor confidence in real time.
- November 4, 2026 – Q3 well above expectations: Revenue of 79.2 billion DKK (consensus per Reuters: 73.2 billion DKK), adjusted operating profit of 31.7 billion DKK (consensus: 28.4 billion DKK). Very bullish
- November 4, 2026 – Forecast raised for the third time: adjusted revenue and adjusted operating profit for 2026 now projected at −2% to +2% at constant exchange rates, up from 0% to −6%. Bullish
- November 4, 2026 – Wegovy pill takes off: DKK 5.39 billion in revenue in the third quarter. Very bullish
- November 4, 2026 – Impairment charges of DKK 8.7 billion: DKK 4.6 billion related to ziltivekimab, DKK 4.1 billion due to the downsizing of the production network; reported EBIT falls to DKK 23.0 billion (−3%). Bearish
- November 4, 2026 – Jefferies maintains Hold rating, price target of 275 DKK. Neutral
- October 28, 2026 – JPMorgan reaffirms Neutral with a price target of 275 DKK. Neutral
- Oct. 7, 2026 – Deutsche Bank Research lowers the price target from 245 to 225 DKK, rating: Sell. Bearish
What does Novo Nordisk’s management say about the Q3 results?
Management, led by CEO Maziar Mike Doustdar, cites a stronger-than-expected third quarter and is therefore raising its 2026 forecast for the third time this year. Doustdar emphasizes that both the U.S. business and international operations have grown—“Growth was led by our obesity portfolio,” says the CEO.
What performed particularly well: The star of the quarter is the Wegovy pill, with revenue of 5.39 billion DKK. According to the company, it continues to gain patients in the U.S. and is now also being launched internationally, including in the U.K. and Germany. Driven by increased sales of GLP-1 medications, adjusted operating profit rose 34% to DKK 31.7 billion.
The catch: Reported operating profit fell by 3% to DKK 23.0 billion. This is due to non-cash impairment charges of DKK 8.7 billion—DKK 4.6 billion related to the drug candidate ziltivekimab and DKK 4.1 billion for the downsizing of the production network. In addition, the comparison base is favorable: The same quarter last year was burdened by high restructuring costs, which is why the adjusted profit increase is so strong. And at constant exchange rates, revenue grew by only 4%.
The outlook: For 2026, Novo Nordisk now expects adjusted revenue and adjusted operating profit to range from −2% to +2% at constant exchange rates (previously 0% to −6%). The upward revision is attributed to higher expectations for GLP-1 medications. As the next major step, management is preparing for the U.S. launch of the weight-loss drug CagriSema in early 2027—subject to approval.
What does Novo Nordisk do—and how does the company make its money?
Novo Nordisk generates revenue from medications for diabetes and obesity and, with its GLP-1 agents—including Ozempic and Wegovy—is one of the world’s leading providers in this field. The Danish pharmaceutical company, headquartered in Bagsværd, has been led by CEO Maziar Mike Doustdar since 2025.
Diabetes Care: The traditional core business includes insulins as well as the GLP-1 medications Ozempic (injection) and Rybelsus (tablet). This segment continues to generate a large portion of the company’s revenue, but competition—primarily from Eli Lilly—and price pressure in the U.S. have increased significantly.
Obesity Care: The growth segment centered on Wegovy, which is now available as both an injection and a tablet. According to Novo Nordisk, growth in the third quarter was driven by the obesity portfolio.
Rare Diseases: Medications for rare diseases such as hemophilia and growth disorders—a smaller but stable pillar of the business.
Regions: Novo Nordisk reports on two regions: U.S. Operations and International Operations. According to the company, both regions grew in the third quarter of 2026—an important sign following a difficult previous year.
The Wegovy pill as a new growth driver: With third-quarter revenue of DKK 5.39 billion, the tablet version of Wegovy is already a significant revenue driver. According to Reuters, the figure was well above analysts’ expectations, placing the pill at the center of the battle with Eli Lilly for the weight-loss drug market. For investors, it is the main reason why Novo Nordisk has raised its 2026 forecast for the third time—and, for the first time this year, considers revenue growth a possibility again.
Fundamental Analysis: Is the Novo Nordisk Stock Undervalued Following the Forecast Upgrade?
Based on the raw numbers, Novo Nordisk stock is clearly undervalued with a P/E ratio of around 10 and a dividend yield of about 4.2%—provided that business stabilizes as indicated in the third quarter. At this valuation, the market is barely pricing in any growth, even though Novo Nordisk continues to operate at high profitability.
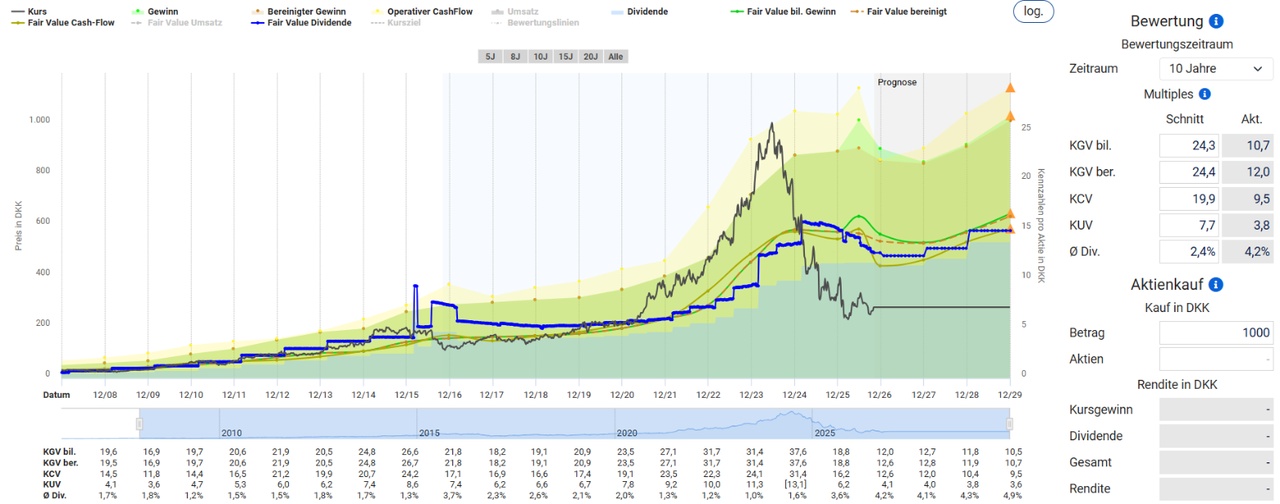
Margin Performance: In the third quarter, Novo Nordisk reported adjusted operating profit of DKK 31.7 billion on revenue of DKK 79.2 billion—corresponding to an adjusted operating margin of around 40%. The prior-year quarter was weighed down by high restructuring costs, which is why the 34% increase (27% at constant exchange rates) is so substantial.
Impairment charges and reported earnings: On a reported basis, operating profit fell by 3% to DKK 23.0 billion, bringing the reported margin to approximately 29%. This was due to impairment charges of DKK 8.7 billion: DKK 4.6 billion related to the drug candidate ziltivekimab, and DKK 4.1 billion to the downsizing of the production network. This is a clear setback for the pipeline but does not impact ongoing operations.
Comparison with Eli Lilly: The major rival is growing significantly faster in a shrinking market: Eli Lilly increased revenue by 39% in the third quarter of 2026 and raised its full-year forecast to $91–92 billion, driven by Mounjaro and Zepbound. Novo Nordisk grew by only 4% at constant exchange rates in the same quarter. It is precisely this growth gap that explains why Lilly trades at a significant valuation premium on the stock market, while Novo Nordisk is available at a P/E ratio typical of a value stock. However, a low P/E ratio alone is not a buy signal—the Mercedes Aktie has long shown how persistent a value trap can be when the market doesn’t believe in growth.
Dividend: For fiscal year 2025, Novo Nordisk paid a total of 11.70 DKK per share (interim dividend of 3.75 DKK plus final dividend of 7.95 DKK). An interim dividend of 3.75 DKK per share was already paid in August 2026. Based on the current share price, this represents a yield of approximately 4.2%.
Novo Nordisk Stock Price Targets and Forecast for 2026
Analysts’ average price target for Novo Nordisk stock is around 298 DKK, which is only about 7% above the current price of 278.45 DKK. The range of estimates from major brokerages extends from 225 DKK (Deutsche Bank, Sell) to 332 DKK (UBS, Neutral). The outlook based on the chart is clear: As long as the stock trades below 308 DKK, the bear market remains intact—only above that level does room open up toward 395 and 513 DKK.
Just how quickly even record-breaking numbers can fizzle out on the stock market was recently Palantir Aktie . With Novo Nordisk, it’s the opposite: The earnings are impressive, but the chart has yet to prove that buyers are back.
Key price levels:
- 52-week high: 391.30 DKK
- Current price: 278.45 DKK (Nov. 4, 2026; weekly high: 287.80 DKK)
- First resistance: Downward trend line at around 290–300 DKK and signal level of 308 DKK
- Second resistance: around 395 DKK
- Target in the event of a trend reversal: 513 DKK
- Support zone: 220–225 DKK (52-week low at 214.05 DKK)
- Critical downside level: 200 DKK
Analysts’ price targets:
- Average price target: approx. 298 DKK
- UBS: Neutral, 332 DKK (Oct. 15, 2026)
- Berenberg: Hold, 305 DKK (September 22, 2026)
- Jefferies: Hold, 275 DKK (November 4, 2026)
- JPMorgan: Neutral, 275 DKK (October 28, 2026)
- Morgan Stanley: Underweight, 250 DKK (September 11, 2026)
- Deutsche Bank Research: Sell, 225 DKK (October 7, 2026)
Chart Analysis:
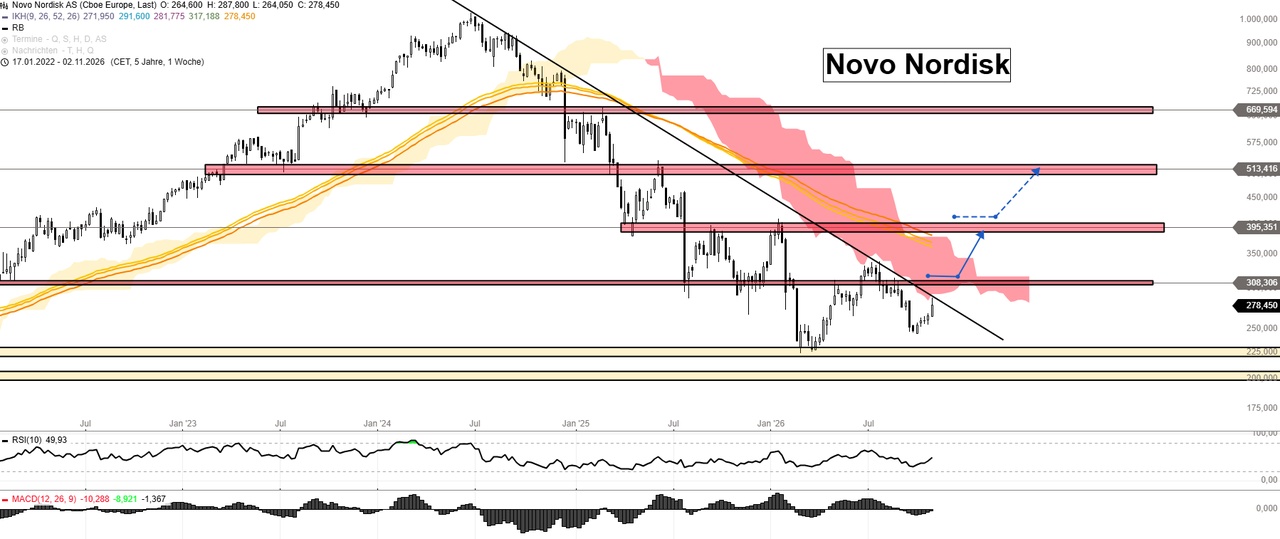
Novo Nordisk stock continues to trade in a firm bear market. Since its record high in 2024, a clear downward trend line has been running through the weekly chart; the price is currently testing this line from below in the range of approximately 290 to 300 DKK, and the Ichimoku cloud also remains above the price. For several months now, the stock has been attempting to defend the key range of around 220 to 225 DKK and attract new buyers. So far, this effort has been only tentative—the RSI(10) is right in the neutral zone at around 50.
A breakout above 308 DKK would be an initial positive signal. This could lead to moves initially toward the intermediate level around 395 DKK and, subsequently, up to 513 DKK. However, should the price fall below the 200 DKK mark on a sustained basis, the bear market will continue, resulting in drastic sell-offs. For anyone looking to take a long position, this means waiting until the first positive signal above 308 DKK appears.
Conclusion: Novo Nordisk Stock—Trend Reversal or Another Bear Trap?
Based on the Q3 results, Novo Nordisk stock is fundamentally undervalued, but from a technical perspective, it’s not yet a buy: the first positive signal won’t appear until the price rises above 308 DKK, while a drop below 200 DKK could trigger another sell-off. The third quarter clearly exceeded expectations; the Wegovy pill is already contributing DKK 5.39 billion in revenue, and the forecast for 2026 has been raised for the third time. At the same time, impairment charges of DKK 8.7 billion indicate that not everything in the pipeline is going according to plan. Looking ahead to 2027, Novo Nordisk is preparing for the U.S. launch of the weight-loss drug CagriSema, subject to approval, according to its own announcement.
With a P/E ratio of around 10 and a dividend yield of about 4.2%, the stock is attractively valued for long-term investors. However, the chart tells a different story: Novo Nordisk is in the midst of a firm bear market and has been only tentatively defending the 220 DKK level for months. My assessment is therefore: wait and see. Only a breakout above 308 DKK would be the first positive signal, with potential gains up to 513 DKK. If, on the other hand, the stock falls sustainably below 200 DKK, drastic sell-offs loom.
The fact that a strong quarter can literally send a stock soaring has recently been SAP Aktie —Novo Nordisk has yet to make that breakthrough, and the 308 DKK mark will determine the next chapter.
✅ Opportunities
- Q3 clearly beat expectations: Revenue of 79.2 billion DKK, adjusted EBIT of 31.7 billion DKK (+34%)
- Wegovy pill, with quarterly revenue of 5.39 billion DKK, emerges as a new growth driver
- 2026 forecast raised for the third time (−2% to +2% at constant exchange rates)
- Low valuation with a P/E ratio of around 10
- Dividend of DKK 11.70 for 2025 (yield approx. 4.2%)
- A breakout above 308 DKK would open up upside potential to 395 and 513 DKK
⚠️ Risks
- Established bear market: Stock is trading below the downtrend line and the Ichimoku cloud
- Impairment charges of 8.7 billion DKK, of which 4.6 billion DKK relate to Ziltivekimab
- Reported Q3 operating profit down 3% to 23.0 billion DKK
- Fierce competition with Eli Lilly and price pressure in the U.S.
- Skeptical analysts: Deutsche Bank “Sell” (225 DKK), Morgan Stanley “Underweight” (250 DKK)
- Drastic sell-offs loom below 200 DKK
Sources
- Novo Nordisk Company Announcement No. 65/2026: Financial Report Jan. 1–Sept. 30, 2026 (Nov. 4, 2026)
- Novo Nordisk Investor Relations
- Novo Nordisk 2026 Half-Year Report (Form 6-K, SEC)
- Novo Nordisk Annual Report 2025 (Form 6-K, SEC)
- Reuters: Novo Nordisk’s Wegovy pill beats forecasts as it battles Lilly (November 4, 2026)
- Investing.com: Novo Nordisk Raises 2026 Outlook (November 4, 2026)
- AWP via finanzen.ch: Novo Nordisk following Q3 results (November 4, 2026)
- dpa-AFX Analyser via boerse.de and finanznachrichten.de: Analyst ratings for Novo Nordisk
- NPinvestor and TradeDesk: Price, 52-week range, P/E ratio, consensus price target
- Zacks and TIKR: Eli Lilly Q3 2026
- The Local Denmark and Finviz: Novo Nordisk revenue warning 2026
- Stock3: Novo Nordisk weekly chart (Cboe Europe, DKK), as of November 4, 2026
- Aktienfinder: Novo Nordisk Valuation and Key Ratios
This is not investment advice—all information is provided solely for financial education purposes.
What are your current thoughts on $NOVO B (+2,61 %)?


