Copart (ticker CPRT on Nasdaq) is an American company that is a global leader in online auctions of used and damaged vehicles, acting as a intermediary between sellers (mainly insurance companies, banks, rental companies and fleet owners) and buyers all over the world. The business is technology-intensive, with a digital platform that allows remote participation in auctions and integrated management of the entire vehicle cycle, from loss to resale or scrapping.
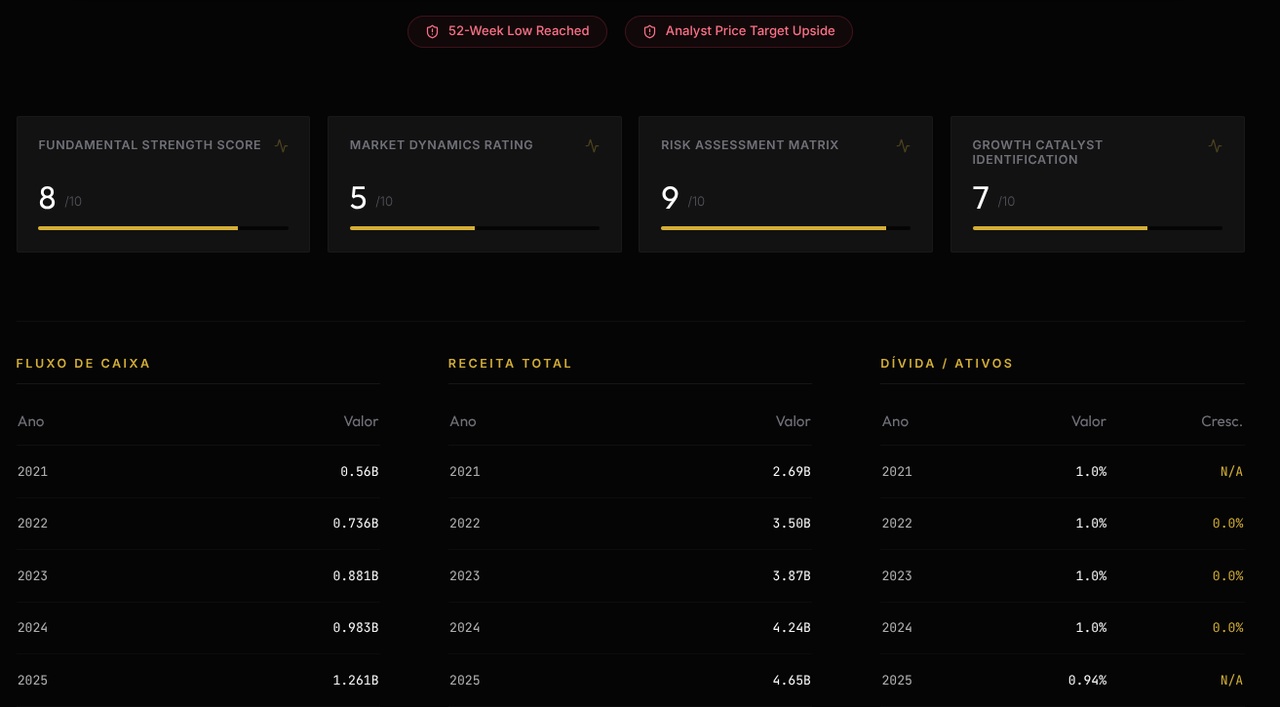
Fundamental Strength Score 8/10
Copart ($CPRT (+1,96 %) ) demonstrates robust financial health.
Free Cash Flow has grown consistently over the last five years, reaching $1.261 billion by 2025.
Revenue has also shown solid growth, rising from $2.69 billion in 2021 to $4.65 billion in 2025.
The current P/E ratio of 23.45, while not the lowest historically, is below the average of the last 5 and 10 years, suggesting a potentially more attractive valuation.
Market Dynamics Rating 5/10
Copart's stock has faced challenges, down -31.78% in the last year and hitting a 52-week low at $38.17 today at the time of publication.
Market sentiment is mixed, with a consensus analyst rating of 'Hold', based on 3 buy ratings, 6 hold ratings and 2 sell ratings. Key support levels are at $38.40 and $39.07, resistances are at $39.51 and $39.98.
Risk Assessment Matrix 9/10
The risk associated with Copart is considered low, mainly due to its strong financial stability.
The company has an impressive Altman Z-Score of 26.53, indicating very solid financial health and a low probability of bankruptcy.
The low Debt/Assets ratio (0.94%) minimizes financial risk.
Market risks are mitigated by the stock's liquidity and controlled movements.
Growth Catalyst Identification7/10
Copart operates on a resilient business model, focused on salvage vehicle auctions, with a strong market position.
Continued growth in revenue and Free Cash Flow demonstrates the company's ability to expand its operations and generate value.
The expansion of its land network and the quality of its services are driving the volume of vehicles.
Innovation in its virtual bidding platform (VB3) continues to be a growth driver
Valuation Analysis (DCF & Multiples)
The valuation analysis, based on analysts' estimates, suggests significant upside potential.
The current price of $38.17 is below the median target price of $48.18, indicating upside potential of +26.23% in the base case.