
Convincing figures
Financially, this approach is reflected in an impressive track record. Over the past ten years, sales have increased from 1.81 to 5.37 billion US dollars, while earnings per share have climbed from 1.37 to 6.47 US dollars.
The operating margin has improved from around 8% to over 9% during this period.
In addition, the expansion was financed almost entirely from current cash flow. There are no significant debts, and the number of outstanding Aktien The number of shares outstanding even fell from 70 to 67 million during this period.
In return, the dividend has multiplied from USD 0.66 to USD 2.58 per share. The Dividendenrendite currently stands at 1.55 %. At first glance, this is not a lot, but in my view, it is the direction and not the current level that matters most when it comes to dividends.
For example, anyone who bought into Texas Roadhouse 10 years ago can now enjoy a dividend yield of around 7.5% (based on the purchase price at the time).
Dividend with a future
So if you want to make provisions for your retirement and Dividenden should focus on companies that have the potential to consistently increase their dividend payout over the coming decades.
This, in turn, is only possible if the company has the potential for growth.
This is likely to be the case with Texas Roadhouse.
The company's expansion could continue for decades to come. So far, Texas Roadhouse has mainly been active in the eastern half of the USA, which opens up considerable further potential. In addition to the core brand, business is also growing with the two additional brands Bubba's 33 and Jaggers.
The company currently operates 608 of its own Texas Roadhouse locations, 49 Bubba's and 9 Jaggers. In addition, there are 60 franchise restaurants in the USA and 58 more abroad - almost all under the Texas Roadhouse brand.
Franchise as a yield turbo
In view of competitors such as Outback Steakhouse with over 1,000 branches or Chili's and Applebee's with more than 1,600 locations, the growth potential is far from exhausted.
Added to this is international expansion, which is still in its infancy.
Another factor is the increasing proportion of franchise business. This is a highly profitable, low-risk business that also requires hardly any capital of its own.
It currently accounts for around 15% of the Group's business, but already around 30% for new locations. This shows where the direction could go.
As the franchise share increases, margins and returns on capital increase, which in turn suggests a rising valuation. At the same time, this creates scope for higher payout ratios.
Profit increases of 13-15% are expected in each of the next two financial years. This is in line with long-term averages and therefore seems plausible.
The share should have similar potential. The forward P/E (2026) is currently 23.6.
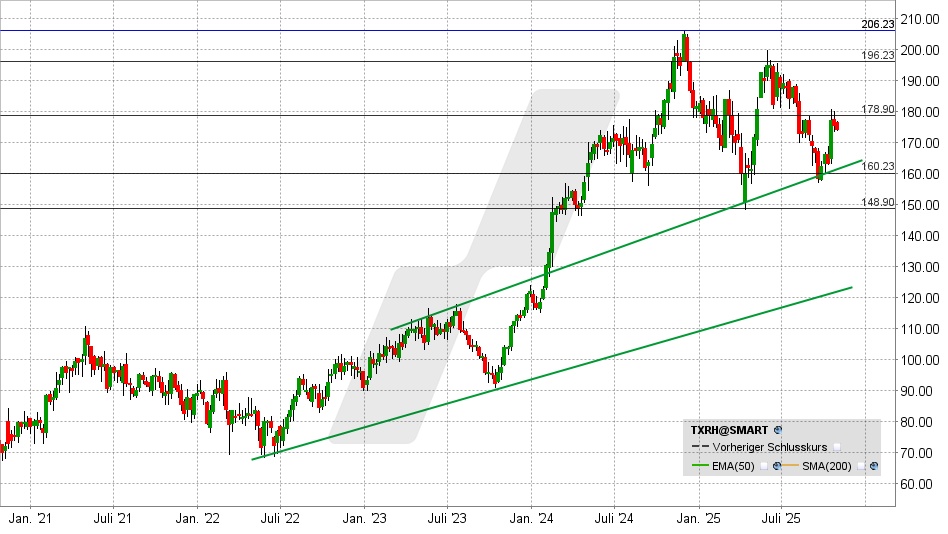
Texas Roadhouse share: chart from 28.10.2025, price: USD 174.31 - symbol: TXRH | Source: TWS
From a technical perspective, the positive signs are also increasing. If a breakout above USD 179 now succeeds, a pro-cyclical uptrend will begin. Kaufsignal with possible price targets at USD 196 and USD 206.
If the share returns towards USD 160, this could be interesting for anti-cyclical investors.
Source


