
Good morning, everyone,
Since a pharmaceutical stock hit the Portfolio 2036 , I’m now looking for an alternative.
Four pharmaceutical stocks are still in the Portfolio 2036. That’s why I’m now focusing my search on stocks from the second wave. However, I’m trying to stay within the healthcare sector.
AI and healthcare are, for me, one of the most exciting areas for the future.
And that’s why this weekend’s feature is about
$VEEV (-1,37 %)
Veeva Systems
an AI specialist for the biopharma industry! 14 of the top 20 pharmaceutical companies rely on Veeva Systems!
The “Healthcare” sector is currently experiencing strong momentum and has gained 4.2% in just one month. The “Health Information Services” segment, in particular, is shining. My friends, today we’re taking a look at the frontrunner, Veeva Systems, which has risen by a strong 18.69%. What has changed since the setback at the beginning of the year? Veeva Systems offers cloud and AI software for the life sciences; 14 of the top 20 pharmaceutical companies rely on these systems. With an 18% increase in revenue in the most recent quarter, Veeva is raising its annual forecast.
Vault CRM & AI agents driving the stock price—monopoly position in the life sciences sector continues to grow
Veeva Systems is a market leader in cloud-based software for the life sciences industry. On August 27, the company significantly exceeded expectations for the second quarter. Revenue climbed 18% to $928 million, driven by a 16% increase in subscription revenue. Adjusted earnings per share rose to $2.35, well above estimates. Due to the strong business performance, management raised its full-year guidance and now expects revenue of up to $3.687 billion and earnings per share of approximately $9.21.
Veeva Systems Inc. (ISIN: US9224751084) develops software for pharmaceutical and biotech companies to manage clinical trials, regulatory filings, and relationships with physicians. The company generates most of its revenue from software subscriptions, supplemented by data offerings and services. Veeva was founded in 2007 and went public on the NYSE in 2013.
Meanwhile, adoption of the Vault CRM customer management software is steadily increasing.#
Strategic commercial successes and product adoption provide the operational foundation for this valuation expansion. Veeva has secured significant global commitments from major industry players, thereby solidifying its dominance in the life sciences industry’s cloud ecosystem. Notably, Regeneron Pharmaceuticals has committed to a global rollout of Veeva Vault CRM with the goal of leveraging AI-powered field operations. Similarly, the clinical research organization IQVIA has expanded its use of Veeva’s clinical applications, including CTMS and eTMF, in its development studies. Furthermore, emerging biotech companies are increasingly standardizing on Veeva Basics to accelerate drug development, while Servier is deploying Veeva OpenData in 80 countries to support AI initiatives. These deals underscore the deepening integration of Veeva’s platform into critical customer workflows.
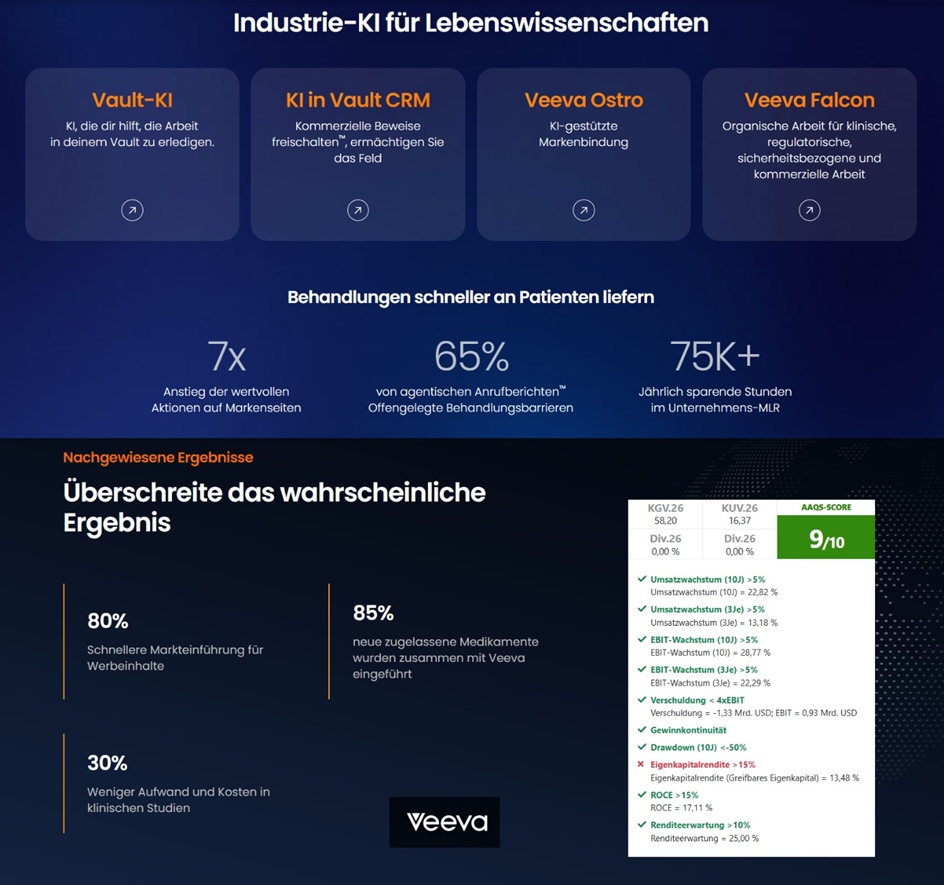
The market is also recognizing the potential of Veeva’s artificial intelligence strategy, particularly the Falcon platform for agent-driven workflows. Management has introduced innovations such as the Veeva Study Builder Agent, which automates the setup of clinical trials, and Veeva Falcon Safety, which is designed to optimize the capture of adverse events. These tools are designed to reduce costs and increase speed in regulated biopharma operations. Analysts view these AI capabilities not as a risk of disruption, but as a key driver of future revenue growth and margin expansion, citing the company’s ability to embed AI into high-risk, compliance-intensive workflows.
Conclusion: Veeva combines a subscription-based business model with growing demand for specialized pharmaceutical software. The latest quarterly results and the growing adoption of Vault CRM reinforce the outlook for continued revenue and profit growth. For sustained stock price gains, it will likely be crucial that the newly acquired major clients generate additional revenue and that Veeva meets its improved full-year outlook.
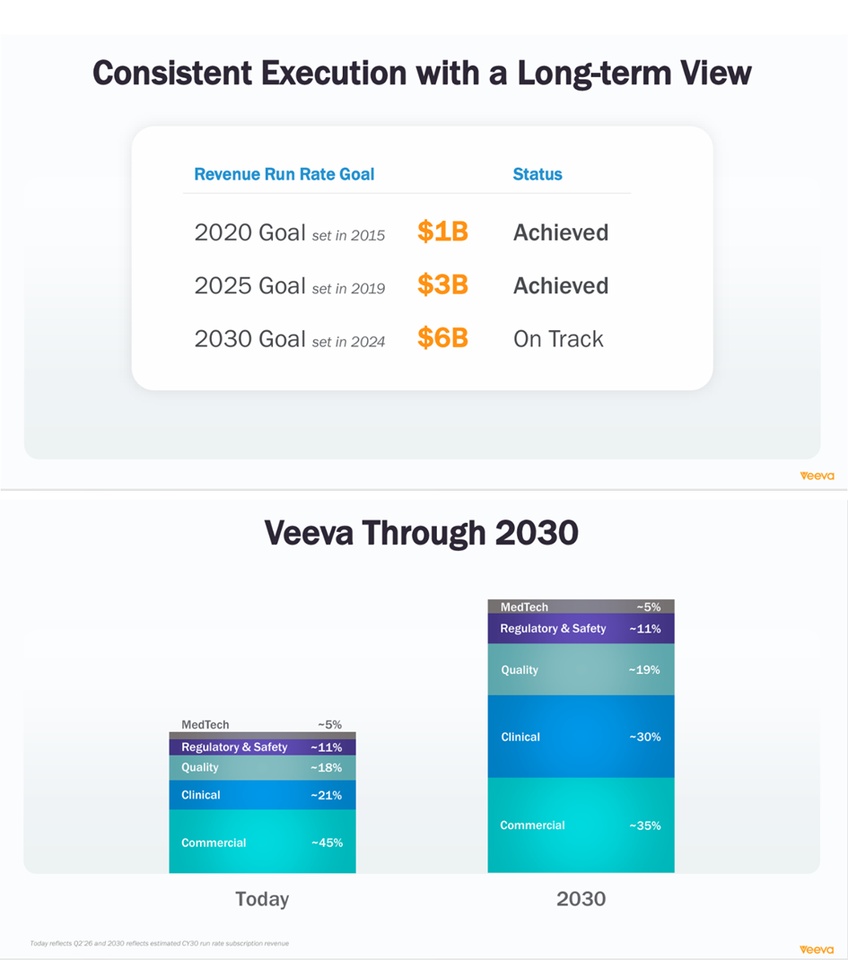
Veeva Systems Inc. specializes in the development and marketing of cloud-based solutions for the life sciences industry. The company offers software, data, and consulting services. Its solutions are aimed at pharmaceutical and biotechnology companies, as well as companies in the technology and medical device sectors. Net revenue is broken down by business segment as follows:
- Subscription revenue (84%);
- Services (16%).
Net revenue is distributed geographically as follows: North America (59.6%), Europe (29.4%), Asia/Pacific (8.8%), and Other (2.2%).
Number of employees: 7,928
Oppenheimer Reaffirms Rating for Veeva Systems – R&D Growth on Track
Published on October 15, 2026, 11:48 a.m.
🔹 Oppenheimer confirms “Outperform” rating for Veeva Systems
- Price target remains $325.
- Discussions with Veeva show: R&D growth is on track, despite the previously indicated slowdown.
- The transition from the “old” to the “new” generation of R&D products is proceeding as expected.
- Demand in the R&D segment remains broadly stable; no indications of deals being brought forward.
🔹 Operational Strength & Forecast Upgrade
- Forecast raised thanks to strong operational execution and improved visibility.
- Consulting remains a robust growth driver.
- Vault CRM migrations are near record levels; uncertainties are easing.
- Management is confident about customer winbacks.
🔹 Veeva remains the “Best Idea”
- Reasons, according to Oppenheimer:
- Strength in the commercial segment is expected to be sustained .
- The slowdown in R&D is understood and taken into account.
- AI monetization offers additional opportunities.
🔹 Strong Q2 figures (FY 2027)
- Revenue: $928 million
- Exceeds Truist’s forecast (904 million) and the consensus estimate (905 million).
- Analysts raise price targets:
- Wells Fargo: $330 (AI potential)
- Truist: $305 (Buy)
- TD Cowen: $283 (19% billings growth)
- Piper Sandler: $320 (subscription acceleration, balanced segment growth)
Based exclusively on Veeva Systems’ website at MarketScreener Deutschland
The publication date is March 4, 2026, so the figures do not yet reflect the upward revision to the forecast.
5. My Assessment for the 2036 Portfolio
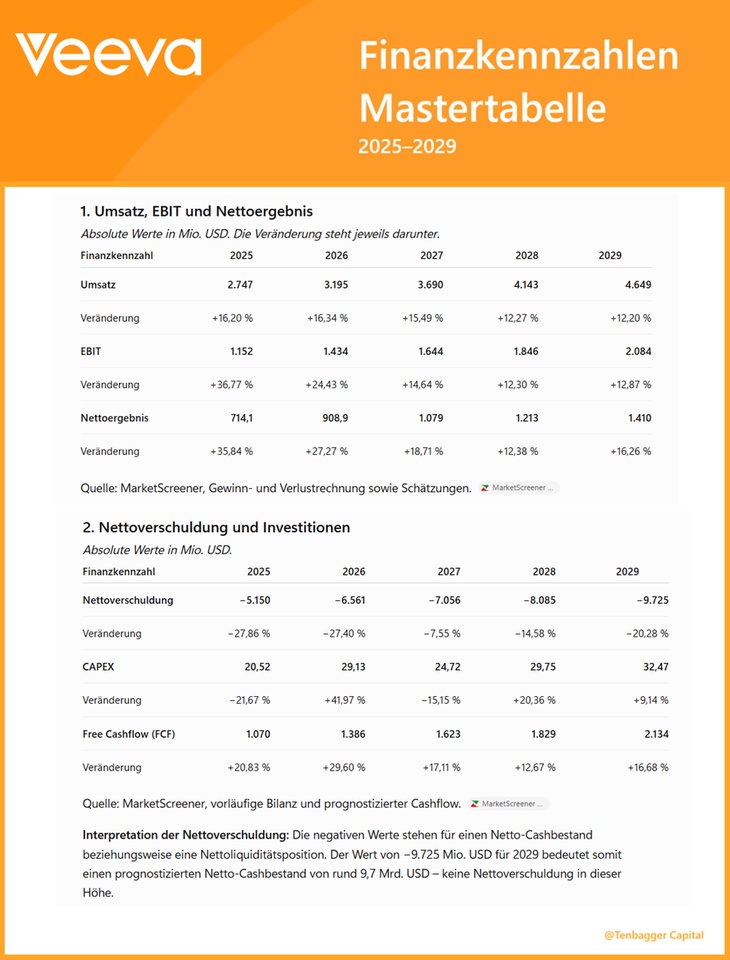
MarketScreener’s forecasts paint an interesting picture for Veeva Systems:
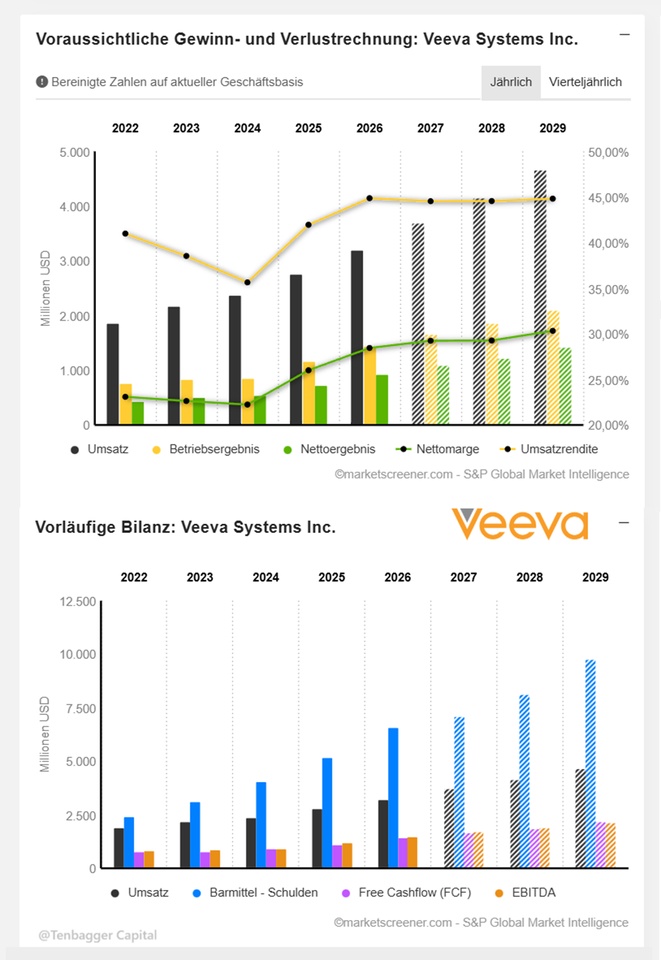
- Growth: Revenue is expected to rise from $2.75 billion in 2025 to a projected $4.65 billion in 2029.
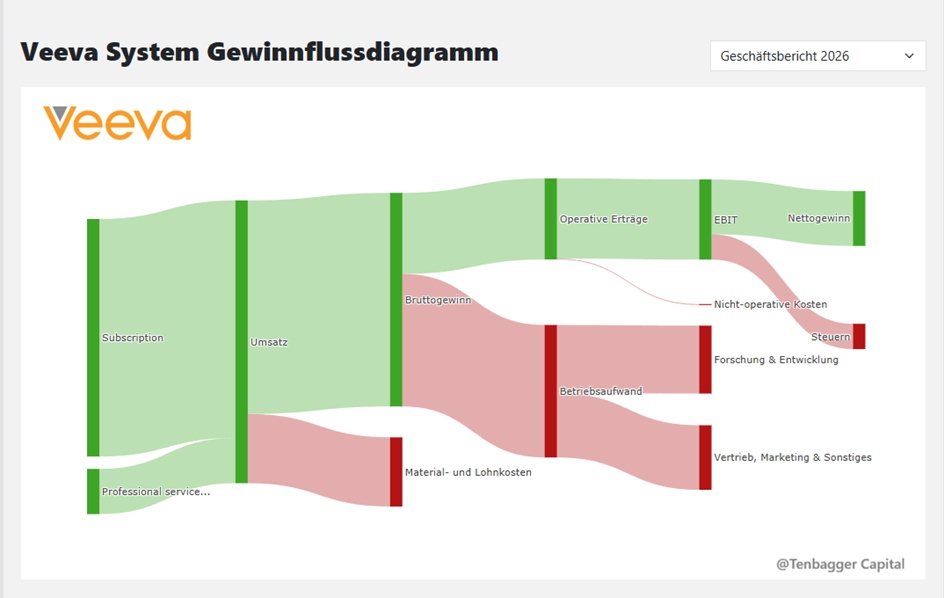
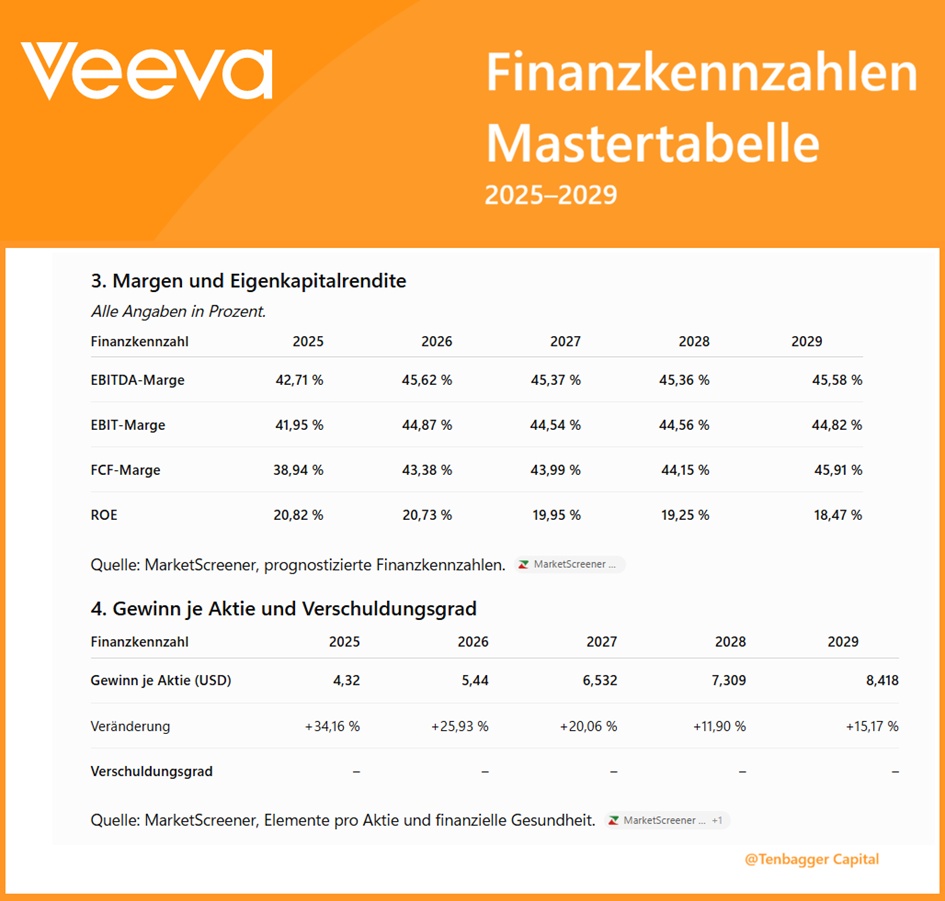
- Profitability: The EBIT margin is expected to hover around 45% over the forecast period. This is remarkable for a growing software company.
- Cash Flow: Free cash flow will rise from $1.07 billion to $2.13 billion.
- Financial Strength: Projected net liquidity continues to increase.
- Earnings Growth: Earnings per share are rising from $4.32 to $8.418.
What I’ll be paying particular attention to
According to the forecast, the return on equity will decline from 20.82% to 18.47%. At the same time, free cash flow is growing significantly. This isn’t necessarily a negative: A growing equity base can depress the return on equity, even as the company strengthens its operations.
For my analysis of the second wave of AI, it is particularly important whether Veeva can successfully monetize AI capabilities and how this will impact revenue growth, margins, and cash flow.
My conclusion: The published forecasts show a company with strong cash flow, high margins, and a solid financial position. Whether the stock is attractively valued must be assessed separately based on the current stock price and valuation metrics.
All forecasts are estimates and not guaranteed results.
🔎 Brief Analysis
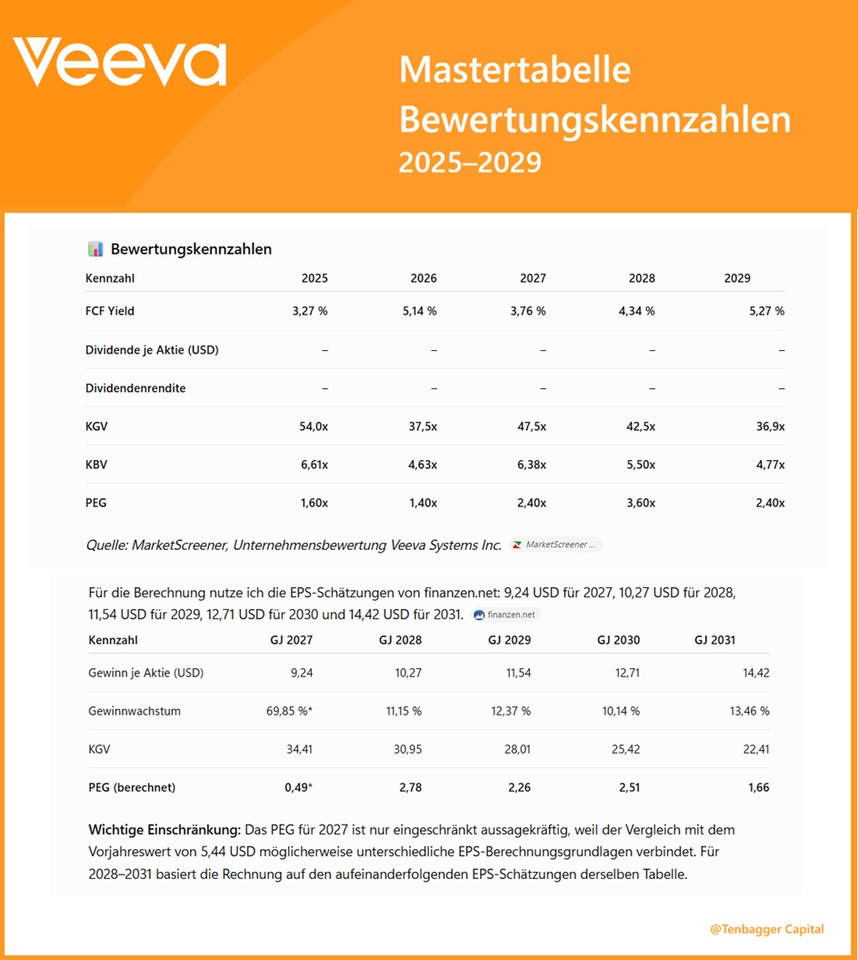
- FCF Yield: 5.27% is projected for 2029—higher than for 2025 and 2026.
- P/E Ratio: The valuation declines from 54.0x in 2025 to a projected 36.9x in 2029, though not at a steady rate.
- P/B ratio: A P/B ratio of 4.77x is expected for 2029.
- PEG: The highest value during the period shown is 3.60x in 2028.
Important: The figures are taken from the provided MarketScreener link. Other financial portals may report different metrics due to varying earnings estimates, calculation methods, or update times. The figures should therefore be understood as reflecting the data available at that time.
For the master table, I would list the PEG values from finanzen.net separately from the PEG figures from MarketScreener, since the portals use different P/E and EPS estimates. This ensures that the basis for the calculations remains transparent.
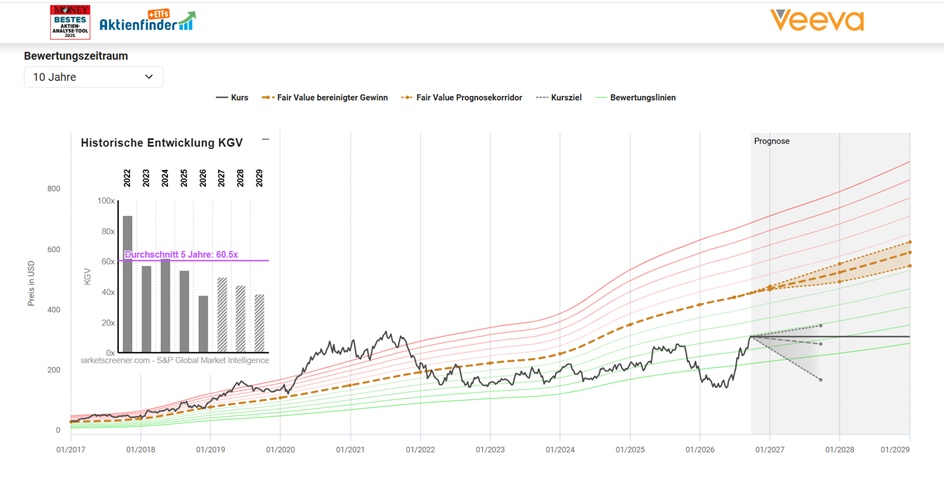
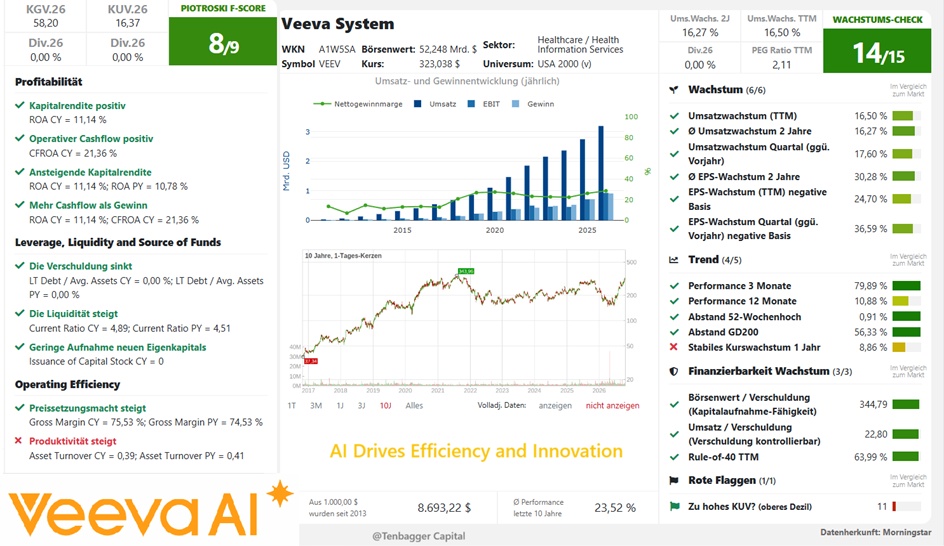
The metric with the highest stability for Veeva Systems stock is the adjusted earnings, which is used for the valuation below. The P/E ratio (price-to-earnings ratio) stands at 37.23 , which is 15.04 points below the historical average of 52.27 over the past 10 years. From this perspective, Veeva Systems stock appears to be to be undervalued .
The fair value of Veeva Systems stock is calculated using the 10-year valuation period selected above. In this case, the average P/E ratio is 52.27.
Multiplying this by the adjusted earnings per share of $8.69 for the last 4 quarters yields a fair value of $454.20. The current price of $323.54 is 28.8% below this fair value, which represents a undervaluation of the stock.
(Source: Aktienfinder)
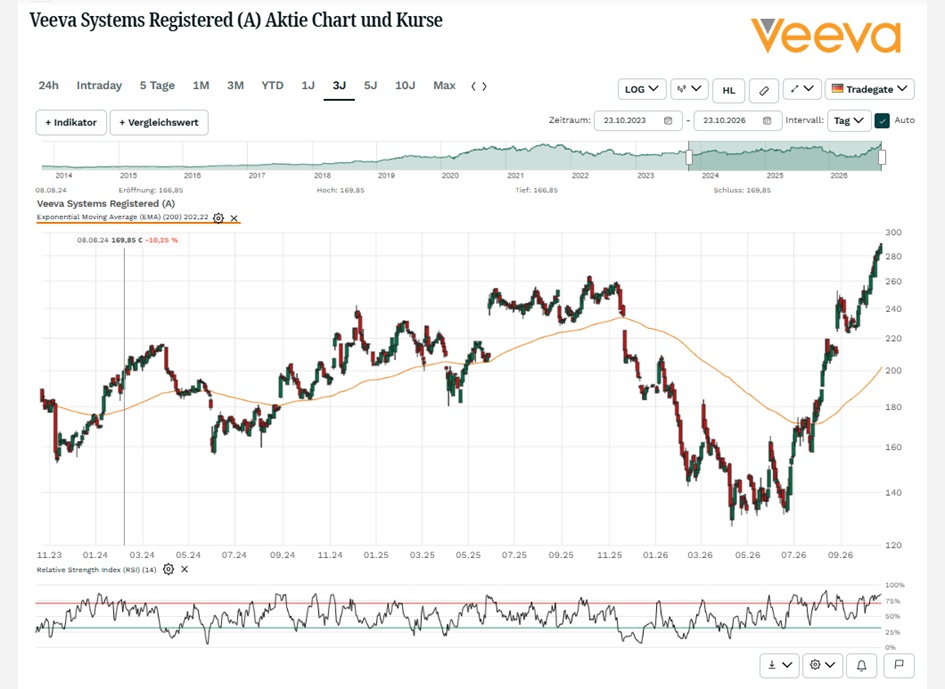
Performance:
1 week +4.09%
1 month +19.31%
6 months +106.88%
1 year +10.82%
3 years +65.55%
After a rally of +106% over 6 months, it’s probably best to wait for a correction here and keep an eye on the RSI closely.
289.00 EUR +1.80 EUR +0.63%
Oct. 23, 2026
BMN
323.00 USD + 0.06 USD + 0.02%
after-hours
01:46:54


