In Switzerland, many employers offer a choice of different pension savings plans. The contribution rates and the split between employer and employee vary depending on the pension fund and the employer.
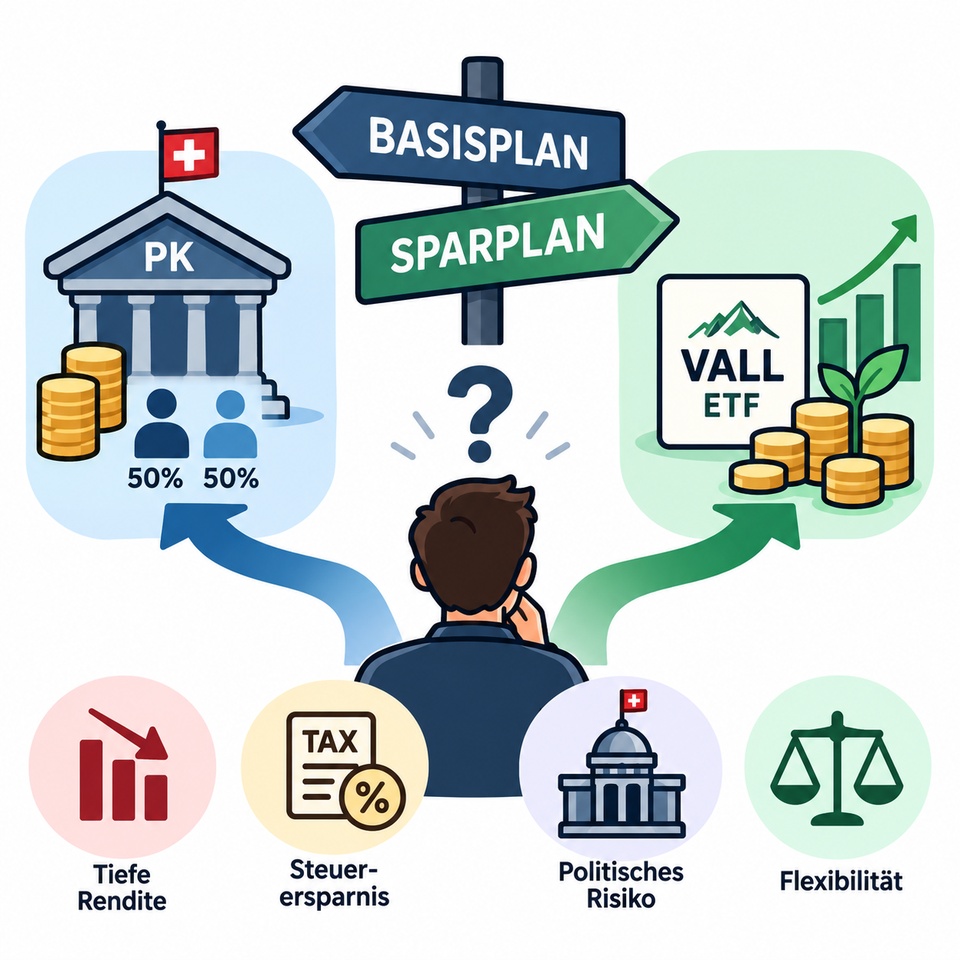
In the basic plan, for example, the employer and employee split the contributions 50:50. In a savings plan, the employee voluntarily contributes more.
💰 The advantage: Higher pension fund contributions reduce taxable income and result in tax savings.
📈 The disadvantage: Pension funds often generate comparatively low returns. In the long term, therefore, investing independently in ETFs may be more worthwhile despite the lost tax savings. Last but not least, there is also a political risk, as future political reforms could change the framework conditions for pension funds and thus retirement planning.
🎯 My decision: I’ve opted for the basic plan and am now investing the saved contribution myself in the $VALU (-0,37 %)
ETF. I hope this will yield a higher return in the long run.
💬 How do you handle this? Do you make additional pension contributions for tax optimization, or do you prefer to invest in ETFs on your own?
#Schweiz
#Pensionskasse
#BVG
#Altersvorsorge
#ETF
#VALL
#Investieren
#Steueroptimierung
#Vermögensaufbau