
Veeva has recently come under massive pressure. The company has responded with new quarterly figures and an impressive outlook.
The reason for the sell-off is well known; after all, no topic has been discussed more in recent months: Veeva has been traded as an AI loser.
Quarter after quarter will show whether this narrative was correct or not. So far, the bulls have achieved one victory after another on the fundamental front - even if the share price performance suggests the opposite.
Indispensable for the pharmaceutical industry
Veeva offers cloud-based software solutions that are precisely tailored to the complex requirements of the pharmaceutical industry.
Unlike generic providers, Veeva understands the strict regulatory hurdles that pharmaceutical companies have to overcome in research, approval and sales. The platform supports the entire life cycle of a drug - from early research and clinical trials to commercialization and distribution.
This integration provides measurable efficiency gains and makes Veeva indispensable for its customers.
At the heart of its success is Veeva Vault. The platform is much more than a cloud storage for documents. It was developed specifically for regulatory compliance. Pharmaceutical companies must document every step of development and marketing in an audit-proof manner in order to meet the strict requirements of authorities such as the FDA or EMA.
Veeva Vault automates these compliance processes and allows documents and data to be managed securely. At the same time, the platform significantly improves collaboration between internal departments and external partners.
Burgraben: Complexity, compliance, long runtimes, high switching costs
Compliance risks are minimized, which is of enormous value to pharmaceutical companies, as violations can mean not only fines but also the loss of marketing approval.
In addition to documentation, Veeva accelerates research and development through the Veeva Clinical Cloud. Clinical trials are traditionally one of the most expensive and time-consuming phases of drug development. The digitalization of study planning, data collection and patient protocols significantly reduces effort and duration.
On the commercial side, the Veeva Commercial Cloud, together with Veeva CRM, supports sales and marketing.
The business model is clearly designed for recurring revenue. Customers generally subscribe to the software via multi-year contracts, which creates a high level of planning security. The implementation of the systems leads to high switching costs, meaning that customer loyalty is exceptionally high.
This combination of complexity, compliance, long research cycles and high switching costs forms the moat that sets Veeva apart from its competitors.
Fundamental strength despite share price setback
A few days ago, the company presented its figures for the final quarter of 2025.
At USD 2.06 per share, earnings were well above expectations of USD 1.92. With revenue of USD 836 million, analysts' estimates of USD 810 million were also significantly exceeded.
For the year as a whole, this corresponds to a 16% increase in sales and an 18% jump in profits.
This means that sales growth in the final quarter was at the same level as for the year as a whole. The momentum has therefore not slowed - there is no sign of increasing competition or even disruption.
This is also supported by the fact that the operating margin (non-GAAP) rose from 42.0% to 44.9% in the last financial year.
Earnings increased by 23% to USD 8.10 per share in 2025. Veeva therefore has a P/E of 24.1.
Target for 2030: 6 billion dollars in sales
Veeva is currently in a phase that CEO Peter Gassner describes as an "agentic transformation" - a shift towards more data-driven, intelligent applications in the life sciences industry.
According to Gassner, this development opens up significant opportunities for the company. Veeva can build on its core systems, which cover the industry's most important functions, as well as unique data sets to deeply integrate AI solutions into existing applications.
In particular, the initiatives around Veeva AI and the proven Commercial Cloud, Development Cloud and Quality Cloud platforms are expected to bring significant added value to the industry.
Gassner emphasizes that while AI is being hailed as a new paradigm for software and hardware, it will not replace existing core systems. Systems such as Veeva, SAP or Workday are indispensable for the respective industries.
For this reason, the Executive Board has set the long-term goal of increasing revenue to USD 6 billion by 2030 ("As we look ahead, strong momentum and operational discipline give us confidence in our trajectory towards our $6 billion revenue run rate target by 2030").
Outlook and valuation
Compared to the previous financial year, this would correspond to an almost doubling of sales.
To achieve this target, Veeva would have to achieve average sales growth of 13.4% in the financial years 2026 - 2030.
The outlook fits in with this. In the current financial year (1/2027), Veeva expects an increase in sales from USD 3.20 billion to USD 3.60 billion and a jump in earnings from USD 8.10 to USD 8.85 per share.
The previous consensus estimates were USD 3.54 billion and earnings of USD 8.50 per share.
On this basis, Veeva has a forward P/E of 22.1, which is reasonable given the characteristics of the business model and the sustained high growth rates.
Over the last five years, the P/E has averaged 45.
As the company is known for its conservative forecasts, there is a high probability that the outlook will be exceeded.
Veeva had initially forecast earnings of USD 7.32 per share for the financial year just ended - as we now know, the final figure was USD 8.10 per share
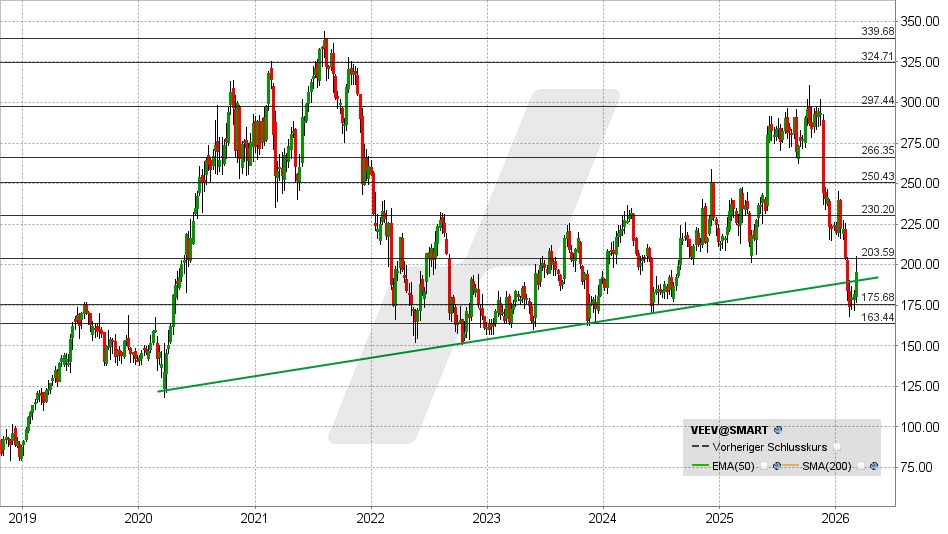
Veeva share: Chart from 09.03.2026, price: USD 195.49 - symbol: VEEV | source: TWS
The first reaction to this news was a jump in the share price. If it now manages to rise above USD 204, a procyclical buy signal with possible price targets of USD 218 and USD 230 will emerge.
However, if the share falls below USD 175 on a sustained basis, there is a risk of further price losses in the range between USD 164 and USD 150. Below this level, the chart picture would become even gloomier.
Source

