

Hello, everyone,
Yesterday, our dear @Raketentoni a comparison of energy stocks.
Among others, the top pick of the day $GNRC (+0,88 %) Generac.
But the stock we’d like to introduce to you today was also included. This stock might surprise you just as much as Generac.
@Raketentoni will be collaborating with me and will present his agents’ analysis to you once again in a repost.
Thank you very much in advance for this.
As always, we look forward to hearing your opinions in the comments.
Hammond Power Solutions Inc. is a manufacturer of dry-type transformers in North America. It was founded in Ontario in 1917. The company develops and manufactures a range of standard and custom transformers, which are exported worldwide as electrical equipment and systems. Its product categories include control and automation products, low-voltage distribution products, medium-voltage distribution products, power quality products, as well as filters and specialty products. Control and automation products include control transformers, isolation transformers for drives, and chokes. The company serves robust industries such as oil and gas, mining, steel, waste and water treatment, commercial construction, data centers, and wind power generation. In addition, it offers “Integrated Electrical Solutions” (IES), a business unit focused on providing more comprehensive system-level solutions. The company has manufacturing facilities in Canada, the United States, Mexico, and India, and distributes its products worldwide.
Number of employees: 2,121
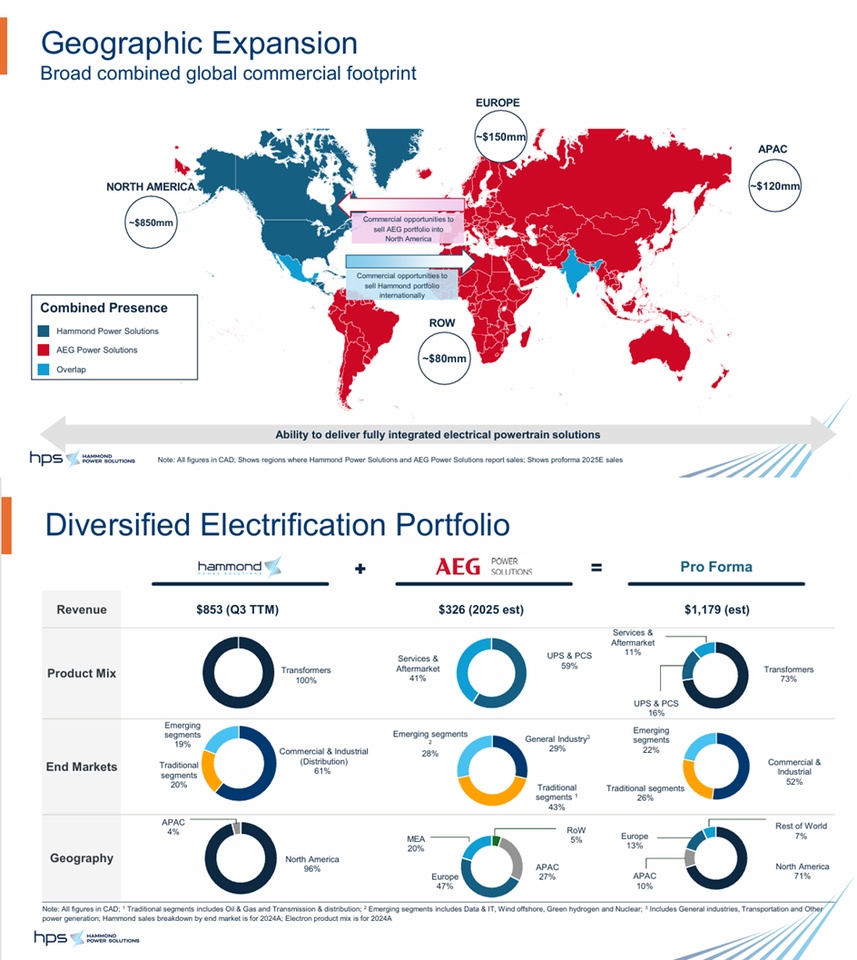
The acquisition of AEG Power Solutions by Hammond Power Solutions (HPS) is strategically very interesting from an investor’s perspective:
Product expansion:
AEG brings strong power electronics expertise (UPS, PCS, industrial power conversion). This allows HPS to expand its portfolio beyond traditional transformers.
Positive—strengthens technological depth
End-market diversification:
Access to sectors such as offshore wind, hydrogen, nuclear, data & IT, and rail.
Very positive – future markets
Geographic expansion:
HPS has traditionally had a strong presence in North America (≈ 96% of revenue). AEG opens up Europe, MEA, and APAC.
Transformative – true globalization
Aftermarket & Services:
AEG has an installed base with a high proportion of service revenue (≈ 41% of revenue). This increases recurring revenue.
Stability booster
Financial Impact:
The transaction (≈ CAD 365 million, all-cash) is expected to be EPS-accretive starting in Year 1; leverage is 2.7×, but strong FCF allows for rapid deleveraging.
Financially Sound
Integration:
Management retention, cultural preservation, phased integration.
Disciplined—low integration risk
💡 Investor Takeaway
- HPS is scaling up from a transformer manufacturer to an integrated power quality player.
- AEG technologies (UPS, PCS) are central to the energy transition, electrification, and grid stability.
- Synergies lie primarily in cross-selling (AEG portfolio in North America, HPS portfolio in Europe).
- The valuation (EV ≈ CAD 365 million) appears moderate given the company’s market position and growth areas.
- Risk: Integration across multiple continents; however, the management’s approach appears conservative and realistic.
🔋 Conclusion
The acquisition is strategically excellent and should catapult HPS into the league of global power-quality leaders in the medium term. For you as an investor: a clear step toward a “compounder story” with a growing service base and exposure to megatrends such as the energy transition and electrification.
Hammond Power Solutions Inc. schließt die Übernahme von AEG Power Solutions ab
Veröffentlichungsdatum: 29. Juni 2026
Allgemeine NachrichtenInvestor Relations
Geographic Revenue Breakdown:
2025 (CAD)
United States & Mexico 632 million
Canada 234 million
India 32.35 million
HPS-AEG-INVESTOR-PRESENTATION.pdf
Q2 2026
Finanzergebnisse des zweiten Quartals 2026
Veröffentlichungsdatum: 30. Juli 2026
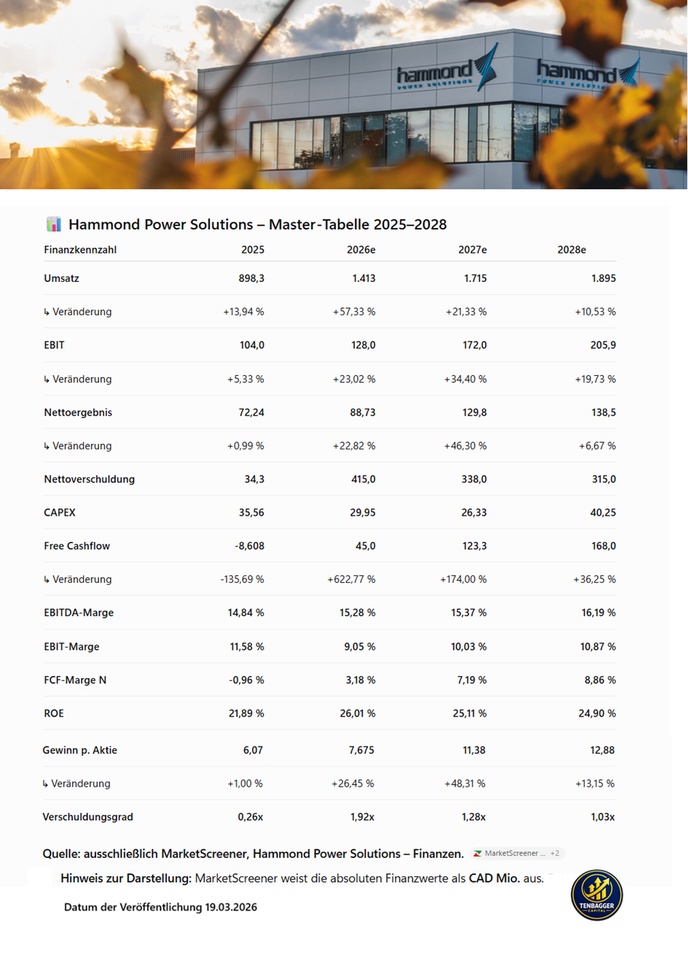
🔎 Performance at a Glance
- Revenue: 898.3 → 1,895 million CAD
EBIT: 104.0 → 205.9 million CAD
Net income: 72.24 → 138.5 million CAD
FCF: from -8.608 million 2,025 to 168 million CAD in 2028.- FCF margin: improves significantly from -0.96% to 8.86%.
- EPS: rises from 6.07 to 12.88 CAD, with MarketScreener projecting a particularly strong increase of 48.31% by 2027.
- Debt-to-equity ratio: initially rises from 0.26x to 1.92x, but then falls to 1.03x in 2028e.
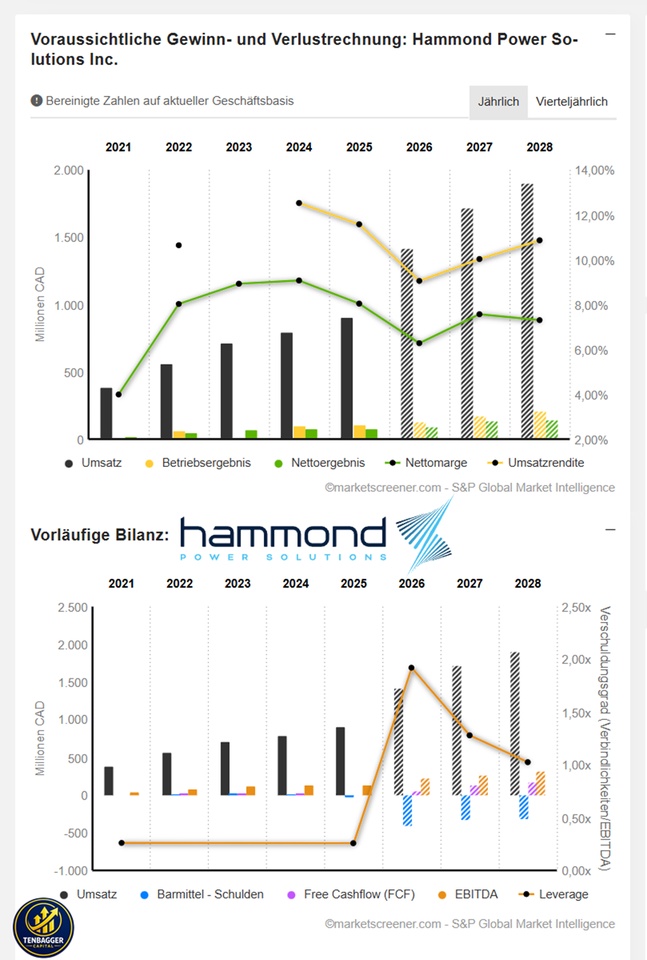
Particularly striking, therefore, is the combination of strong revenue and earnings growth and a very robust increase in free cash flow starting in 2026e.
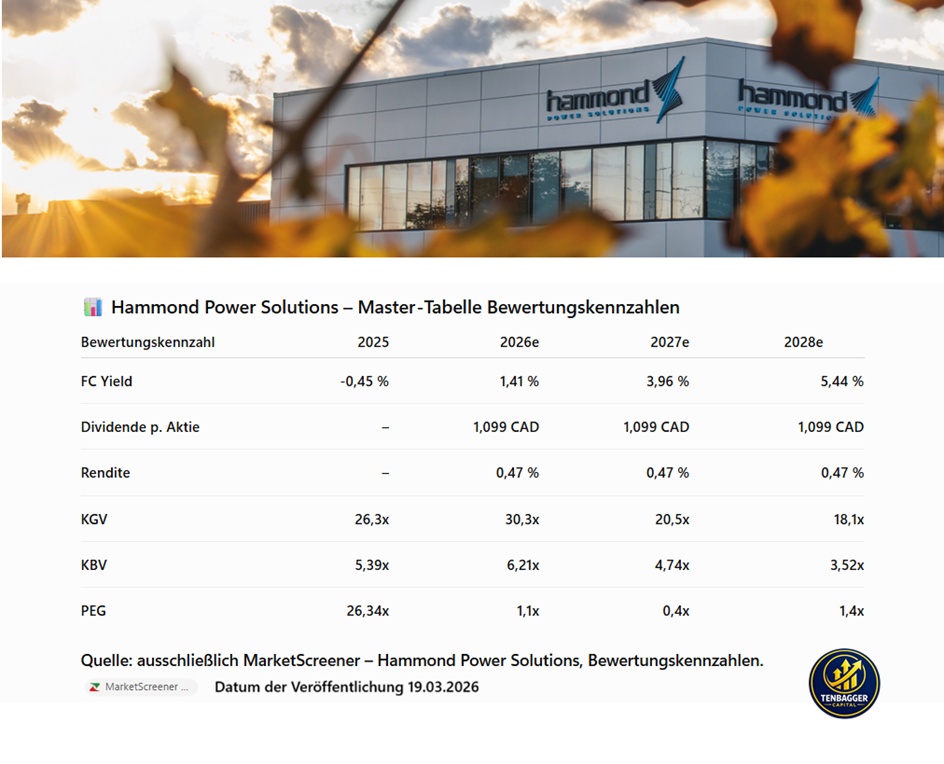
🔎 Performance at a Glance
- FC Yield: improves very significantly from -0.45% → 5.44%.
- P/E ratio: falls from the high 2026e figure of 30.3x to 18.1x in 2028e.
- P/B ratio: decreases from 6.21x to 3.52x.
- PEG: drops sharply from 26.34x (2025) to 0.4x (2027e) and rises again in 2028e to 1.4x.
- Dividend: MarketScreener projects a dividend of 1.099 CAD per share ; according to the table, the yield is 0.47%.
What is particularly interesting here is the sharply declining valuation multiples coupled with significantly rising FCF yields through 2028e.
Performance:
Year-to-date +48.55%
1 year +103.64%
5 years +2,000.27%
10 years +3,435.97%
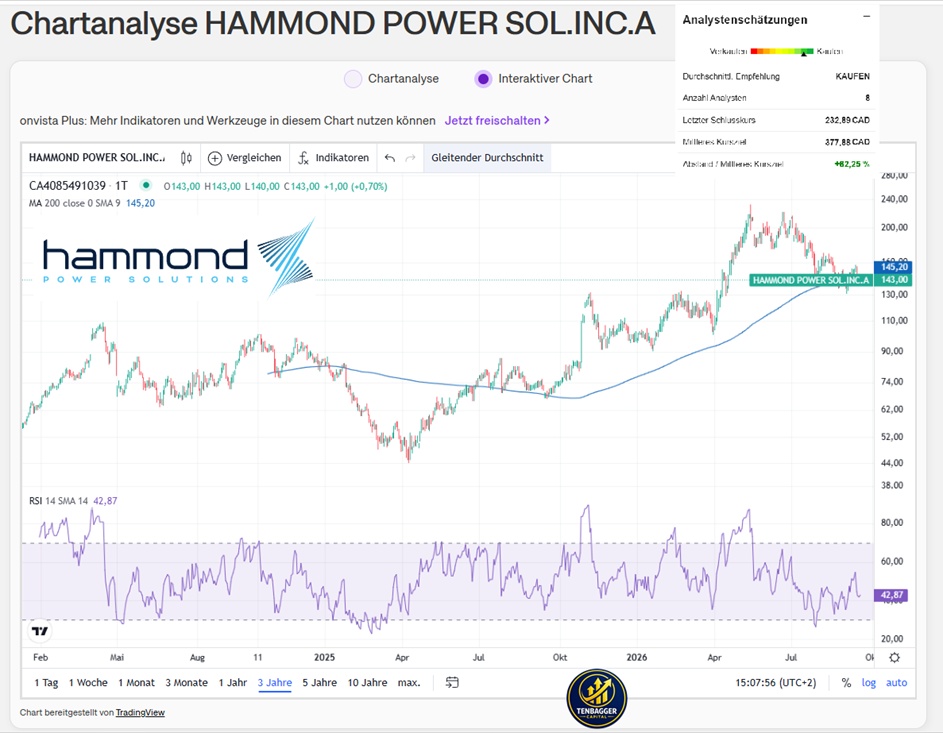
September 17, 2026, 2:46:35 PM •
Lang & Schwarz (EUR)
143.00 EUR
