3Semana·

3xGTAA – August 2026 Monthly Review

Finally, a completely normal month for the strategy again! Here’s the update:


Asset Performance 08/26 (July 31–August 31, according to Wikifolio)

3xUSDEUR: -2.3%

3xQQQ: +11.6%

3xEU50: -7.1%


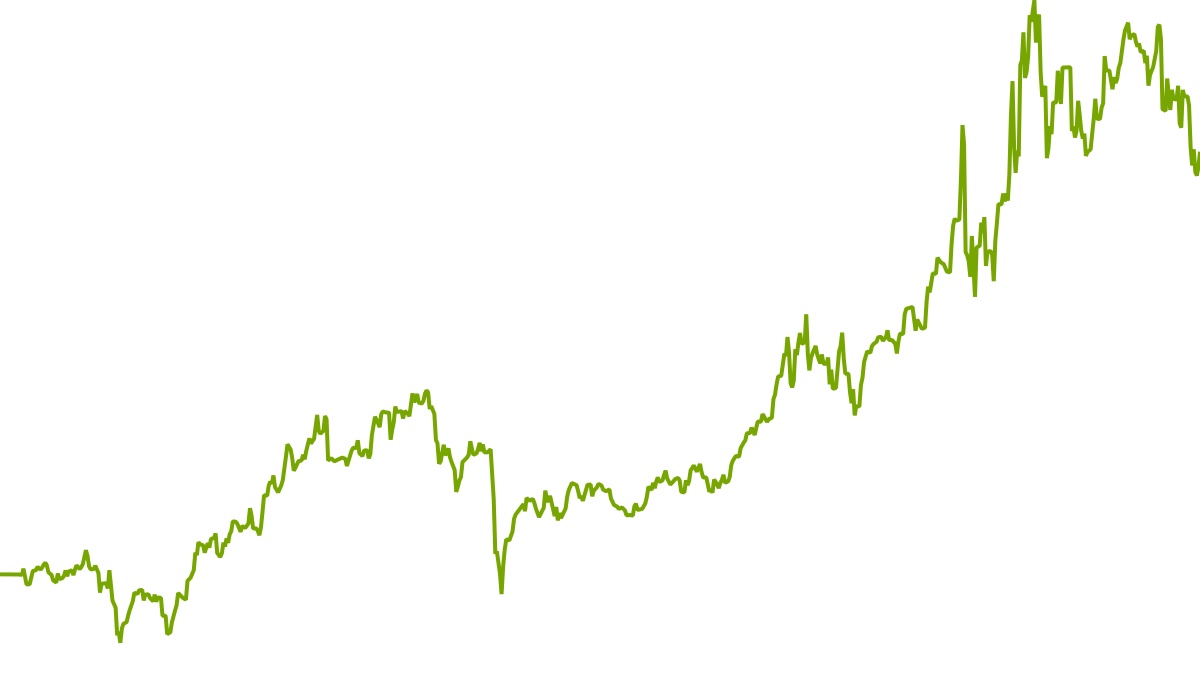
3xGTAA Portfolio (Aug. 31, according to Getquin)

July 31, 2026: €124,540

August 31, 2026: €127,700


Wikifolio Certificate (August 31, average price according to Wikifolio)

July 31, 2026: €193.70

August 31, 2026: €198.60


Month: +2.5%

YTD: +21.5%


August 2026 Review


With a monthly performance of +2.5%, 3xGTAA barely moved in August. The gains in the Nasdaq 100 were almost entirely offset by losses in the Euro Stoxx 50 and the USDEUR—even though things looked significantly more positive at one point. A quick note for the record: the losses in these two asset classes had already been foreshadowed last month, as they had almost completely lost their momentum.


Outlook 09/26


There have been some shifts in momentum within the asset pool. The EU50 and USDEUR are falling back and are thus being removed from the active allocation. Replacing them are two old favorites: WTI and BTC. WTI has stabilized significantly and is now trading above the SMA150 again. Since the margin is narrow, the signal could still change on September 1. In that case, EU50 would remain in the portfolio. The price at approximately 12:00 p.m. on September 1 will be decisive, to allow enough time for execution (finding a favorable spread, partial sales in low-liquidity conditions). The situation is different for BTC, which is trading well above the signal line following the August rally and has also shown positive momentum overall over the past six months.


The allocation for 9/26 is therefore:

2xWTI

3xQQQ

1xBTC


Report from the 3xGTAA Workshop


As already mentioned in recent monthly reports, the issue of interest rates is increasingly coming into focus for investors. This is a good opportunity to take another close look at the bond asset class in the 3xGTAA.


As some of you may know, the dominant regime of falling interest rates over the past 40 years came to an end in 2022 and is now reversing. However, this also reverses the logic behind including bonds in portfolios and strategies. What has worked over the past 40 years will not necessarily work over the next 40 years. This is relevant—even for every ordinary B&H investor. In what way? Due to their negative correlation with stocks, bonds have served as a hedge or risk buffer in many standard portfolios. You’ll still hear this from your personal financial advisor. However, when inflation reaches around 3%, this correlation flips to a positive one, and the risks of both asset classes amplify each other. You won’t hear that from your advisor anymore.


What does this mean for 3xGTAA? The asset pool consists primarily of uncorrelated asset classes, of which—according to the plan—a few are always trending upward. If stocks now fall due to rising interest rates, then bonds will also fall, and there will be no diversification. One idea would be to add short bond ETFs—that is, ETFs that rise when bond prices fall or interest rates rise.

One problem with this idea is that the new interest rate regime was only implemented in 2022 and hasn’t been in place long enough to conduct meaningful backtests. Including such ETFs in 3xGTAA would therefore be purely speculative. A specific candidate would be the WisdomTree US Treasury 30y 3x Short $UL3S (-1,27 %) (I’d call it the short -3xTLT).


Now my question for you: What do you think of the idea of adding a -3xTLT to the portfolio to potentially profit from rising U.S. interest rates? I’m still undecided on this (new interest rate environment vs. lack of backtests) and would appreciate any input!


Whatever your opinion may be: May the momentum be with you!


Yours, Epi

$DE000LS9U6W1 (-0,98 %)

https://www.wikifolio.com/de/de/w/wf03x0gtaa

previw image
44
33 Comentarios

Imagen de perfil
True to my motto, “No Risk, No Fun,” I’d take them on. Where else are you going to make a positive return? Okay, you could, of course, also short stocks or gold.
7
Imagen de perfil
@Multibagger It's just not a "No Risk, No Fun" strategy
1
Imagen de perfil
3Semana
@Multibagger Gold and stocks are difficult to short in momentum systems, primarily because of the asymmetric volatility and the resulting numerous false signals.
2
Imagen de perfil
I’m invested because your strategy is strictly based on facts and data, not on emotions and assumptions. That’s why I don’t think much of adding -3xTLT to the pool. On the contrary, it could lead me to pull out. I’d have to think it over if it comes to that.

It’s a good thing I got in early on the BTC bull market. Even if naysayers claim that a “green August” has never been followed by a “green September.”

Glad to see you’re still around.
4
Imagen de perfil
3Semana
@DonkeyInvestor The end of the 40-year cycle of interest rate cuts is more than just a hunch—it’s more like a logical fact. You simply can’t go below 0.

But the lack of backtests is certainly a compelling argument. It would be a leap into the unknown...
4
Imagen de perfil
Hi @Epi, I don’t know enough to offer a technically sound opinion on the inclusion of -3xTLT. In my experience, though, it’s never hurt to leave a system that’s working as is. As far as I understand, your 3xGTAA model has delivered what it was supposed to so far. Strictly speaking, there hasn’t been a new all-time high since March 2026, but that’s just part of the game, and the average return is still around 34% per year—which is enormous and absolutely excellent. As I mentioned earlier, though, I know far less about the technical details, so I appreciate you asking me for my input as an investor and will leave the decision up to you.
2
Imagen de perfil
I’d already given this some thought, but I was undecided about whether I should include 30-year bonds or stick with 10-year bonds in my model.

I came to the conclusion that if interest rates were to level off on the higher end, gold and BTC should pick up steam again, right? That’s why, in my view, a position in U.S. bonds would be an unnecessary risk.

I’m really curious to see how you and the other momentum traders here will adjust your models for such a scenario.😄
1
Imagen de perfil
3Semana
@HomoOeconomicus That's an interesting thought! Why do you think gold and BTC rise when interest rates go up? Intuitively, you'd think that assets yielding high interest rates would outperform non-interest-bearing assets, right? What goes against this classic logic?
Imagen de perfil
As I understand it, a high-interest-rate environment is one in which high inflation is likely to prevail and economic growth is likely to be rather moderate, with a tendency toward stagnation.

Therefore, I would expect that, in addition to bonds—due to their more attractive risk-adjusted returns—gold and BTC would also gain momentum due to the loss of confidence in fiat currencies and the institutions behind them.
Personally, I’m not a fan of government bonds, since I don’t want to finance the debt of someone whom I don’t trust to handle money responsibly.
Imagen de perfil
Good idea. Let's do it! If a significant number of investors in 3xGTAA see it differently, maybe we should consider creating a new certificate so everyone can decide for themselves?
1
Imagen de perfil
3Semana
@Keineui Well, I can just do it alongside 3xGTAA in my trading portfolio.
The real question is, how do you deal with untested asset classes?
Imagen de perfil
@Epi Your question in the article was, after all, what we think of it. That's why I'm answering.
As for your second question: backtest as much as you can. But the future will always be different from the past anyway. So for me personally, a 40-year backtest is interesting to look at, but ultimately not decisive.
2
Imagen de perfil
3Semana
@KeineuiThanks for your answer! I find the reasoning behind the answers even more interesting. I can learn from that.
So, why do you think it would make sense to include -3xTLT?
Imagen de perfil
@Epi Somehow, we need to hedge against the debt crisis. Only time will tell whether Bitcoin and gold will be able to do that, so I think the approach using options makes sense.
1
Imagen de perfil
2Semana
So what's the idea behind SpyTipps?
1
Imagen de perfil
2Semana
@T-Dax Good question. My first thought: yes. Tips is a liquidity indicator, regardless of the underlying trend in interest rates. Systematically, in an environment of rising inflation and even steeper increases in interest rates, the indicator should be negative more often.
1
Hmm. It seems like the momentum has already run out for Bitcoin again. It jumped for three days and now it’s flat again. Or to put it another way: the momentum has already faded again.
WTI is another story. It seems to me that it’s reacting less to momentum and more simply to day-to-day political events—mainly in Iran—which are essentially unpredictable.
But we’ll see.
The tlt thing might be a useful addition to our toolbox.
1
Ver todas las 2 respuestas adicionales
Can you trade this on comdirect?
1
Ver todas las 4 respuestas adicionales
Imagen de perfil
I would leave it as is.
​2x WTI provides good coverage of inflation and commodity momentum during periods of rising interest rates.
​1x money market serves as the ultimate safety net, which actually becomes more profitable when interest rates rise.

During extreme market shocks involving panic selling, major investors worldwide flee to long-term U.S. Treasuries. The TLT price shoots up abruptly—and at exactly the same moment, drags the -3x TLT into negative territory along with the 3x Nasdaq or 3xEU50.
1
Imagen de perfil
1Semana
@JBatelli Thanks for your thoughts! I think you're right. The current backtests don't show any added value from -3xTLT. The only thing that might make sense is the lower correlation with my other strategies, but that's independent of the Wikifolio.
I’ll probably just add -3xTLT to my trading portfolio watchlist and buy it when momentum picks up. 👍
Dear Epi, I myself invest in three different, strictly rule-based, and thoroughly back-tested TAAs, and I’m following your “3xGTAA” momentum-leverage strategy with great interest, and I’ve also invested a five-figure amount (i.e., 10% of my investment capital) in the Wikifolio certificate.

The mere fact of starting a discussion about adding an asset to the existing certificate—one that hasn’t been backtested and is difficult to backtest—makes me feel somewhat uneasy. And it has somehow led to a shift in my personal perception of you as the manager of 10% of my assets (sorry, this is purely subjective, but that’s what it triggered in me).

What you’re doing in your “Depotwerkstatt” and sharing with the community is great, and it certainly fosters creativity in finding investment models.

But a change like this to the certificate would be a clear reason for me to exit.

Personally, unlike most poorly managed Wikifolios (which almost every investor has already run a few into the ground—on Wikifolio), I trust this model to generate long-term excess returns for enduring the pain of drawdowns and to survive... As long as you just stick with it, month after month...

Such a change would mean “throwing overboard” the entire structure that you and other community members have tested, and to me, it would be nothing less than a reckless intervention....

Sorry for speaking my mind

May the momentum continue to be with us
1
Imagen de perfil
1Semana
@income_engineer_kyfqr I understand your concerns and have already mentioned elsewhere that I won’t be adding -3xTLT to my Wikifolio (but will hold it in my trading portfolio instead). This is based less on social considerations than on objective reasons: the asymmetric volatility, the logic of falling returns during a market crash, and the lack of backtests all argue against including it. It was really just a thought experiment from the workshop, but if that’s too much transparency, then I’ll just leave it out.

Still, based on some recent backtests from the nerd group, there might be a few minor adjustments to the model. I’ll probably remove the FX pairs from the pool; they haven’t shown any positive effect, they increase complexity, and the logic behind them isn’t entirely convincing. This would bring 3xGTAA back to the classic, lean, simple model: QQQ, EU50, BTC, GLD, WTI, TLT. This has proven to be quite robust in the tests.

What kind of TAAs do you invest in, if I may ask?
@Epi My core investment is in Keller’s HAA, and on the side, I’ve adopted even more aggressive momentum models for individual stocks from the world of system traders, which also require only one trading intervention per month. No “buy and hold.”

According to my own research (without ever having conducted a backtest myself), short products have essentially always failed in models with such infrequent trading activity. After all, no one would dare to include 3x short positions on any of the other assets from 3xGTAA in the model.... Maybe my way of thinking is too conservative? But for me, that would mean a fundamental change to your approach.

I appreciate your transparency—that’s what led me to you in the first place during my research. Please be sure to keep it up. Again, sorry for being so direct; please don’t read too much into it. But I was actually startled when I read your monthly report.

Further development is extremely important. But it should happen in the workshop, after prototyping and testing… and not on a running machine.

Most system traders share the following credo regarding robustness:
Keep strategies simple (no overfitting), and instead distribute capital across a few different (preferably uncorrelated) strategies = robustness
1
Imagen de perfil
2Semana
The point here is not higher for longer, but the fear of debasement trade. On that though you have gold and BTC already included. Why then shorting long-term bonds?
Imagen de perfil
2Semana
@GiCi The idea is simple: Include assets in the model that are as uncorrelated as possible and have the potential for long-term upward trends. -3xTLT could be a good fit for this.
Usuario eliminado
2Semana
Comentario eliminado
Mostrar respuesta
Únase a la conversación