

What This Showdown Is Really About
We’re all familiar with the obvious showdown:
Mounjaro versus Ozempic in the diabetes market and—more specifically—Zepbound versus Wegovy in obesity treatment.
That’s exactly why I want to keep this section deliberately brief this time.
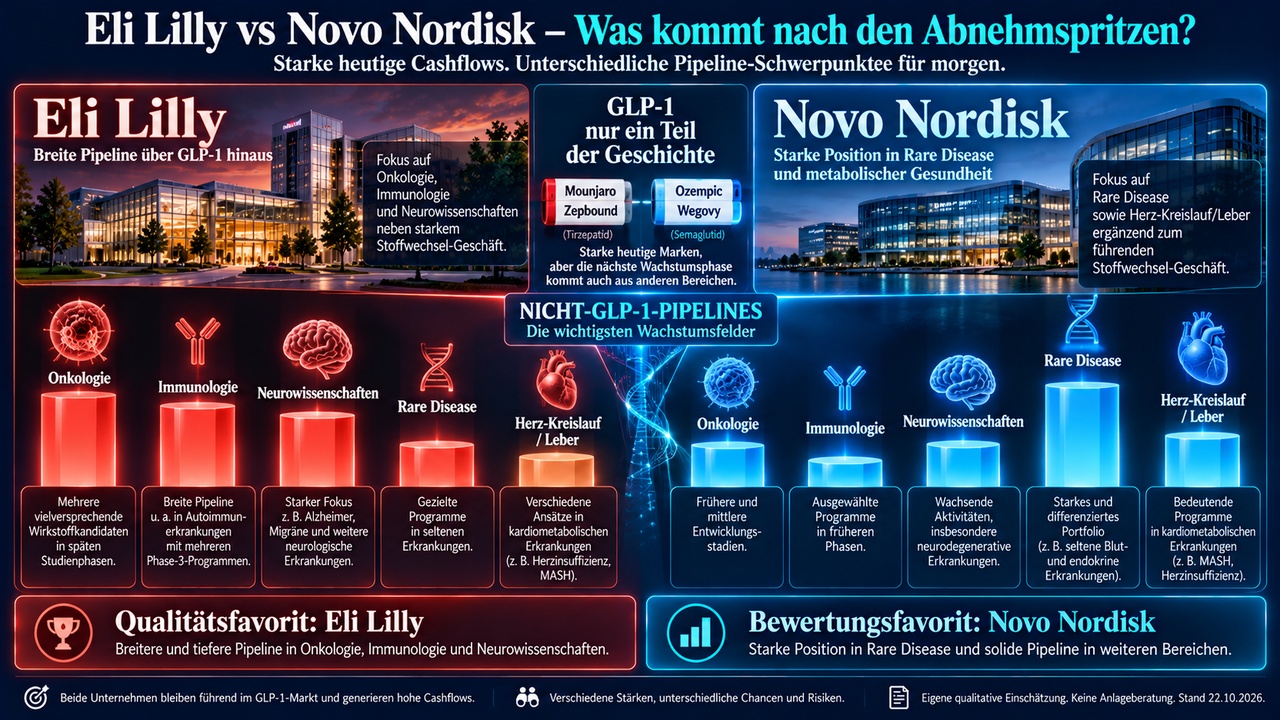
What’s more interesting is the question of what will remain of both companies if we mentally set aside their best-known GLP-1 brands.
- What second revenue pillar already exists?
- Which pipeline could drive the next growth story in five or ten years?
- And how much of that are we already paying for today?
The result is more exciting than it seems at first glance.
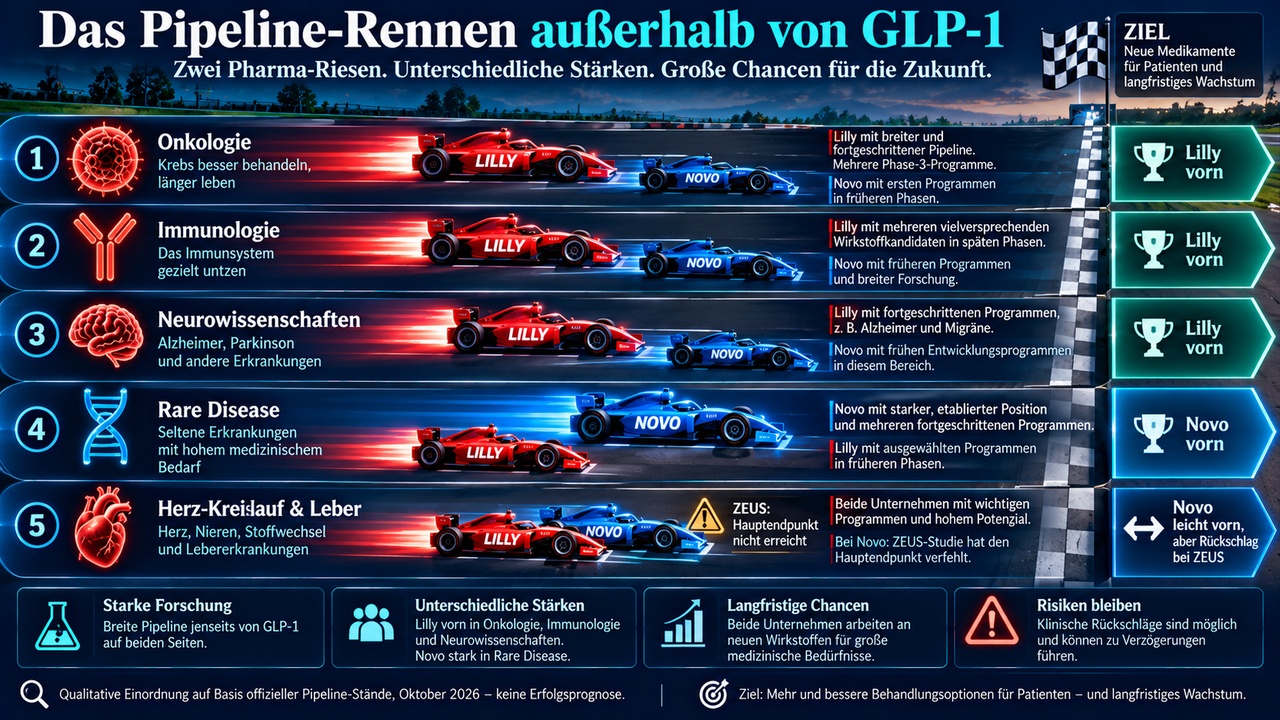
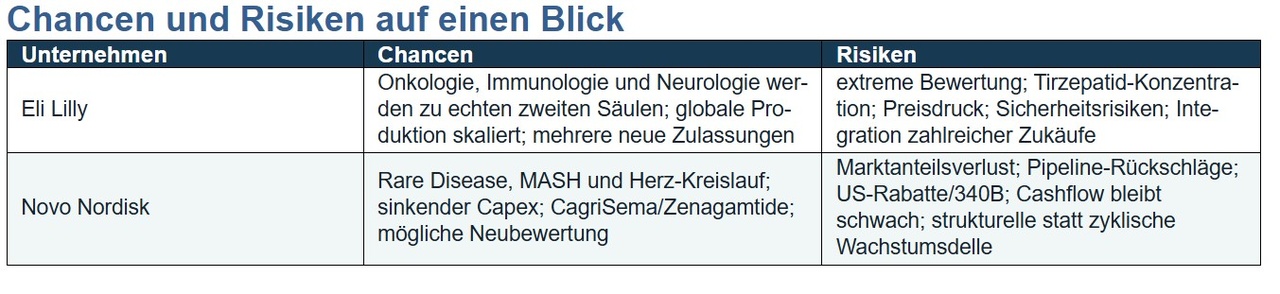
Lilly $LLY (+0,34 %) now has a broad portfolio beyond tirzepatide, spanning cancer drugs, immunology, and neuroscience.
Novo
$NOVO B (-1,1 %) , on the other hand, has a strong but smaller rare-disease franchise and is also focusing on liver and cardiovascular projects.
Operationally, Lilly is clearly more dynamic at the moment. When it comes to the stock price, however, the situation is exactly the opposite.
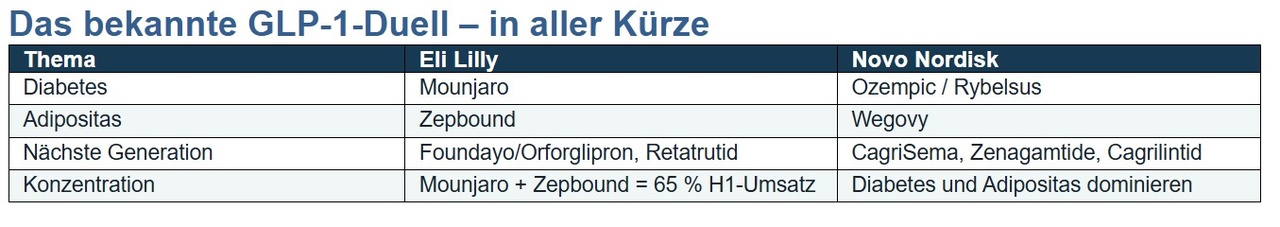
Lilly is growing faster and gaining market share. Novo, on the other hand, has decades of experience, a massive global reach, and new oral or higher-dose formulations. However, both remain heavily dependent on pricing, reimbursement, safety, and production capacity. That’s why the quality of the rest of the pipeline is so important.
Eli Lilly Beyond GLP-1
In my view, Lilly is strongest in oncology. Verzenio has long been established.
Added to this are Jaypirca, Retevmo, and Inluriyo. In September 2026, Inluriyo received full approval in combination with Verzenio, and in October, Jaypirca’s approval was expanded to include certain previously untreated CLL/SLL patients.
At the same time, Lilly is developing Sofetabart mipitecan, an antibody-drug conjugate candidate for ovarian cancer, and Olomorasib, a KRAS G12C inhibitor for lung cancer. This is not a single beacon of hope, but rather a whole range of independent options.
Revenue is already being generated in immunology as well. Taltz, Ebglyss, Omvoh, and Olumiant target various inflammatory diseases. Omvoh recently met the primary Phase 3 endpoint for pediatric colitis, and Olumiant was expanded in 2026 to treat severe alopecia areata in patients aged 12 and older. In neuroscience, Kisunla for Alzheimer’s is still in its early commercial stages but, together with prevention studies, pain and sleep projects, and genetic approaches to Parkinson’s and hearing loss, opens up another field.
The downside is the cost of this breadth. Lilly is aggressively acquiring platforms and projects. In the first half of 2026, acquired research projects weighed on profits by approximately $3.36 billion. Not every acquisition will succeed. The pipeline is broad, but capital allocation and integration are becoming an increasingly important part of the investment thesis.
Novo Nordisk Beyond Semaglutide
Novo’s most credible second pillar is rare blood and hormonal disorders. NovoSeven, Esperoct, Refixia, Alhemo, Rivfloza, Norditropin, and Sogroya are not fantasy projects, but an existing business.
Denecimig has been filed in key markets, Etavopivat has completed Phase 3 trials for sickle cell disease, and Zaltenibart expands the pipeline to include another blood disorder.
In addition, Novo is seeking to expand its presence in liver and cardiovascular diseases. Efruxifermin is in Phase 3 for MASH. Coramitug is in Phase 3 for ATTR cardiomyopathy, and CDR132L is in Phase 2 for heart failure.
The potential is there, but recent setbacks call for caution: Ziltivekimab missed the primary endpoint in the ZEUS trial; in Q2 2026, Novo wrote down DKK 6.3 billion in pipeline assets, of which DKK 4 billion was attributed to Monlunabant.
The Capital Markets Day in September 2026 sets an ambitious goal: more than five multi-blockbusters by 2030 and over 150 billion DKK in risk-adjusted pipeline revenue by 2035. That would represent the desired diversification. Unlike Lilly, however, Novo still has to prove a larger portion of this.
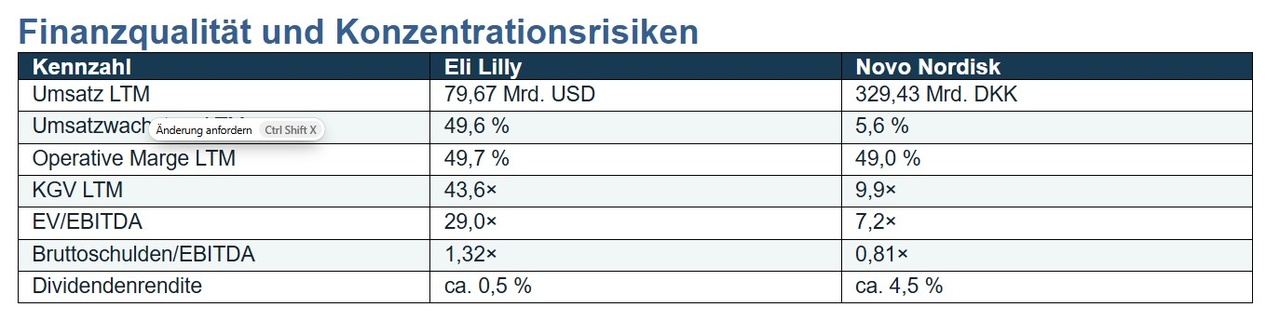
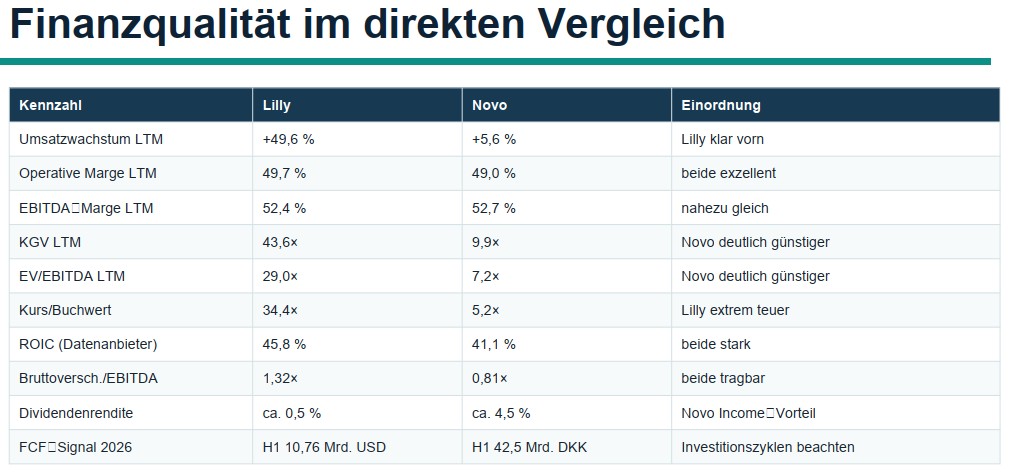
In terms of margins, both companies are surprisingly close to each other.
The big difference lies in growth and valuation. Lilly delivers nearly 50 percent LTM revenue growth and is priced accordingly.
Novo is barely growing anymore and is valued almost like a mature value stock. With Lilly, you’re buying expectations; with Novo, you’re buying the hope of stabilization.
Both companies are also dependent on a few large U.S. wholesalers.
At Lilly , the three largest wholesalers accounted for 16 to 24 percent of consolidated revenue.
At Novo , three U.S. wholesalers accounted for 23, 18, and 14 percent of global revenue.
This is less a classic default risk than an indication of bargaining power, discounts, and the significance of the U.S. reimbursement structure.
Balance Sheet, Cash Flow, and Dividend
As of the first half of the year, Lilly had approximately $54.9 billion in gross debt and approximately $9 billion in cash. H1 cash flow from operating activities was $16.02 billion; after capital expenditures of $5.26 billion, free cash flow totaled approximately $10.76 billion.
That’s strong, but at the same time, the company is investing aggressively in manufacturing facilities, research, and acquisitions.
Novo reported DKK 140.1 billion in gross debt and, for H1, free free cash flow of DKK 42.5 billion. For 2026, DKK 35 to 45 billion is expected. The burden stems primarily from the massive capacity expansion.
If this investment cycle does indeed slow down in the coming years, that will be a significant positive driver. If not, the low P/E ratio will have a more favorable impact than the economic cash flow.
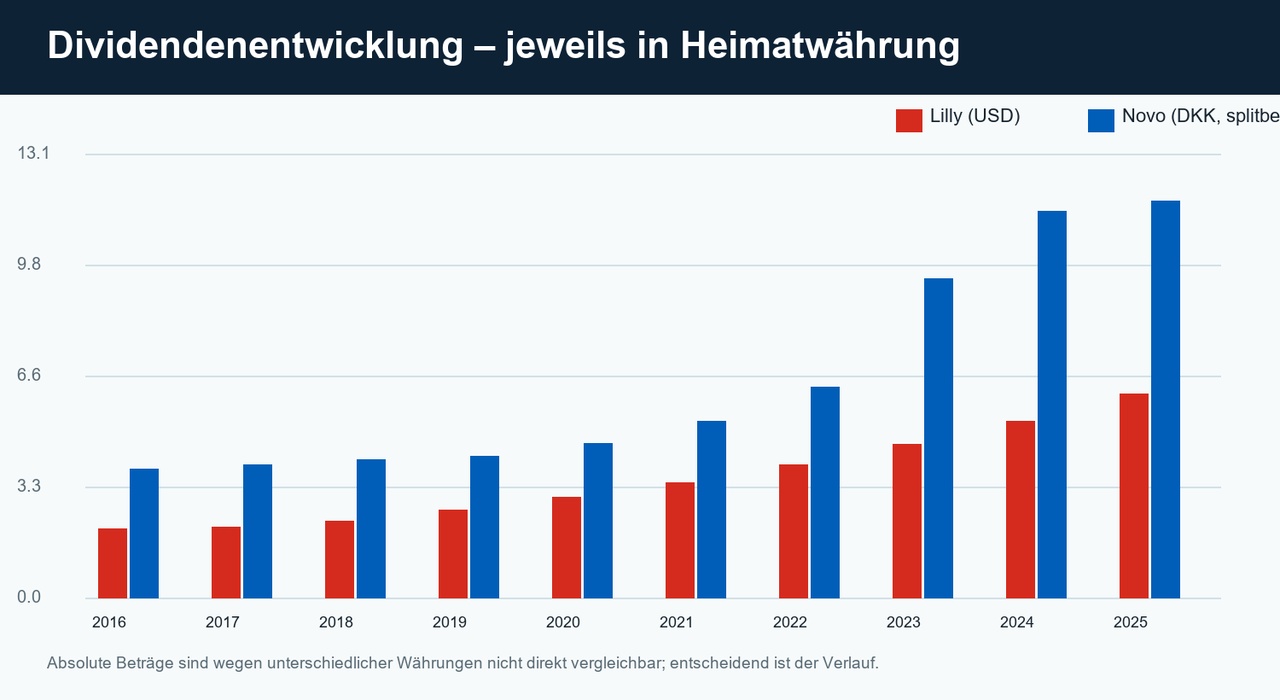
With an annual dividend of 11.70 DKK in 2025, Novo offers a yield of around 4.45 percent at the current price. Lilly’s dividend is growing faster, but due to its high share price, it yields only about 0.5 percent. Investors seeking current income receive a genuine waiting premium with Novo; with Lilly, the price appreciation must account for the bulk of the return.
Valuation: Cheap Doesn’t Automatically Mean a Good Deal
My normalized DCF for Lilly comes to about $570 in the bear case, $1,157 in the base case, and $1,813 in the bull case.
The stock price of around $1,307 is thus above my base-case scenario.
The company can grow into this valuation, but the margin of safety is small.
For Novo, the figures are approximately 107 DKK in the bear case, 235 DKK in the base case, and 483 DKK in the bull case. Here, too, the share price of around 263 DKK is slightly above the base case.
This shows that Novo’s low P/E ratio alone does not automatically make it a bargain. The attractive asymmetry will only emerge once revenue and cash flow stabilize and the pipeline regains investor confidence.
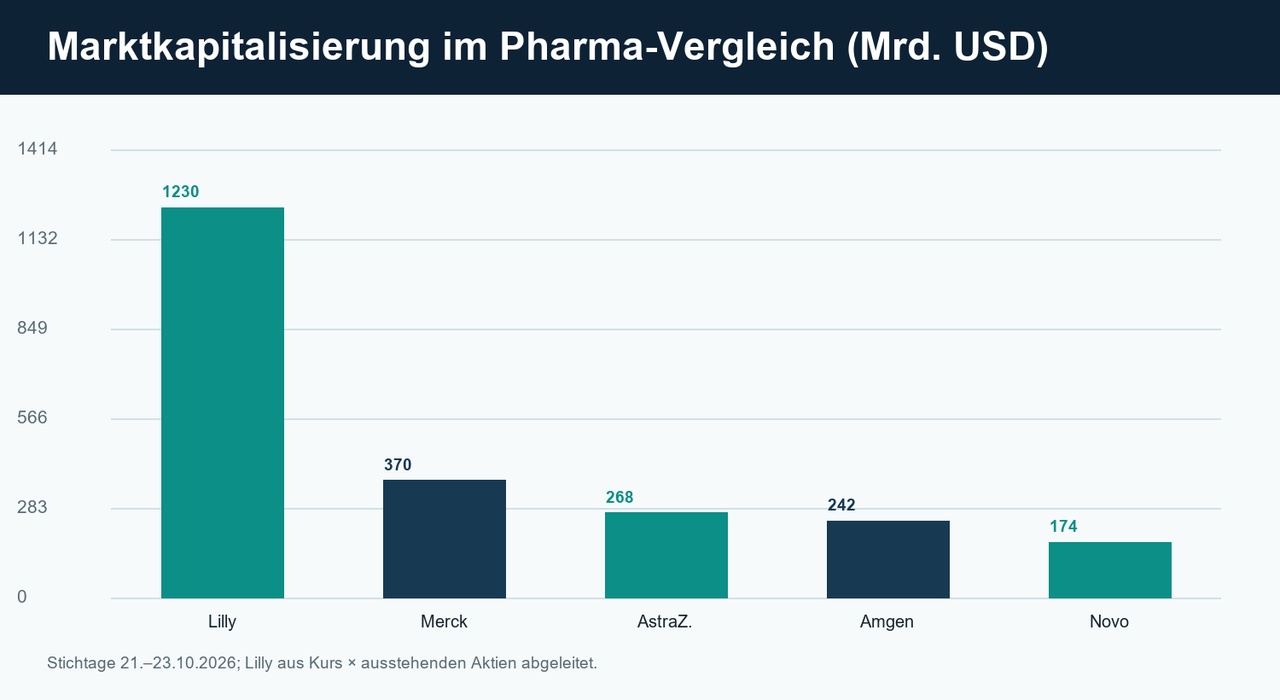
Lilly is now valued higher than Merck, AstraZeneca, Amgen, and Novo combined.
That’s impressive, but it sets the bar extremely high.
Novo, on the other hand, is once again valued like a normal, mature pharmaceutical company.
It is precisely this valuation gap that makes the contest so wide open.
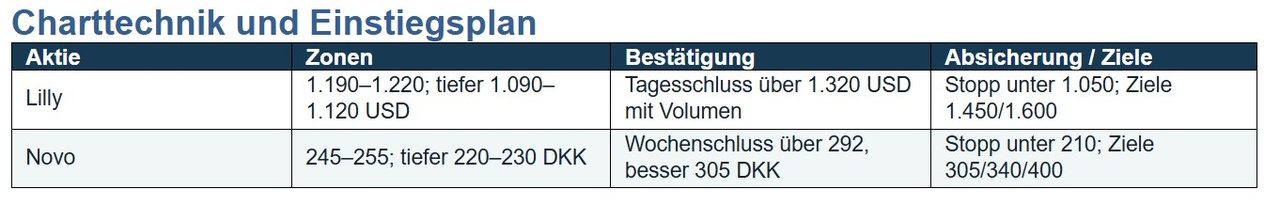
Lilly is overbought in the short term on the daily chart:
The RSI is around 70, the price is trading above key moving averages and at the upper Bollinger Band. The trend is strong, but the risk-reward ratio at the high is unfavorable.
Novo is showing signs of bottoming out on the daily chart, but remains below the 50-day and 200-day EMAs on the weekly chart. I’d like to see a confirmed retake of those levels first.
AI: Useful, but Not a Moat in Its Own Right
Both companies can use AI in drug discovery, study design, patient selection, production, and demand planning.
However, I wouldn’t make this a separate investment case. AI reduces search costs, but it does not replace clinical efficacy, safety, regulatory approval, or industrial manufacturing.
Lilly has more areas of application due to its larger pipeline;
Novo can scale its narrower focus more easily.
I consider the direct risk of disruption from AI to be low for both companies.
My Final Verdict
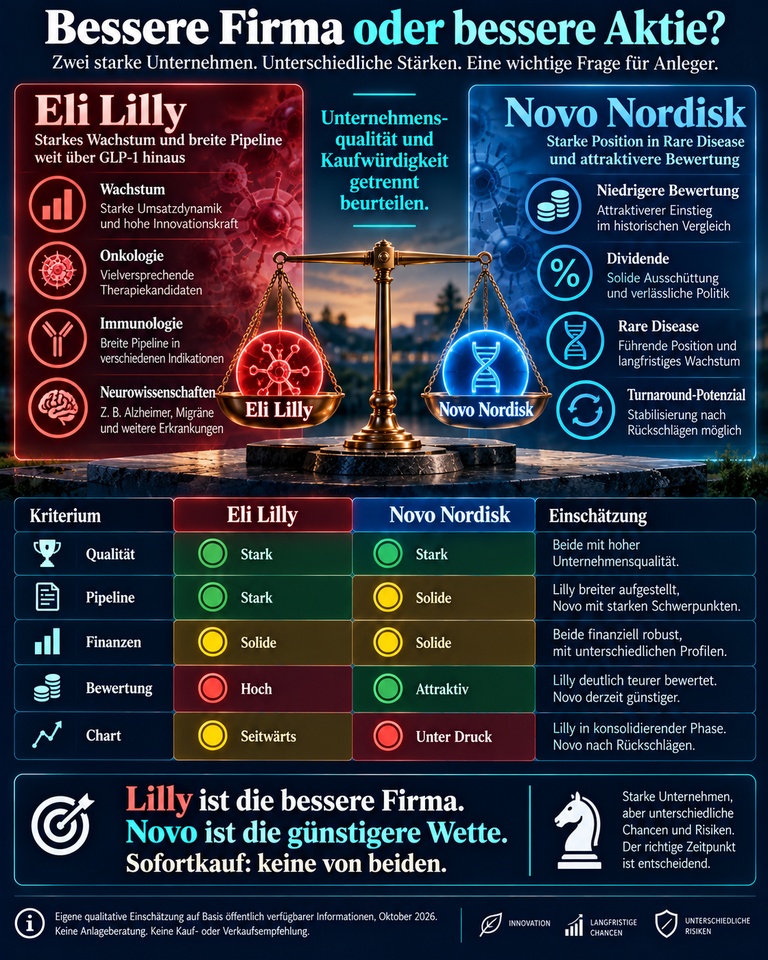
Eli Lilly wins the head-to-head comparison in my view.
The company has a significantly broader portfolio outside of GLP-1, brings new products to market faster, and has several realistic growth pillars.
Novo Nordisk, on the other hand, wins the valuation showdown.
Expectations are much lower, the dividend offers a reward for patience, and even a stabilization could be enough to positively surprise the market.
Still, I wouldn’t buy Novo blindly. The long-term chart is still damaged, and the pipeline needs to regain credibility after recent setbacks.
With Lilly, I wouldn’t bet against the trend, but I wouldn’t chase the price either.
My preferred approach would therefore be:
Buy Novo in small, staggered increments after confirmation; put Lilly on the watchlist for a significant pullback.
What do you think?
Is Lilly’s broad pipeline worth the enormous premium—or is Novo the more interesting turnaround bet after its crash?
I’m particularly interested in your assessment of the non-GLP-1 programs, because that’s exactly where it’s likely to be decided who really wins the duel in five years.
Greetings from NoVo Land, Denmark :)
Raketentoni
Sources, Assumptions, and Disclaimer
Primary Sources and Data Set
● Eli Lilly Q2 2026 Results, August 5, 2026 –
investor.lilly.com/news-releases/news-release-details/lilly-reports-second-quarter-2026-financial-results-raises-full
● Eli Lilly Q2 2026 Form 10-Q – sec.gov/Archives/edgar/data/59478/
● Eli Lilly 2025 Form 10-K – sec.gov/Archives/edgar/data/59478/000005947826000013/lly-20251231.htm
● Lilly R&D Pipeline, as of August 5, 2026 – lilly.com/discovery/clinical-development-pipeline
● Lilly Dividend History – investor.lilly.com/stock-information/dividends-splits
● Novo Nordisk Q2 2026 / Investor Presentation, August 4, 2026 – novonordisk.com/investors/financial-results.html
● Novo Nordisk Annual Report 2025 – annualreport.novonordisk.com/2025/
● Novo R&D Pipeline – novonordisk.com/science-and-technology/r-d-pipeline.html
● Novo Capital Markets Day 2026, September 21, 2026 –
novonordisk.com/news-and-media/news-and-ir-materials/news-details.html?id=916773
● Investing.com Pro Research Reports from October 22–23, 2026, and four chart screenshots from October 23, 2026.
● Market capitalizations: CompaniesMarketCap / StockAnalysis, October 21–23, 2026; Lilly’s figure additionally validated using price × number of shares
.
DCF assumptions: ten explicit years, followed by Gordon Growth. The scenarios are intentionally broad. WACC, terminal growth rate, normalized FCF,
debt, and number of shares are assumptions and not company forecasts.
DISCLAIMER
This document is intended solely for informational and discussion purposes. It is
not investment advice, nor is it an offer or solicitation to buy or sell
securities. Prices, estimates, and pipeline assumptions are subject to change at short notice
and, of course, all others :)


