
Deutsche Telekom exceeded expectations in the third quarter of 2026 and raised its full-year forecast slightly for the third time. Revenue rose 7.5% to 31.1 billion EUR, adjusted EBITDA AL increased 9.9% to 12.2 billion EUR, and free cash flow AL rose 1.4% to 5.7 billion EUR — According to Dow Jones, analysts had expected only EUR 30.38 billion, EUR 11.96 billion, and EUR 5.41 billion, respectively. For 2026, shareholders are set to receive a dividend of 1.10 EUR per share—10% more than the previous year—along with a share buyback of up to 2 billion EUR in 2027. The catch: The forecast is rising by only EUR 0.1 billion in each case; the market had hoped for a more substantial dividend increase; the domestic growth is also benefiting from the World Cup; and concerns about a full merger with T-Mobile US are resurfacing. Nevertheless, the stock reacted with losses: On Xetra, it was trading at EUR 26.18 on the morning of November 5, 2026, about 2.2% below the previous day’s closing price of EUR 26.76. From a technical analysis perspective, the stock remains below the downtrend line that has been in place since its multi-year high of 35.91 EUR—only a dip to 23.50 EUR or a breakout above 27 EUR would be a trigger for me; the target remains 29.50 EUR.
Key Points
- Q3 2026: Revenue of 31.1 billion EUR (+7.5%), adjusted EBITDA AL of 12.2 billion EUR (+9.9%), free cash flow AL of 5.7 billion EUR (+1.4%)
- All three metrics exceeded consensus estimates (30.38 / 11.96 / 5.41 billion EUR according to Dow Jones)
- 2026 Forecast: Adjusted EBITDA of approximately 47.6 billion EUR (previously 47.5), adjusted free cash flow of approximately 20.1 billion EUR (previously 20.0), EPS of approximately 2.20 EUR (unchanged)
- Dividend for 2026: EUR 1.10 (+10%), share buyback of up to EUR 2 billion in 2027
- Analysts: Average price target around 35.20 EUR, range 28.10 to 40.00 EUR
- Chart levels: downside risk to 23.50 EUR, trigger above 27 EUR, target 29.50 EUR – no immediate action required
What are the current key metrics for the Telekom stock?
On November 5, 2026, the Telekom stock is trading on Xetra at 26.18 EUR (−2.2%, 10:19 a.m.), which is about 24% below its 52-week high of 34.36 EUR.
Based on the adjusted EPS target of approximately 2.20 EUR, the 2026 P/E ratio stands at around 11.9; the proposed dividend of 1.10 EUR corresponds to a yield of approximately 4.2%.
What news is currently driving the Telekom stock?
Telekom shares are currently being driven primarily by the Q3 results released on November 5, 2026, which exceeded expectations but still failed to make an impact on the stock market.
Revenue, adjusted EBITDA AL, and free cash flow beat the consensus, and the dividend is rising by 10% to 1.10 EUR. According to traders, hopes for a larger dividend increase and resurgent concerns about a full merger with T-Mobile US are weighing on the stock. Lurking in the background is also the SpaceX shock from October: I’ll show just how much potential this new mobile communications rival from Musk’s company really has in my analysis of SpaceX Aktie.
What does Telekom’s management say about the Q3 results?
CEO Tim Höttges sees Telekom clearly in the lead: “With our strong numbers, we’re setting the standard in our industry,” he said during the presentation of the Q3 results.
For years, the company has demonstrated the success of its strategy with impressive results—underpinned by the third forecast upgrade within a year and a record dividend.
What went well: Adjusted EBITDA AL grew by 9.9%, significantly faster than revenue. In Germany, revenue rose by 3.9% to 6.6 billion EUR; Telekom gained 284,000 mobile contract customers and, with 190,000 new fiber-optic customers, reached a record high for a single quarter. The systems business increased order intake by about 28% to EUR 883 million, primarily thanks to the Industrial AI Cloud.
The catch: The forecast has been raised by only EUR 0.1 billion in each case, and adjusted free cash flow grew by just 1.4% in the quarter. The dividend of 1.10 EUR fell short of market expectations. The domestic growth also benefited from the World Cup, so the licensing revenue is not recurring. And there is still no clear answer regarding a full merger with T-Mobile US.
Outlook: For 2026, Telekom now expects adjusted EBITDA AL of approximately EUR 47.6 billion, free cash flow AL of approximately EUR 20.1 billion, and adjusted earnings per share of approximately EUR 2.20, unchanged from previous guidance. A share buyback of up to EUR 2 billion is planned for 2027; the full-year results will be released on February 25, 2027.
What does Deutsche Telekom do—and how does it make its money?
Deutsche Telekom is Europe’s largest telecommunications group and generates most of its revenue from mobile, landline, and broadband services—the majority of which comes from the U.S.
The DAX-listed company, headquartered in Bonn, is led by CEO Tim Höttges and holds more than half of T-Mobile US. In the third quarter of 2026, Deutsche Telekom generated EUR 31.1 billion in revenue and EUR 12.2 billion in adjusted EBITDA AL.
U.S. (T-Mobile US): The biggest value driver. In the third quarter, the segment’s revenue rose 7.5% to $23.6 billion, and adjusted EBITDA AL increased 11.4% to $9.4 billion. T-Mobile US added 274,000 postpaid accounts, bringing its total to approximately 35 million postpaid accounts.
Germany: Mobile, fixed-line, broadband, and fiber optics. Revenue of EUR 6.6 billion (+3.9%), adjusted EBITDA AL of EUR 2.8 billion (+1.5%), 78.7 million mobile customers.
Europe: National subsidiaries in Poland, Austria, and Greece, among others, with revenue of EUR 3.3 billion (+4.2% organic) and adjusted EBITDA AL of EUR 1.3 billion.
Systems Business (T-Systems): IT and cloud solutions for business customers, with revenue of EUR 1.1 billion and new orders of EUR 883 million (+28%).
Fundamental Analysis: Is the Telekom stock undervalued following the Q3 results?
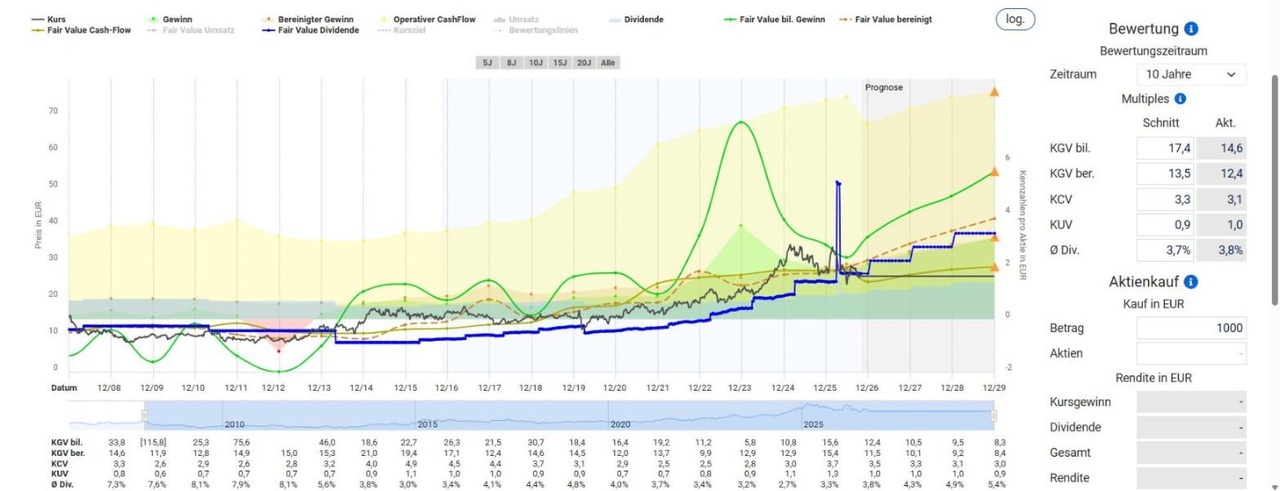
From a fundamental perspective, the Telekom stock appears more affordable than expensive following the Q3 results: According to Aktienfinder, the adjusted P/E ratio stands at 12.4, which is below the 10-year average of 13.5.
Based on the confirmed EPS target of approximately 2.20 EUR, I arrive at a 2026 P/E ratio of around 11.9 at the current price. The dividend yield, at around 4.2% for the proposed EUR 1.10, is above the 10-year average of 3.7%.
Growth and Margins: After nine months, revenue rose by 4.1% to EUR 90.9 billion, and adjusted EBITDA AL increased by 6.4% to EUR 35.6 billion. Earnings are thus growing faster than revenue, and the margin is increasing. Adjusted net income rose by 12.7% to EUR 3.0 billion in the third quarter.
Cash Flow and Dividends: Free cash flow AL stood at EUR 16.4 billion (+1.7%) after nine months; Telekom is targeting around EUR 20.1 billion for the full year. The Group will use this to finance the dividend of EUR 1.10 and the buyback of up to EUR 2 billion in 2027. Anyone specifically looking for reliable dividend payers on the DAX should also check out my analysis of Münchener Rück Aktie —it shows how the stock market rewards strong dividend performance.
]
The Discount: Despite the figures, a valuation discount remains. Exchange rates are weighing on the U.S. earnings converted into euros, debt levels are high, and the unresolved question of a full merger with T-Mobile US is keeping investors at bay. As long as these issues remain unresolved, I do not expect a rapid revaluation.
Telekom Stock Price Targets and Forecast for 2026
On average, analysts see a price target of around 35.20 EUR for the Telekom stock, representing upside potential of about 34%.
Based on eight analyses, finanzen.net arrives at 35.22 EUR; six of the seven current brokerages recommend buying. Following the earnings report, JPMorgan confirmed its target of 38 EUR; the range extends from 28.10 EUR (Bernstein) to 40.00 EUR (Deutsche Bank). Just how stubbornly a stock can remain trapped below a downtrend line is also illustrated by my analysis of Porsche Aktie.
Key price levels:
- 52-week high: 34.36 EUR (February 2026)
- Current price: 26.18 EUR (Xetra, Nov. 5, 2026, 10:19 a.m., −2.2%)
- Resistance: 27.00 EUR (upper edge of the gray zone around 26.50–27 EUR, bullish trigger)
- Target and resistance: 29.50 EUR (red resistance zone)
- Multi-year high: 35.91 EUR (March 2025, start of the downtrend line)
- Support and critical level: 23.50 EUR (gray support zone, 52-week low of 23.53 EUR on June 30, 2026)
Analyst price targets:
- Average price target: approx. 35.20 EUR (our own calculation based on seven targets; finanzen.net: 35.22 EUR based on eight analyses)
- Deutsche Bank: Buy, 40.00 EUR (October 19, 2026)
- JPMorgan: Overweight, 38.00 EUR (November 5, 2026, confirmed following earnings release)
- Goldman Sachs: Buy, 38.00 EUR (October 5, 2026)
- Berenberg: Buy, 35.20 EUR (October 1, 2026)
- UBS: Buy, 35.10 EUR (October 7, 2026; Buy rating confirmed on November 4, 2026)
- Barclays: Overweight, 32.00 EUR (October 20, 2026)
Bernstein: Market Perform, 28.10 EUR (October 19, 2026
]]
Chart Analysis:
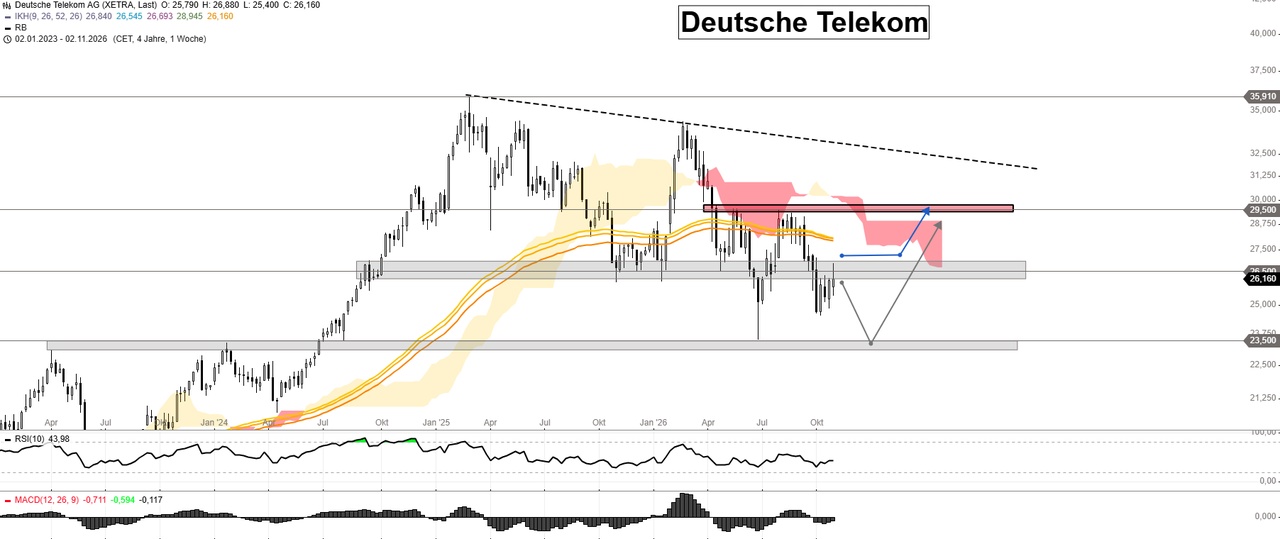
The weekly chart for Deutsche Telekom shows no further momentum—I’m waiting for the triggers. Since hitting a multi-year high of 35.91 EUR in March 2025, the stock has been trading below a downward trend line, and every rally so far has failed at the red resistance zone around 29.50 EUR. Even after the Q3 earnings report, the stock is trading below the gray zone around 26.50 to 27 EUR.
I still see the Telekom stock as vulnerable to a decline toward 23.50 EUR. That’s where the gray support zone lies, at which the stock already turned upward at the end of June. From there, bullish market participants could step in again—that would be the first trigger.
The second trigger lies above: If the stock manages to break above 27 EUR, the path would also be clear. In both cases, my target remains 29.50 EUR.
What’s important to me here is this: At present, I see no need for action and no necessity to buy. Only when one of the two triggers is met—a buy at 23.50 EUR or a breakout above 27 EUR—will a setup with a clear direction emerge for me.
Opportunities and Risks of the Telekom Stock
Opportunities:
- ✅ Q3 figures above consensus for revenue, adjusted EBITDA, and free cash flow
- ✅ Third forecast upgrade: EBITDA AL approx. 47.6 billion EUR, FCF AL approx. 20.1 billion EUR
- ✅ Dividend of 1.10 EUR (+10%, yield approx. 4.2%) plus a buyback of up to 2 billion EUR in 2027
- ✅ T-Mobile US is growing: Adjusted EBITDA +11.4%, forecast raised
- ✅ Attractive valuation: 2026 P/E ratio approx. 11.9, adjusted below the 10-year average
- ✅ Average price target approx. 35.20 EUR, trigger above 27 EUR with a target of 29.50 EUR
Risks:
- ⚠️ Forecast revisions of only EUR 0.1 billion each
- ⚠️ Free cash flow (AL) up only +1.4% for the quarter
- ⚠️ Domestic growth partly driven by World Cup effects
- ⚠️ Uncertainty regarding a full merger with T-Mobile US
- ⚠️ SpaceX as a potential new competitor in the U.S. mobile market
- ⚠️ Downward trend from 35.91 EUR remains intact; risk down to 23.50 EUR
Conclusion: Telekom Stock – Dividend Up 10%, but Where’s the Trigger?
The Telekom stock is delivering on the operational front, but from a technical chart perspective, the trigger is still missing—I’ll stay on the sidelines until it holds at 23.50 EUR or falls to 27 EUR.
Revenue, adjusted EBITDA AL, and free cash flow exceeded expectations in the third quarter; the forecast was raised for the third time, and the dividend is increasing to 1.10 EUR. The fact that the stock is still falling shows just how high expectations were: the upward revision is minimal, the dividend fell short of hopes, and the merger issue with T-Mobile US is weighing on the stock.
With a P/E ratio of around 11.9, a dividend yield of around 4.2%, and an average price target of around 35.20 EUR, the stock is not expensive from a fundamental perspective. From a technical analysis perspective, the plan is clear: Below the downtrend line, it remains at risk of further declines toward 23.50 EUR, where the bulls could step in again. Alternatively, a breakout above 27 EUR would signal the start of an uptrend. In both cases, 29.50 EUR is my target—though no immediate buy action is warranted at this time.
Anyone who prefers to invest in a DAX-listed company that focuses on growth rather than dividends should read my analysis SAP Aktie —there, the cloud will determine the next price wave.
Sources
- Deutsche Telekom Press Release: More Growth, Raised Forecast, Record Dividend (November 5, 2026)
- Deutsche Telekom Investor Relations: Financial Calendar
- Dow Jones via finanzen.net: Telekom Slightly Raises Annual Forecast, Including Consensus (November 5, 2026)
- dpa-AFX via FinanzNachrichten.de: Frankfurt Stock Market Opening, Telekom Share Price Reaction (November 5, 2026)
- dpa-AFX Analyser via FinanzNachrichten.de: JPMorgan Maintains “Overweight” Rating on Telekom, Target Price of 38 EUR (November 5, 2026)
- wallstreet-online via FinanzNachrichten.de: The Hidden Disappointment (November 5, 2026)
- Reuters via TradingView: Telekom Raises 2026 Forecast and Plans Share Buyback (November 5, 2026)
- T-Mobile US: Third-Quarter 2026 Results (SEC Form 8-K, Oct. 28, 2026)
- finanzen.net: Deutsche Telekom Analyst Price Targets
- FinanzNachrichten.de: Analyst Ratings for Deutsche Telekom
- Business Punk, citing Bloomberg and Handelsblatt: Elliott and the merger plans (September 3, 2026)
- Deutsche Börse: Xetra price, daily range, and 52-week range for Deutsche Telekom
- Xetra price for Deutsche Telekom, November 5, 2026, 10:19 a.m.: 26.18 EUR (Deutsche Börse), dpa-AFX 9:48 a.m.: 26.175 EUR (−2.19%)
- Alpha Vantage: Daily and weekly prices for Deutsche Telekom (DTE.DEX, Xetra) and T-Mobile US (TMUS)
- Stock3: Weekly chart for Deutsche Telekom (Xetra, EUR), as of November 5, 2026
- Aktienfinder: Fair value calculation and valuation metrics for Deutsche Telekom, as of November 5, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What do you currently think of $DTE (+0,67 %)?
