

Let's see what happens in 3 months.

Hoegh Autoliners
Stock
Stock
ISIN: NO0011082075
Ticker: HAUTO
NO0011082075
HAUTO
Price
Debate sobre HAUTO
Puestos
116


3D·
Monthly Review 09/2026
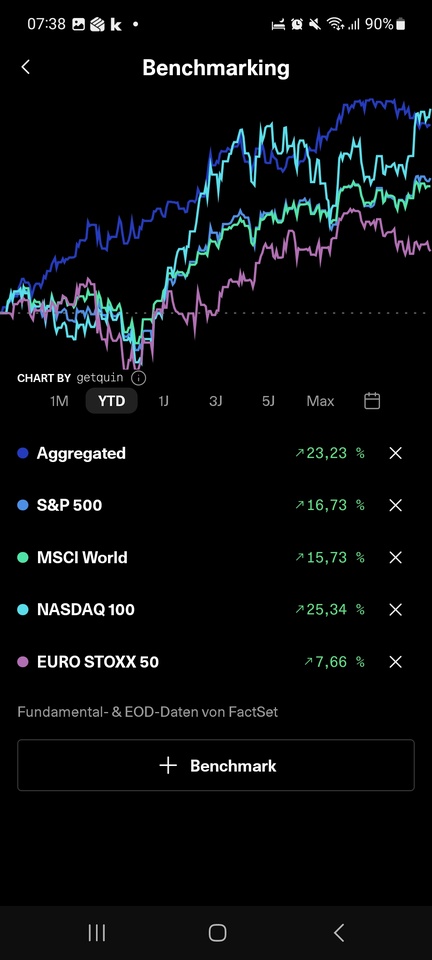
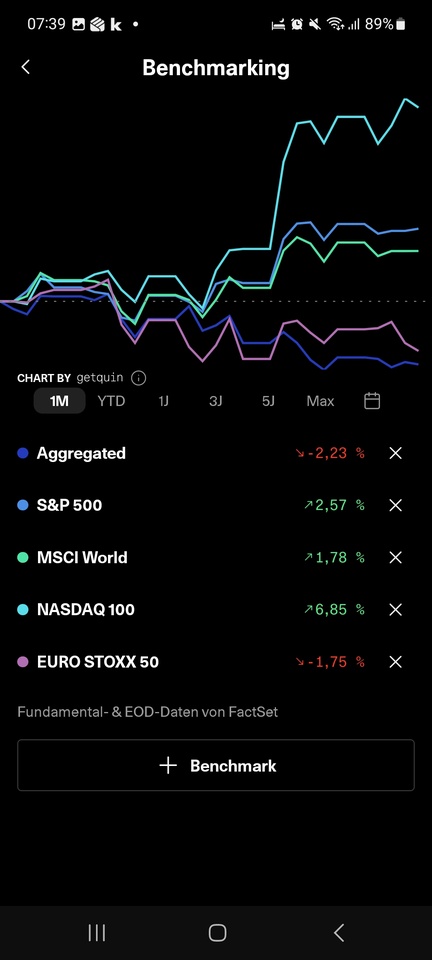
Another quarter is behind us, and after this past 🦘 month, I find it amusing to note that this year, it seems the last month of every quarter always ends up in the red...
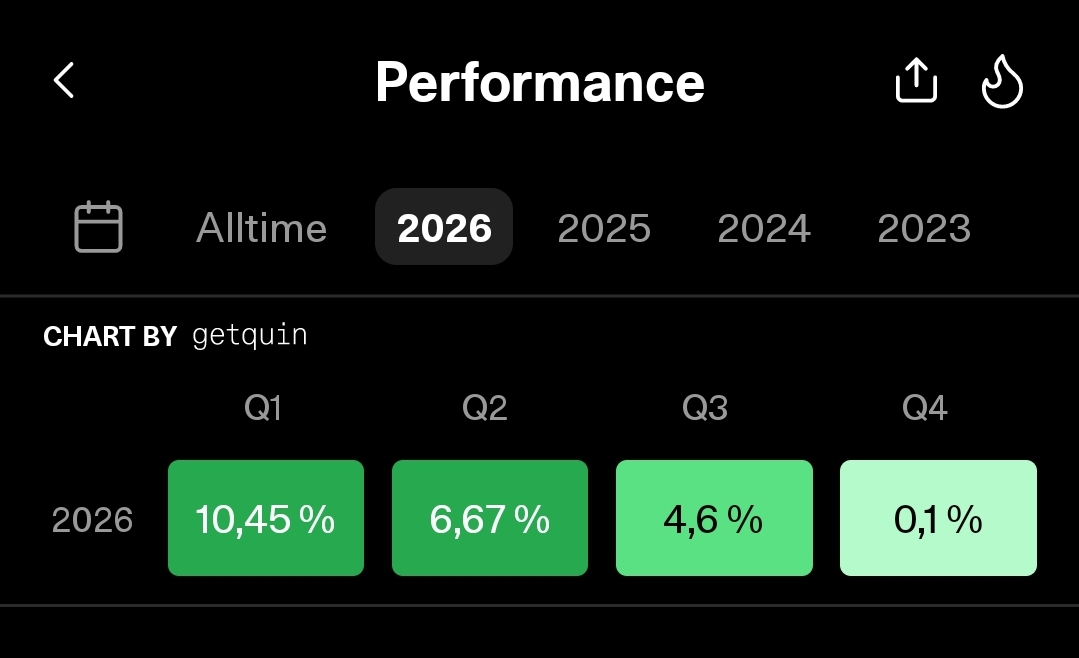
But that doesn’t really bother me right now, because when viewed on a quarterly basis, everything still fits well into the overall picture...
...and from an annual perspective, things aren’t looking too bad so far either...
...for a relatively conservative, dividend-focused portfolio that isn’t heavily weighted toward tech, so everything’s still within reason...
...and from a long-term perspective, everything continues to fit into the overall strategy.
Sure, things can always go better, faster, higher, and further, but considering the resources and the overall conditions, everything is perfectly within the target range 🫠
》DIVIDENDS《
Despite the pesky taxes, this month still yielded €215.63 in net dividends, corresponding to a YOC of 6.28 (target range between 6–7%).
》TOP 3《
$HAUTO (+0,82 %) + 9.89% (+147.82%)
$ASWM (+0,91 %) +4.31% (+24.81%)
$VAR (+0,51 %) +0.86% (+70.93%)
》FLOP 3《
$AII (+0,71 %) -19.10% (+19.85%)
$3750 (+2,58 %) -16.85% (+87.16%)
$DTE (+0,87 %) -8.15% (-4.61%)
》 NEW ADDITIONS 《
43.95 x $WINC (+1,08 %)
24 x $AII (+0,71 %)
10 x $MUX (+1,93 %)
1 x $MUV2 (+0,2 %)
》DISPOSALS《
----
》CONCLUSION《
Everything remains the same, except that the final certification (DATEV LuG) is still pending this month, and with the change of the month, we’ll also have to complete the move into our new apartment.
With that in mind, things continue to be exciting, so I wish you and your portfolios all the best 👍🏻
+ 1
3434
1 Comentario
I think the performance is really impressive. It's awesome. Congratulations. 🙂
•
99
•
1Lun·
HÖEGH AUTOLINERS +100% AND I DON'T SEE AN END IN SIGHT 🚀
Sometimes it’s not the well-known tech giants that make the most exciting stories in your portfolio.
For me, it’s currently a company that many probably don’t even have on their radar: Höegh Autoliners.
My position is now up over 100%—and that’s despite a dividend yield that makes many people do a double-take at first.
But that’s exactly where it gets interesting:
Höegh doesn’t just transport cars. The company is at the center of a structural shift in the global automotive trade.
China is exporting more and more vehicles worldwide. In the first half of 2026, Chinese vehicle exports were already 66% higher than the previous year. At the same time, available RoRo capacity is becoming scarcer, and Höegh reports that its fleet is operating at full capacity. (Höegh Autoliners)
At first glance, the Q2 figures were weaker:
- $376 million in revenue
- $122 million in EBITDA
- $86 million net income
However, the reason is significant: high fuel costs and geopolitical upheavals in the Middle East have weighed on earnings. The fuel effect alone cost approximately $22 million in the quarter. (Investing.com)
And that’s exactly why I find the current situation exciting.
Because if these one-time costs subside, while exports to China continue to grow and market capacity remains tight, the company could $HAUTO (+0,82 %) continue to offer an attractive combination of cash flow, dividends, and growth.
The company itself expects the BAF/fuel surcharge to return to normal over the course of Q3. At the same time, charter rates for the industry have risen significantly. (thedcn.com.au)
For me, Höegh is therefore not a stock I hold solely for the dividend.
I see this as a bet on a long-term trend:
More Chinese vehicles + more global vehicle transport + tight shipping capacity = an interesting starting point for a specialized player.
Of course, shipping remains a cyclical industry. The dividend isn’t guaranteed, and high payouts can fluctuate.
But that’s exactly what makes the stock interesting to me.
+100% price gain realized.
Dividends collected.
And yet the position remains in my portfolio.
Now I’m curious:
Which of you are also invested in Höegh Autoliners—and do you hold the stock for the dividend or for the long-term story?
#HöeghAutoliners
#HAUTO
#Dividendenaktien
#Dividende
#Aktien
#Investieren
#Börse
#China
#Autowerte
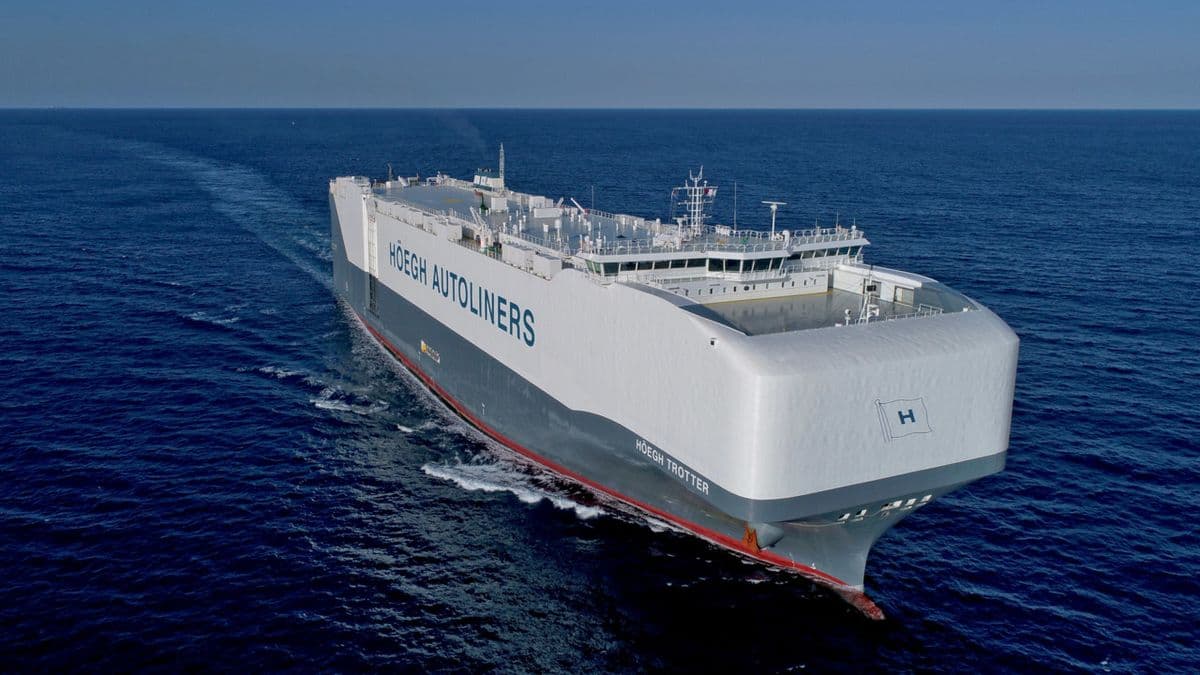
www.hoeghautoliners.comHoegh Autoliners
2222
8 Comentarios
1Lun
I've been with Höegh for 1.5 years now and am up 105%. I invest a small monthly savings plan as well as my Trade Republic round-up. Dividends also keep coming back. Top company...
•
55
•
1Lun·
After the sale is before the purchase
$HAUTO (+0,82 %) It's out…
What should I put in now? 🤔
Hoegh actually was a pretty good fit for my portfolio (logistics sector)
So now, maybe $MAERSK A (-0,9 %) or $HLAG (-1,81 %) add it?
So many questions…
GaLiGrü
66
4 Comentarios•
22
•
1Lun·
Hoegh Autoliners Reports Financial Results and Significantly Reduces Its Dividend
Hoegh Autoliners $HAUTO (+0,82 %) released its latest quarterly results today and announced the amount of its next cash dividend. Investors aren’t happy about this for now, and the stock is down significantly in early trading.
Although revenue and EPS exceeded expectations, Hoegh is struggling with its operating performance. High fuel costs and the impact of the Iran conflict are putting significant pressure on margins.
What will upset many even more is that Hoegh has drastically cut its dividend to just $0.0839. The company hopes this will allow it to keep more cash on its balance sheet.
The dividend cut at Hoegh Autoliners isn’t just a cosmetic move; rather, it changes the earnings logic quite significantly. If this continues, it would fundamentally alter the investment thesis for many.
What do you think? A one-time blip in the dividend. Sell? Or wait and see if improvement is in sight? The outlook for the next quarter is relatively subdued; results are expected to remain roughly flat.
1616
23 Comentarios
I posted 1 minute before you 😬 but deleted it; here’s my opinion:
I see this more as a temporary strain, but not as a guaranteed one-time slip-up.
The business remains profitable, and demand for Ro-Ro transport remains strong, according to the company. The main causes were high fuel costs, rerouting due to the Middle East conflict, and a delay in passing these costs on to customers.
Over the course of the third quarter, cost recovery is expected to take full effect again, and cash conversion should normalize. However, Höegh initially expects Q3 EBITDA to be roughly on par with the weak second quarter. A quick return to the previously high dividends is therefore by no means certain.
My conclusion: no fundamental collapse, likely temporary in part—but the dividend remains highly volatile and dependent on free cash flow. Q3 and Q4 will be decisive.
Only when cash flow and dividends rise significantly again can we speak of a genuine one-time blip.
•
99
•
1Lun·
De-risk my portfolio
$HAUTO (+0,82 %) I have a 2100 shares position in HOEGH and think about selling it completely at 200 NOK because it has grown to 13% of my portfolio. I want to reinvest 10.000 euro in $WINC (+1,08 %) and the rest in $LDGL (+0,35 %) to have stable dividend growth. Is there a flaw in my thinking or should I keep this cyclical stock but a winner so far?
44
6 Comentarios1Lun
Dividends and Growth: You Can Have One Without Sacrificing the Other
••
2Lun·
Monthly Review 07/2026
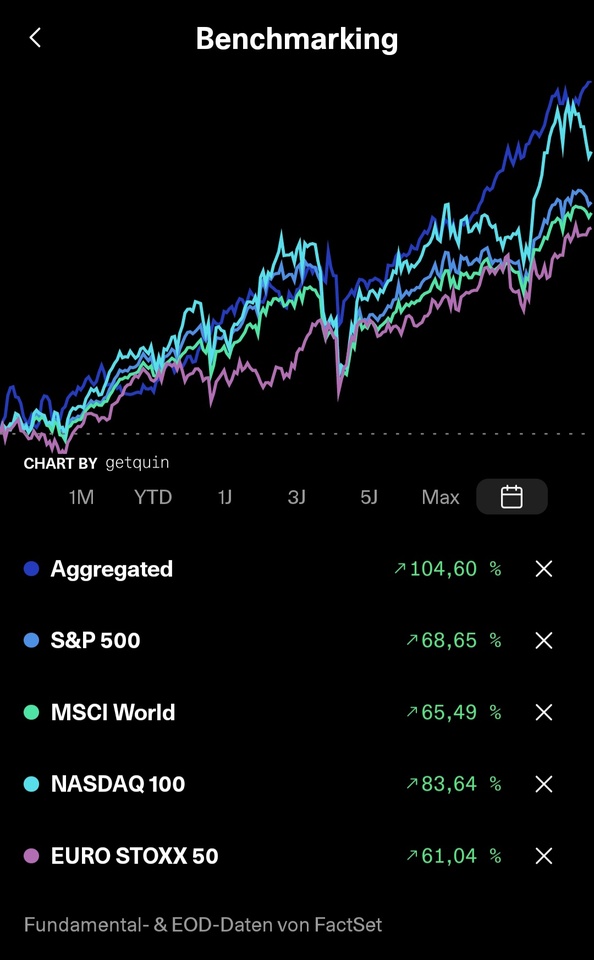
Another month has passed, and it’s time once again to take a quick look into the engine room...
...actually, not much has changed in the big picture, except that after 38 months of consistent performance, the 40k mark has been broken, and so the final sprint of the first half has now begun...
...it’s not a high-flyer portfolio, but so far it’s been a solid growth story, and as the saying goes, every little bit helps...
...which is why YTD hasn’t changed much either...
...nor has it since the very beginning...
...the structure, however, is a different story, and so there were a few changes to the portfolio this month...
》New Additions《
$WINC (+1,08 %) 244.01x
$AII (+0,71 %) 101x
》Exits《
$EVD (+4,67 %) 25x
》Top 3《
$HAUTO (+0,82 %) +24.42% (+122.67%)
$VAR (+0,51 %) +19.82% (+60.72%)
$DTE (+0,87 %) +10.61% (-1.53%)
》Flop 3《
$3750 (+2,58 %) -10.58% (+128.32%)
$ASWM (+0,91 %) -9.86% (+17.84%)
$YYYY (+1,39 %) -7.01% (-4.80%)
》Dividends《
This month, there were €252.24 in net dividends, representing a 12.24% increase year-over-year.
》CONCLUSION《
Everything’s business as usual, so we can relax and prepare for next Friday’s upcoming DATEV certification 👍🏻
I wish everyone continued success, and may dividends and growth be on our side 🫡
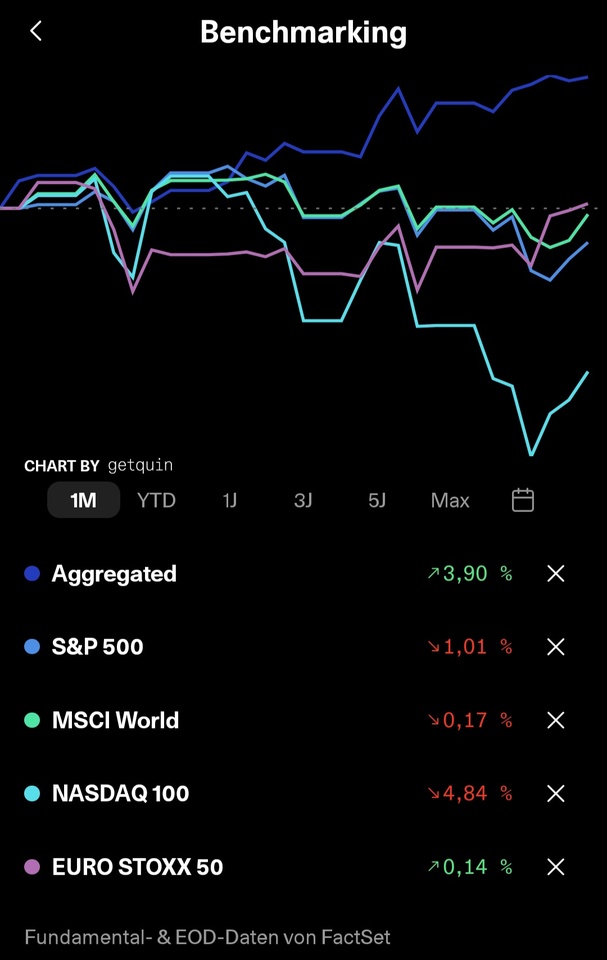
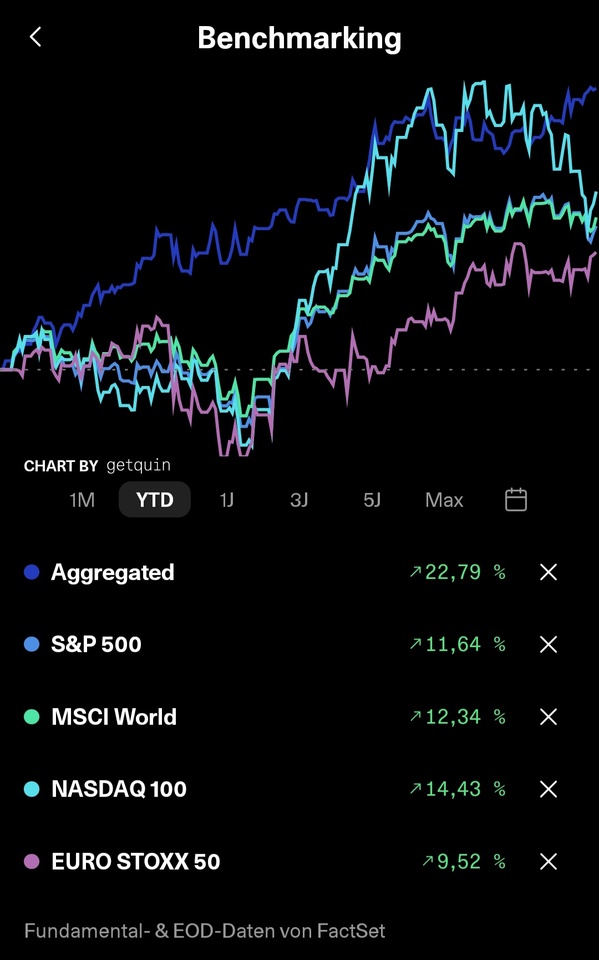

3Lun·
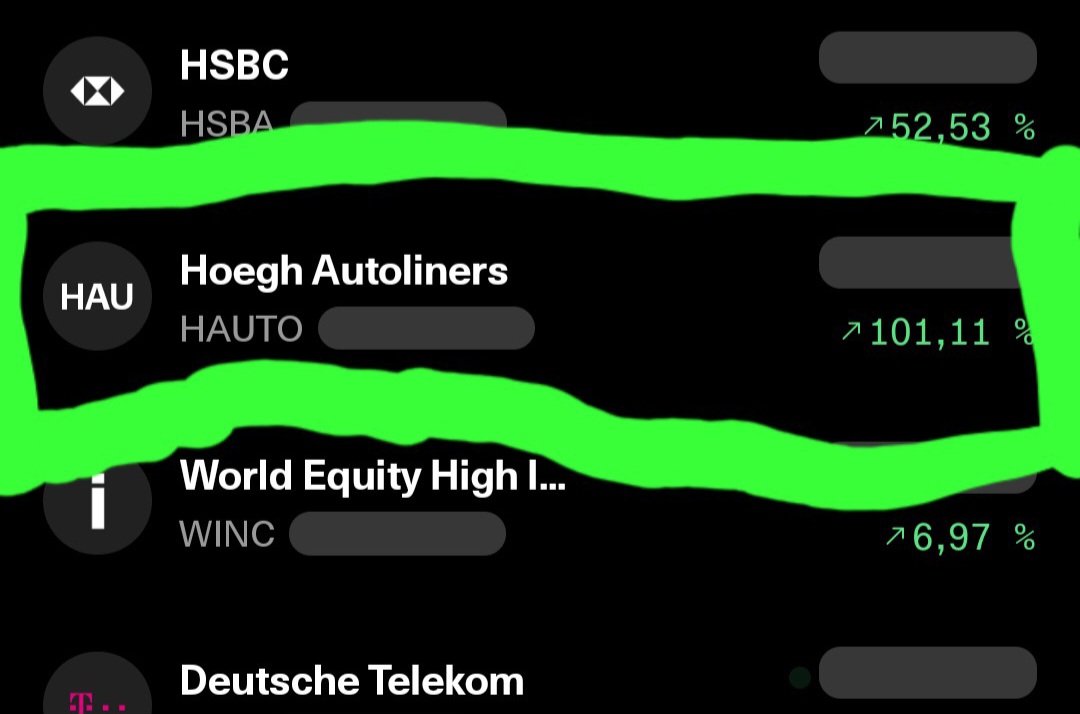
100%
...besides $BATS (+0,58 %) and $3750 (+2,58 %) the next value has now also -> $HAUTO (+0,82 %) the 100% mark 🫠


4Lun·
Höegh Autoliners Q1 2026
Finances Q1 2026
- EBITDA: USD 145 millionstable compared to previous quarter despite additional costs due to Hormuz crisis .
- Net result: USD 103 million .
- Dividend payment: USD 94 million in the quarter (16th quarter in a row) .
- Cash & liquidity: ~ USD 500 million at the end of the quarter .
- Operating cash flow: USD 144 million .
Market & demand
- Chinese car exports explode:
- Total +57 % YoY
- EV/hybrid exports +80-90 % YoY .
- Global light vehicle sales: -5 % YoYbut China compensates with massive exports .
- Strong demand for High & Heavy (construction machinery): +31 % YoY from Asia/China .
Capacity & fleet
- 8 out of 12 Aurora newbuilds already in operation .
- Charter market extremely tight: only 2-3 ships available available until summer, prices continue to rise .
- Industry orderbook: from 42 % to 20 % fallen - new capacity is fully absorbed .
- Ageing legacy fleet → increasing likelihood of scrapping . scrapping in the coming years .
Contract situation
- Overbooking of 80 % contract coverage for 2026; large part of 2027 already secured .
- USD 160 million in new contracts per quarter .
- Spot market only 6 % of the volume, mainly high & heavy
Fuel costs & BAF mechanism
- Hormuz crisis causes massive increase in bunker costs; full effect only visible in Q2 .
- BAF (Fuel Surcharge) compensated ~95 % of the costs - but with a 5-6 month delay .
Outlook Q2 2026
- Q2 heavily burdened by:
- +20m USD Fuel costs
- USD -10 million Middle East disruption .
- Expected EBITDA: slightly below or at the level of Q1 (adjusted) .
- No return to the Persian Gulf planned in the near future .
Cycle & market position
- Market is clearly driven by the Chinese export boom driven; absorbs all new builds and keeps rates high .
- No signs of falling rates in the current environment
Source seekingalpha.com, Copilot summary
1717
5Lun·
Logistics shares
As a logistics specialist, I am considering expanding this area in my portfolio.
I currently have :
$KCC (+1,23 %)
$DHL (-1,49 %)
$MPCC (+1,19 %) and a very small position $HAUTO (+0,82 %)
I am clearly in the black with all positions.
From my professional experience, I see clear potential in the sector, but I lack inspiration.
What is your top stock in the sector, or where would you like to invest?
55
7 Comentarios
5Lun
•
11
•