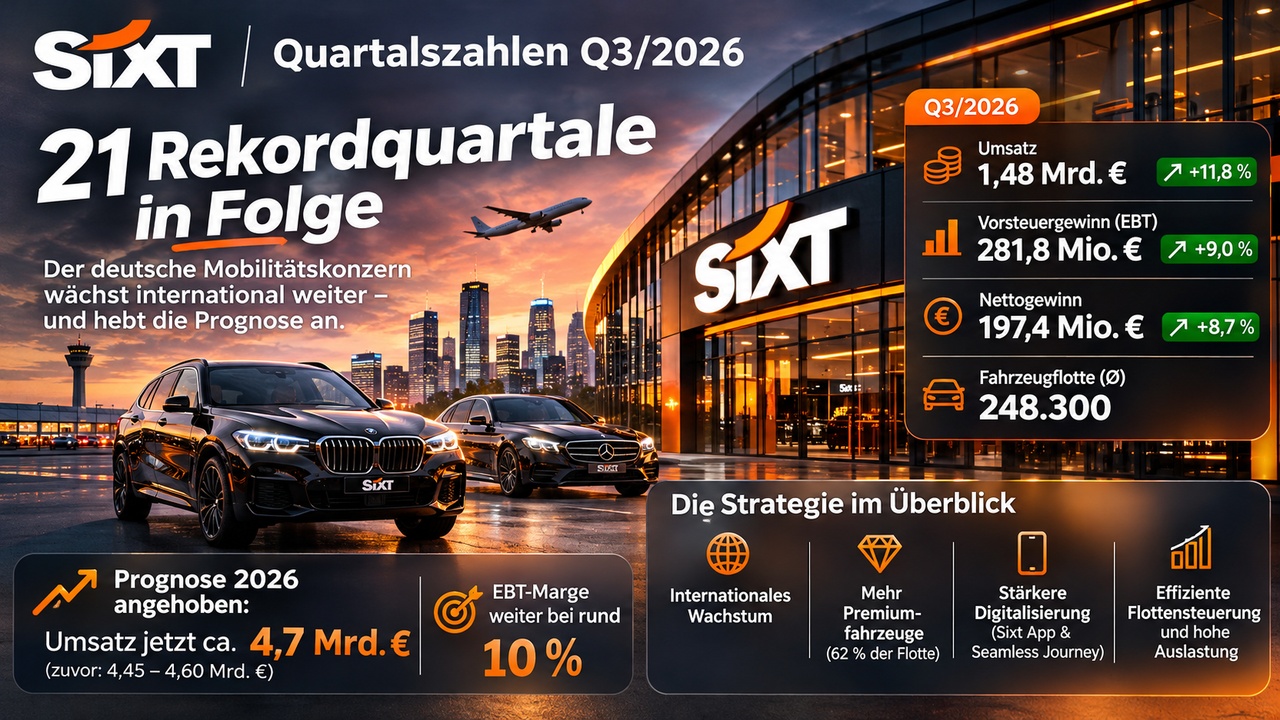

21 consecutive record quarters. And the streak could continue.
Today, SIXT released its results for the third quarter of 2026. I think this trend deserves significantly more attention on the German stock market.
Let’s take a closer look at the numbers:
Q3 2026 – Key Financial Metrics
- Revenue: 1.48 billion euros (+11.8%)
- Earnings Before Taxes (EBT): 281.8 million euros (+9%)
- Net income: 197.4 million euros (+8.7%)
- Corporate EBITDA: 350.4 million euros (+8.9%)
- Average vehicle fleet: approximately 248,300 vehicles
- Revenue after nine months: 3.60 billion euros (+10.2%)
Of particular interest: SIXT has thus achieved the highest quarterly revenue in its corporate history.
And now for the real news:
Management is raising its revenue forecast for 2026.
Instead of the previous range of 4.45 to 4.60 billion euros, revenue is now expected to be just under 4.7 billion euros.
The targeted pre-tax profit margin remains at around 10%. This corresponds to a targeted pre-tax profit of approximately 470 million euros.
What sets SIXT apart strategically?
This is where it gets interesting for long-term investors:
INTERNATIONALIZATION
About three-quarters of revenue growth now comes from international markets. Europe and North America, in particular, are performing well.
PREMIUM STRATEGY
The value share of premium vehicles in the fleet has risen to 62%. In the previous year, it was 55%.
BMW, Mercedes, and Audi are key components of this positioning.
DIGITALIZATION
SIXT will invest more than 100 million euros in its technology platform by 2026. The app is becoming a particularly important booking channel.
With the new SIXT Seamless Journey, the entire car rental process is designed to be digital and seamless.
GROWTH WITHOUT BLIND EXPANSION
SIXT deliberately keeps its vehicle fleet small and aligns it with demand. This is intended to improve utilization and profitability.
But where do the risks lie?
A sound investment analysis must not overlook the downsides:
- High capital requirements for the vehicle fleet.
- Interest expenses and financing terms.
- Residual value risks for used vehicles.
- Economic and consumer risks, particularly in the U.S.
- The equity ratio was most recently 26.6%.
The premium strategy must also prove itself over the long term.
My investment thesis:
I don’t view SIXT as just a traditional car rental company.
The company is increasingly positioning itself as an international premium mobility provider with a strong brand, digital sales channels, and a growing international business.
I find it particularly exciting that earnings after nine months rose by 16.9% to just under 407 million euros, while revenue increased by 10.2%.
This is a trend that investors should monitor closely.
Of course, good quarterly results alone don’t make a stock a good buy. Valuation, debt, cash flow, and future vehicle costs also need to be examined.
Now I’d like to hear your thoughts:
Do you see SIXT as an undervalued German blue-chip stock with international growth potential?
Or is the business model too risky in the long term due to its high capital intensity and dependence on the travel market?
Who among you is already invested or has SIXT on your watchlist?
I’m looking forward to hearing your thoughts.
#SIXT
#Aktien
#Dividendenstrategie
#Deutschland
#Wachstumsaktien
#Börse
#Investieren
#SDAX