

Hello my dears,
after some of my last stocks were rather risky. It's time again to present you with a solid and robust value.
Perhaps the ideal value for the summer slump and what is associated with it.
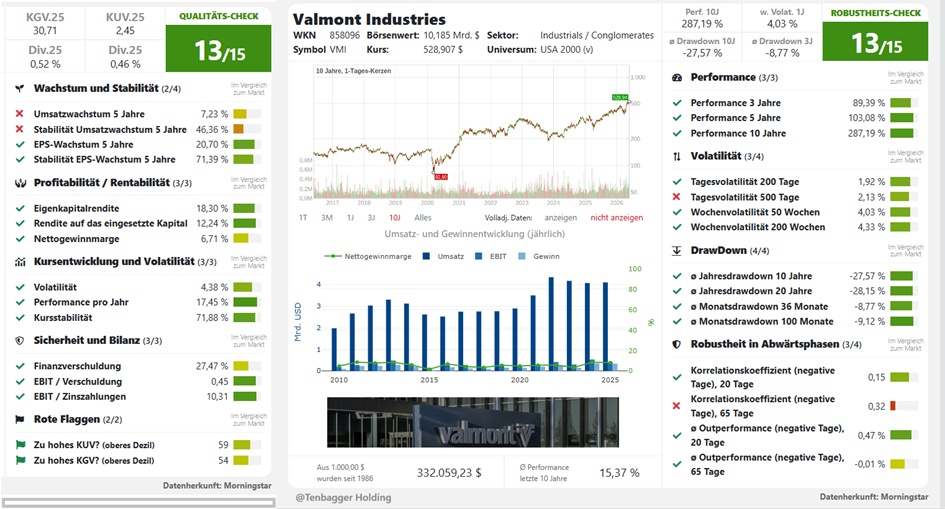
Getting 13 out of 15 points in the Traderfox robustness and quality check is also a rarity.
My dears, what do you think of $VMI (-2,51 %) Valmont, do you see it as a good foundation for stormy weeks?
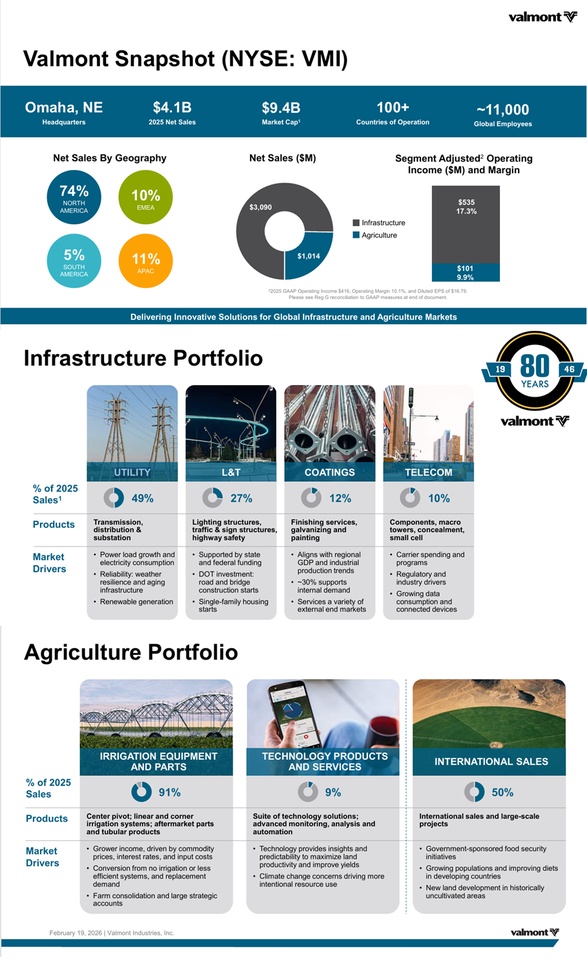
Valmont Industries, Inc. is a manufacturer of products and services for the infrastructure and agricultural markets. The company operates in two business segments: Infrastructure and Agriculture. The Infrastructure segment includes the manufacture and distribution of products and solutions for the infrastructure markets of utilities, lighting, transportation, telecommunications and solar energy, as well as coating services for the protection of metal products. The Infrastructure segment comprises five main product lines: Utilities; Lighting and Transportation (L&T); Coatings; Telecommunications and Solar. The Agriculture segment includes the manufacture of centralized and linear irrigation components for the agricultural market, including spare parts and pipe products, as well as advanced technology solutions for precision agriculture. The company manufactures and distributes center pivot and lateral move irrigation equipment and replacement parts under its Valley brand.
Number of employees: 10,791
Valmont Industries benefits from the modernization of power grids
Valmont Industries is a provider of highly innovative engineered infrastructure and agricultural solutions. The company develops and produces steel, concrete and composite structures for utility and agricultural markets.
On April 21, the company presented impressive figures for the first quarter, with earnings per share rising by 28% to USD 5.51. At the same time, the company increased its operating margin. At the same time, the company increased its operating margin by 190 basis points to 15.1%.
The company's clear growth driver is the infrastructure segment, which now accounts for around 78% of total sales. Valmont is benefiting greatly from the ongoing modernization and expansion of the American electricity grids, some of which are heavily subsidized by the government. Due to the continuing high demand in the infrastructure sector, the management is extremely optimistic about the future and has directly raised its forecast for annual earnings (EPS) for 2026 to a range of USD 21.50 to USD 23.50. The share is now breaking out to a new all-time high, which could be a further trend following move. (VMI)
On March 17, Avner Applbaum, President and CEO of Valmont Industries Inc (NYSE:VMI), joined Chief Financial Officer Thomas Liguori and Senior Vice President Renee Campbell to outline the company's strategic positioning at JPMorgan's Industrials Conference.
The leadership highlighted the company's operations in more than 100 countries, with approximately 70% of revenue generated in North America. 75% of the business is driven by infrastructure, while 25% comes from agriculture.
Management also presented a roadmap that would lead to earnings per share of between $25 and $30 over the next three to four years. This will be achieved by building capacity in the utility infrastructure sector as well as strong growth in agricultural technologies and the aftermarket.
Valmont Industries Inc (NYSE:VMI) is engaged in the production of goods and services for the infrastructure and agricultural industries. It manufactures and markets several products, including prestressed concrete, linear irrigation equipment, electric motors and many more. It also offers other relevant services, including painting, galvanizing and powder coating.
74f0815f-7c8d-475b-bda5-f92c8c87bfab
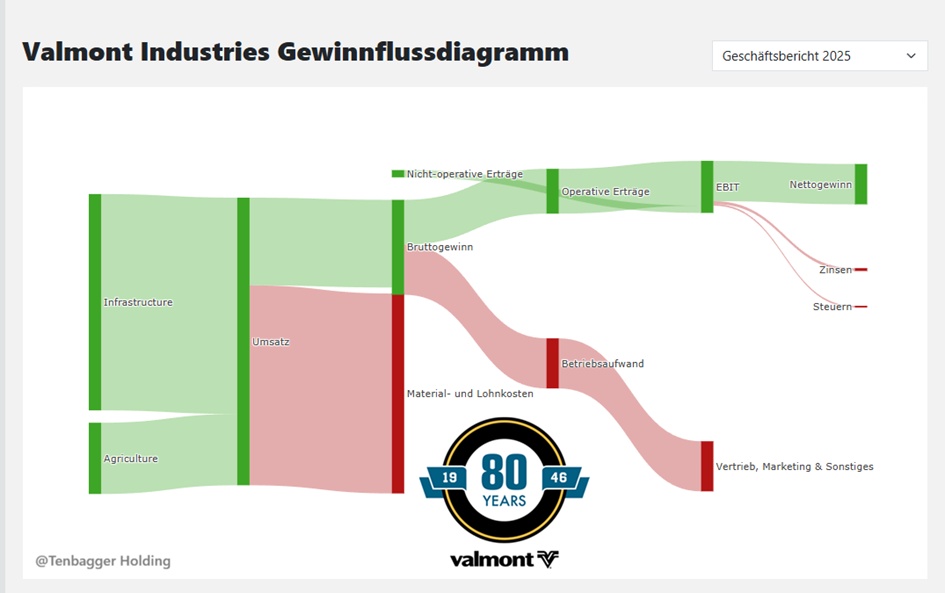
Sales breakdown by business segment:
2025 (USD)
Infrastructure 3.1 billion
Agriculture 1.02 billion
Intersegment Sales -15.68 million
Geographical distribution of sales:
2025 (USD)
U.S.A. 2.96 billion
Other 706 million
Australia 282 million
Brazil 159 million
Juan's conclusion (short, clear, to the point):
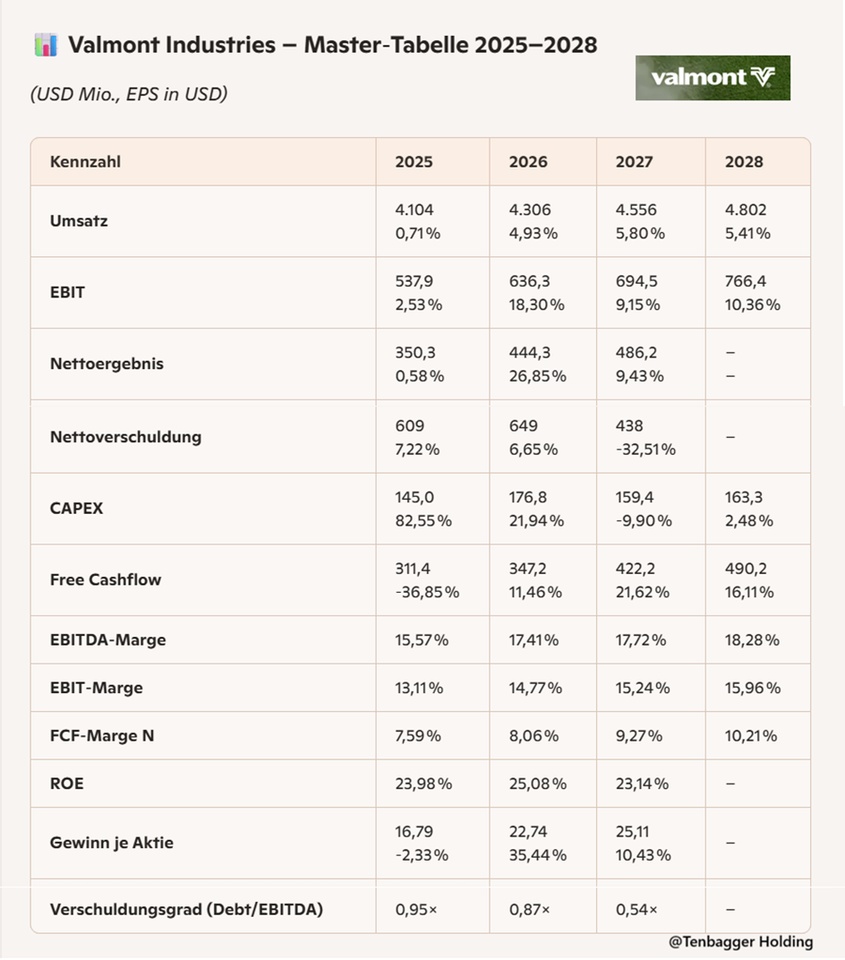
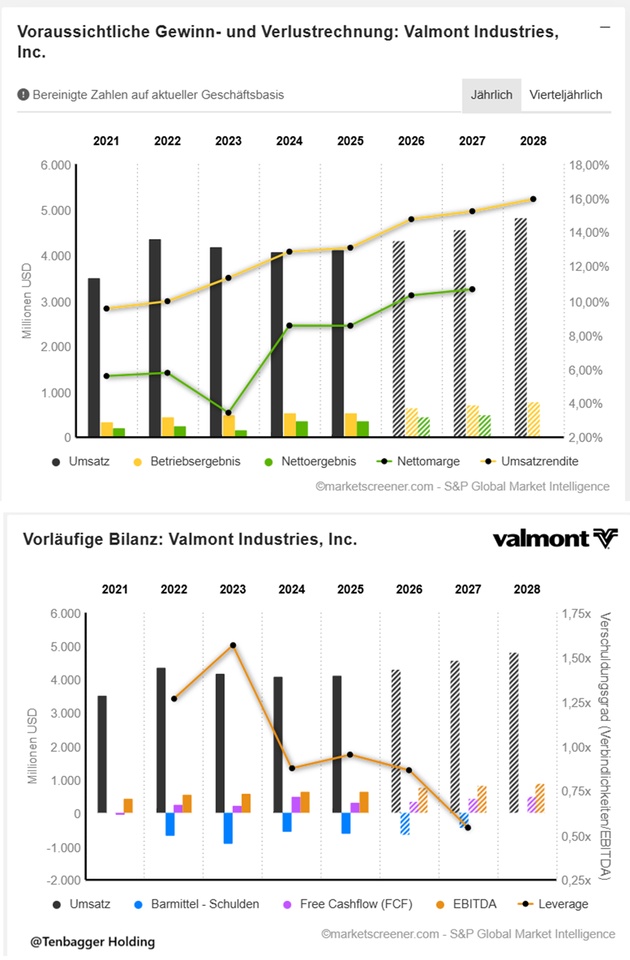
Valmont delivers a stable, clean set of figures. Sales are growing moderately, but profitability is picking up strongly - especially from 2026. EBIT and FCF are rising reliably, margins are climbing year on year. Debt is falling noticeably, improving financial leeway. Overall: solid quality profile with clear FCF strength and good margin momentum.
Market value 9,968
Number of shares (in thousands) 19,414
Date of publication 17.02.2026
🧠 Juan-Fazit - Valuation (short & crisp)
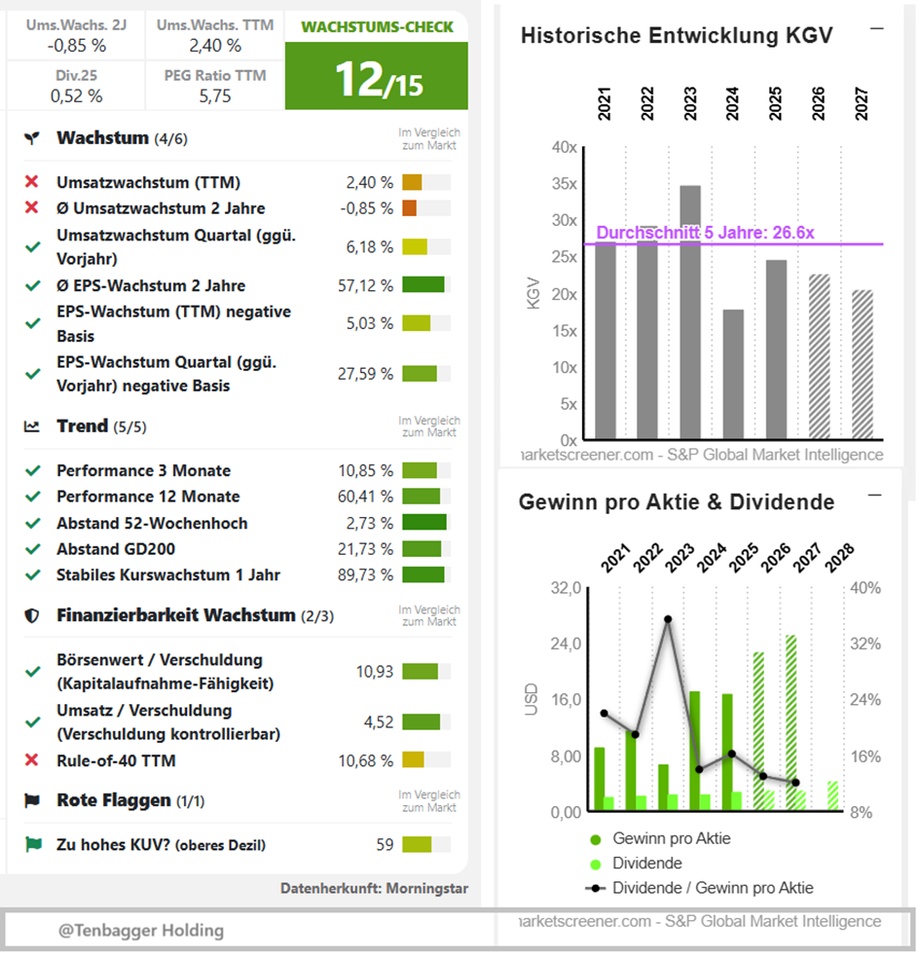
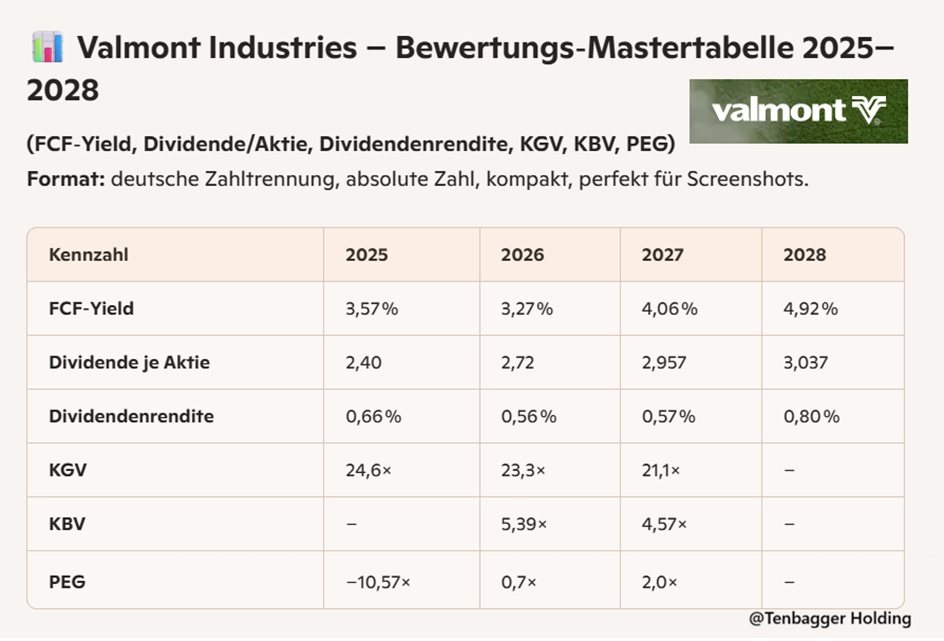
Valmont's valuation looks like a quality stock in transition: the P/E ratio is falling cleanly over the years, while the FCF yield is rising steadily. The dividend is growing steadily, but is deliberately kept low because the management prefers to invest cash in profitable growth. PEG 2026 attractive, 2027 neutral. Overall: not a bargain, but a clear "quality compounder price" with increasing cash efficiency.
🧠 Juan overall conclusion (financials + valuation)
Valmont shows the profile of a mature quality compounder: moderate sales growth, but strong margin expansion, rising FCF and falling debt. The valuation fits the picture: falling P/E ratio, rising FCF yield, attractive PEG 2026. Not a turnaround case, but a cleanly running cash machine. Stable, efficient, financially solid - and 2026 clearly looks the most exciting.
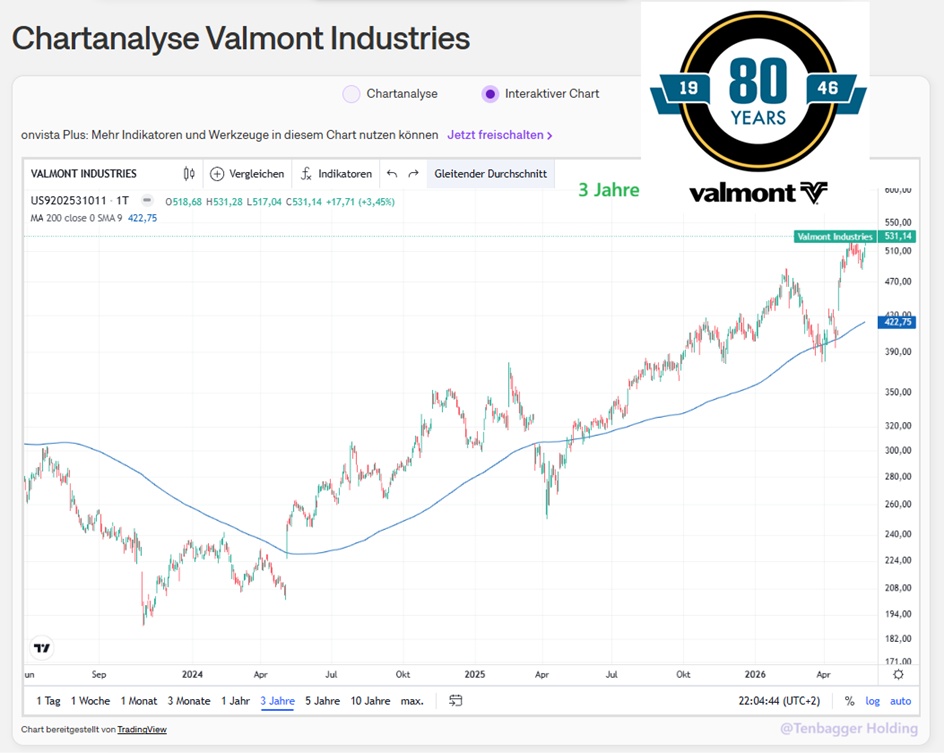
Performance
1 week +1.32 %
1 month +10.00 %
6 months +30.55 %
1 year +64.23 %
3 years +80.64 %
5 years +109.97 %
7 years +325.69 %
27,05,2026
today, 09:16:47 -
Lang & Schwarz (EUR)
452.00 EUR


