7Mo·

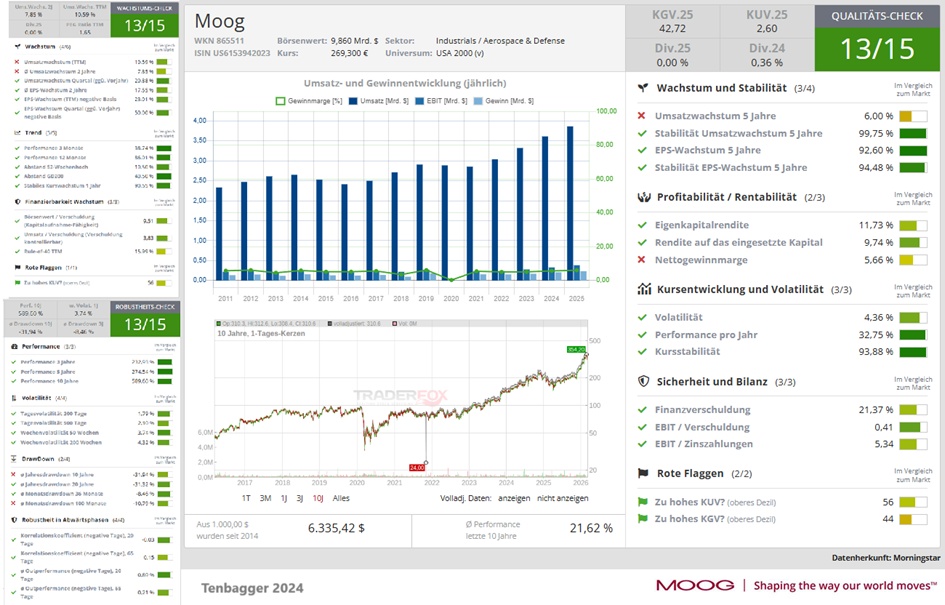
Three times 13 points, everything in the 🟢green area🟢. Night work for the community

Hello my dears,

I have recently introduced you to a few exciting satellite operators and space stocks.


And yesterday I read in the comments that it is very difficult to achieve good margins and constant profits in this sector. And the costs sometimes eat up everything again.

The companies often don't even operate profitably.


Investing here has opportunities but also risks that should not be underestimated.


Now, in my youthful recklessness, I have simply written a comment.


Tomorrow I will give you a company from the sector that has performed consistently over the years:


  • can increase sales and profits
  • has been profitable for a long time
  • the gearing ratio is ridiculously low
  • EBIT margin and ROE are in the double-digit range and are increasing


Oh dear, what had I done 🙈.


First I started with the satellite operators. But I quickly had the idea.


"You should look at your beloved shovel suppliers"


I hadn't said anything about operators, and I was talking about the sector. But even in the sector, finding a company that meets all the requirements. Should become night work 😭.


My dears,

I am all the happier to have found a company.

Which just shines in the Traderfox check.


And even scores high on robustness, which is a rarity.

(That means a stock to sleep soundly, and that in the sector)


I am all the more curious about your comments, and hope you enjoy my little night's work.
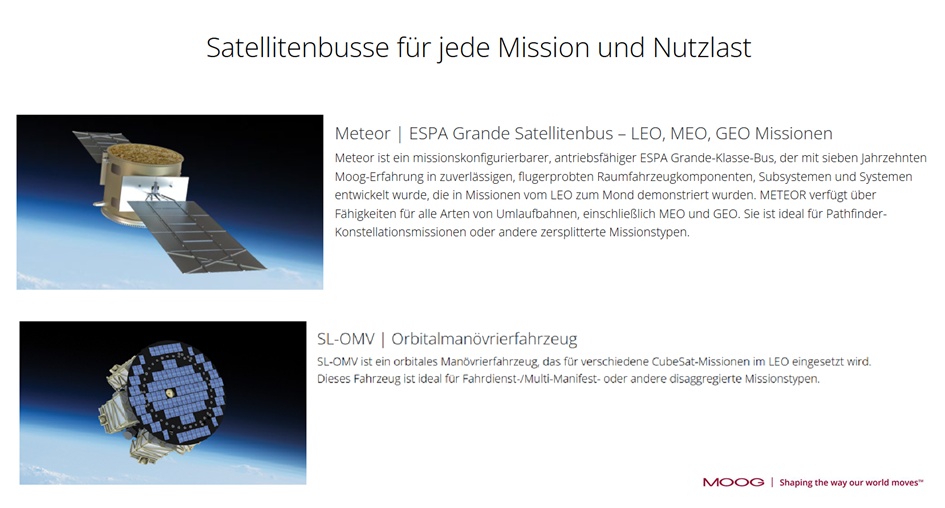
attachment


$MOG.A (+0,61 %)

Moog Inc. is a global company that designs, manufactures and integrates precision control components and systems. The company's segments include aerospace and defense, military aircraft, commercial aircraft and industrial. The Space and Defense segment manufactures critical defense components and motion control systems used in defense vehicle platforms, missile systems, naval vessels and submarines. The Military Aircraft segment designs, manufactures and integrates primary and secondary flight controls, mission-critical actuation systems and products for various military fixed-wing and rotary-wing aircraft. The Commercial Aircraft segment designs, manufactures and integrates primary and secondary flight control systems and products for various commercial aircraft, including wide-body aircraft, narrow-body aircraft, business jets and regional aircraft. The Industrial segment offers customized, high-performance motion control components and systems for industrial automation, medical, simulation and test, and energy applications.

Number of employees: 13,500


Success story continues! Rocket order, record quarter and a high-tech portfolio for the future!

Precision that cannot be replaced


Moog (ISIN: US6153942023) is a prime example of how technological depth and specialization can create value over decades. The company develops high-precision drive, control and regulation systems that are used where errors are not an option: in airplanes, satellites, military applications, medical devices and sophisticated industrial plants.

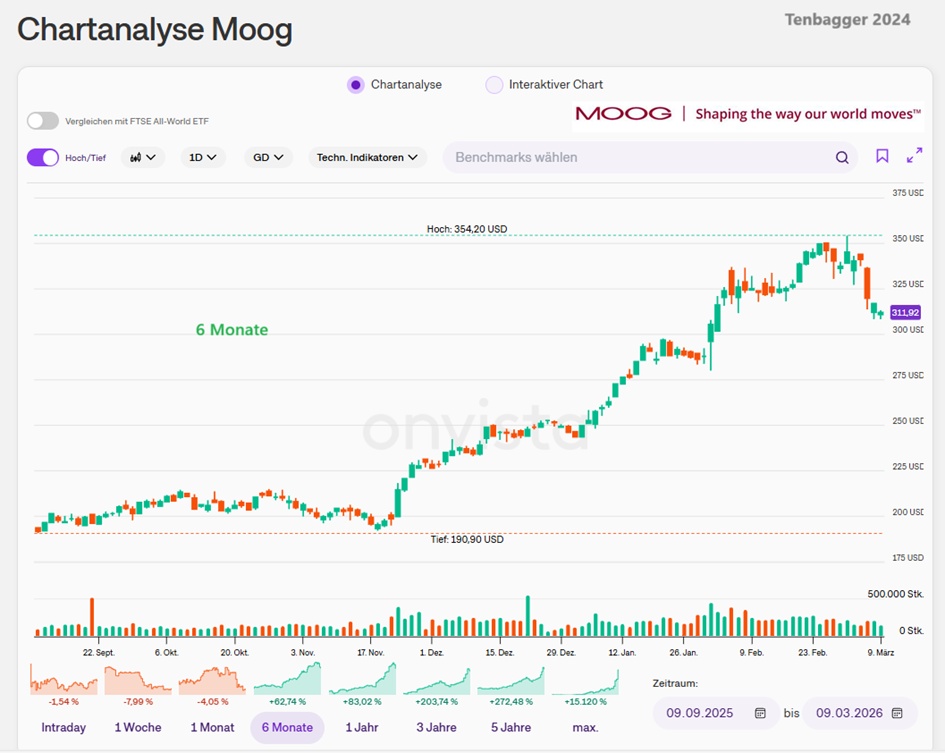
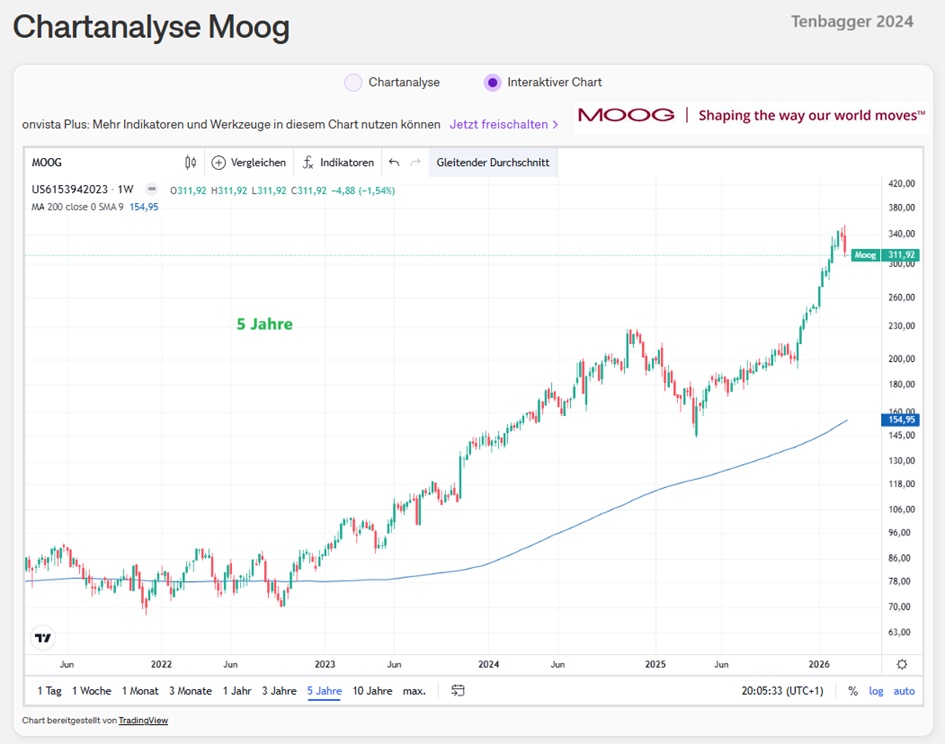
The long-term upswing in the share price began on November 2, 1992 at around USD 1.19. With a record high of USD 248.86 on December 11, 2025, the share price has increased a good 200-fold since then. An investment of EUR 10,000 would be worth almost EUR 2.1 million today - in purely mathematical terms.

Moog has become a long runner because the company has grown consistently over decades in precisely those niches where barriers to entry are particularly high. Customers from the aerospace and medical technology sectors do not change their suppliers lightly. Certifications, safety standards and decades-long product cycles ensure that established suppliers are firmly anchored in their customers' systems.

There is much to suggest that these factors will continue to have an effect. Increasing automation, rising demands for precision and reliability and growing investment in defense and space programs are strengthening Moog's market position. The moat is not spectacular - but it is extremely durable.


My dears, as we can also see from the great rating in all categories of the Traderfox check.
attachment


Moog IR Presentation 2025

attachment


Popular products


attachment


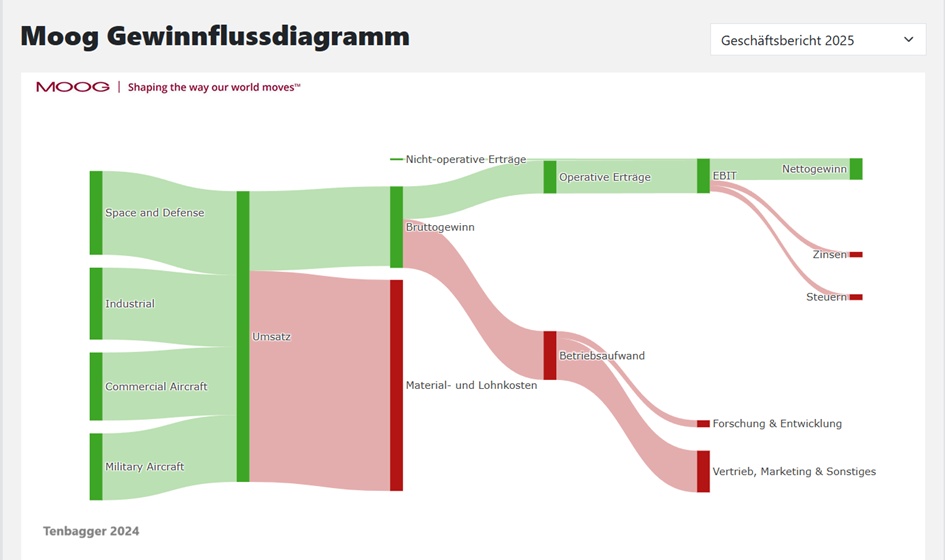
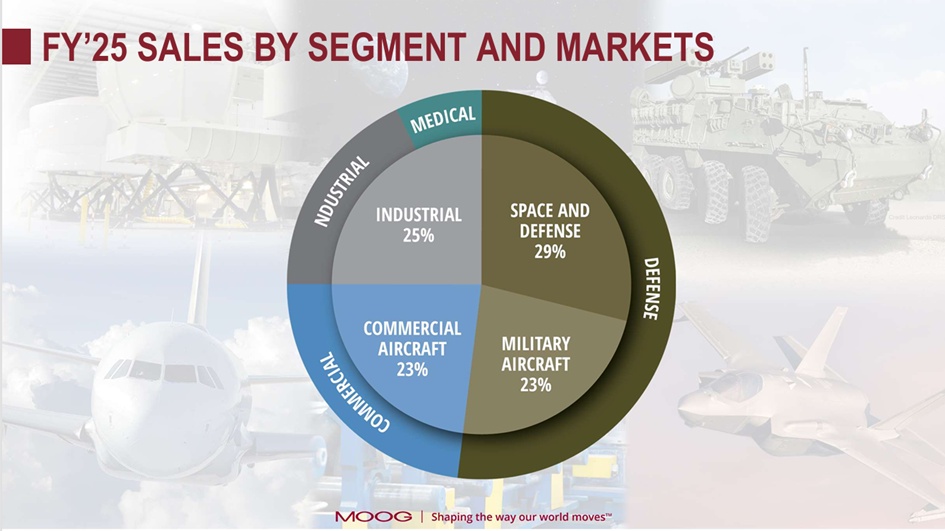
Turnover distribution by business area:

(USD)

2024 2025

Space a Defense 1.02 billion 1.11 billion

Industrial 991 million 956 million

Commercial Aircraft 788 million 904 million

Military Aircraft 812 million 888 million
attachment


INDUSTRY


Aerospace & Defense

Industrial

Medical Medical

Medizinische Ultraschallmessung


Geographical distribution of sales:

(USD)

2024 2025

USA 2.32 bn 2.43 bn

Other 1.13 bn 1.18 bn

Germany 165 million 247 million


USD in millions

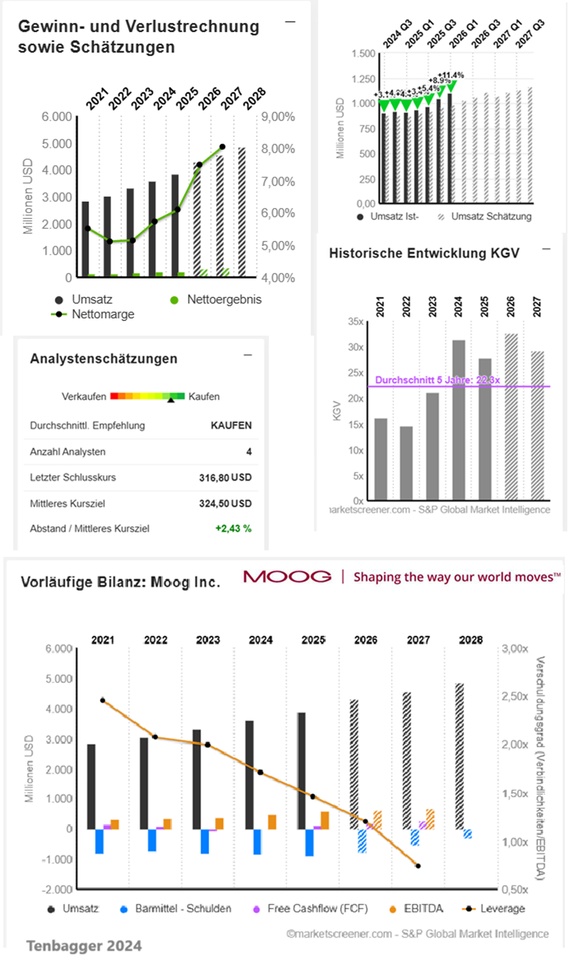
Estimates

Year Turnover Change

2025 3.861 6,97 %

2026 4.303 11,45 %

2027 4.560 5,99 %

2028 4.860 6,57 %


Year EBIT Change

2025 440,1 14,81 %

2026 553,6 25,8 %

2027 607,3 9,7 %

2028 647,9 6,67 %


Year Net result Change

2024 207,2 21,18 %

2025 235 13,42 %

2026 321,5 36,8 %

2027 366,9 14,1 %


Year Net debt CAPEX

2025 883 144,7

2026 753 154,4

2027 511 160

2028 282


Year Free cash flow Change

2024 21,33 157,1 %

2025 128,4 501,87 %

2026 193,1 50,44 %

2027 281,8 45,93 %


Year EBIT margin ROE Leverage ratio

2024 10,62 % 11,85 % 1,71x

2025 11,4 % 14,59 % 1,46x

2026 12,87 % 29,81 % 1,2x

2027 13,32 % 29,34 % 0,74x

2028 13,33 % 28,39 %


Year Earnings per share Change

2024 6,4 19,85 %

2025 7,33 14,53 %

2026 9,675 31,99 %

2027 10,82 11,89 %


Year Dividend Yield

2024 1,11 0,55 %

2025 1,15 0,56 %

2026 1,2 0,38 %

2027 1,23 0,39 %

2028 1,26 0,4 %


Year P/E ratio PEG

2024 31.4x 3.49x 1.6x

2025 27.9x 3.29x 1.9x

2026 32.7x 4.45x 1x

2027 29.3x 3.85x 2.5x

Market value 10,138

Number of shares (in thousands) 31,726

Date of publication 21.11.2025
attachment
attachment
attachment


@Get_Rich_or_Die_Tryin

$MOG.A (+0,61 %)

55
25 Commentaires

image de profil
"Hello Mr. Tenbagger,
First of all, respect for the neat elaboration! With Moog Inc. (MOG.A) you have definitely not chosen an air number, but a real traditional company with a moat. The story you describe (order backlog, defense boom, aging aircraft) is absolutely right in terms of content.
But let's look at the whole thing calmly and objectively and run the share through my filters with today's latest figures.
1. the hard valuation ratios
To get a feel for how "expensive" the story currently is, here are the bare facts (as at March 2026)
* P/E ratio (price-earnings ratio): ~39.2
* KCV (price-cash flow ratio): ~24.6
* KUV (price-sales ratio): ~2.5
* P/B (Price-Book Value Ratio): ~4.4
* Dividend yield: 0.38
2. the reality check with my formulas
A) Core Quality Formula (Qualitative Growth)
* Sales growth: approx. 7 % (financial year 2025: from USD 3.6 bn to USD 3.86 bn)
* Operating margin: 13.0% (adjusted margin for 2025)
* My score: 7 + 13 = 20
* Verdict: Solid (15-25). Moog is doing well in terms of quality and the management is managing to increase margins slightly. But it is a very capital-intensive business and not a high-margin software company.
B) Cashflow Quality Formula (The Cash Machine?)
* Free cash flow (FCF) was around USD 128 million in 2025.
* With a current market capitalization of approx. USD 10.1 bn, this results in an FCF yield of an extremely meager ~1.26%.
* Verdict: My target for a real cash machine is > 5 %. Moog is very weak here. The company has to tie up and invest a lot of cash in operations, which leaves little free cash for shareholders (measured by the share price).
C) Dividend filter
* The yield of 0.38% mercilessly breaks my absolute minimum requirement (>= 3.5%).
* Verdict: Completely failed.
💡 Conclusion: A great company, but not a good share (for me)
Mr. Tenbagger, you did a great job analyzing the company. Moog is the classic "shovel seller" for aviation and defense. BUT: The market already knows that!
With a P/E ratio of just under 40, this industrial stock is currently as expensive on the stock market as a hyped tech rocket. If the defense budgets or aircraft construction stutter even briefly, there is a lot of room to fall at this valuation.
To become a "tenbagger", the value of the company would have to increase tenfold to over 100 billion dollars. With 7% sales growth, that would take decades.
For my portfolio, the share is a clear no, as the dividend is practically non-existent and the free cash flow does not justify the expensive valuation. It's a rock-solid value for you if you ignore the price - but it's unlikely to become a tenbagger.
Keep up the good work, the analyses are getting more and more solid!"
•
8
•
image de profil
@Raketentoni Quality has its price
•
1
•
image de profil
@Tenbagger2024 but quantity also has its own quality 😂
•
1
•
image de profil
@Raketentoni you should develop Mr. Prompt into an honorary stock advisor. However, he should start by questioning his clients very carefully. About risk tolerance, investment behavior, whether growth or dividends, etc. In order to be able to respond precisely to their needs
•
1
•
image de profil
@Tenbagger2024 yes that's a good idea, i'll get to it this week 👍😬
••
image de profil
@Raketentoni that will definitely be mega 😘
••
image de profil
@Raketentoni
Could your Mister Prompt analyze Siemens?
That would help me a lot. It's my biggest position and due to the price drop I'm itching to add to it.
Thank you very much
••
image de profil
@capital_captain_2693 I'll finish it for you later
•
2
•
image de profil
@capital_captain_2693

When the largest position in your portfolio falls and your fingers are itching to buy more, you need a cool head. The share price has fallen from its 52-week high of just under € 276 to currently around € 230.

Here is an objective and precise analysis of the current situation at Siemens (as at March 2026) so that you can make an informed decision:

### 🏭 Fundamental check: Siemens AG

**Price:** ~230 € | **Market capitalization:** ~177 bn € | ** P/E 2026e:** ~19 to 20

#### 1. operating strength (figures for Q1 2026)

The latest figures for the start of fiscal year 2026 (published in February) show that Siemens is in an excellent operational position:

* **Growth:** Revenue increased by 4% to €19.1 billion (on a like-for-like basis even by 8%).
** **Profitability:** The profit margin in the Industrial Business is an outstanding **15.6%**. The *Digital Industries* and *Smart Infrastructure* divisions were the strongest drivers here.
** **Outlook:** Management has started the year so confidently that the forecast for earnings per share (EPS) has even been raised slightly following the strong quarter.

#### 2. Dividend & Valuation

** **Dividend:** The dividend for 2026 was raised to €5.35** per share. At the current share price, this corresponds to a yield of around **2.38%**.
**Valuation:** A P/E ratio of just under 20 is sporty for a traditional industrial company. However, it reflects the fact that the market is increasingly valuing Siemens as a technology and software company that is benefiting massively from the AI boom through automation and the equipping of data centers.

#### 3. Why is the share price currently falling?

If the figures are so good, why the setback?
At over € 270, the share price was simply very high and to some extent overvalued. The current fall of just under 10 % over the month is a healthy market consolidation. In addition, there have recently been market-wide "AI worries" that have temporarily put the entire hardware and industrial sector under pressure.

---

### 💡 Conclusion & plain language on the buy-back idea

**The company absolutely delivers, but should you buy more?
My advice for you: **Keep your fingers still**.

Here is the most important reason: You write yourself that Siemens is already your **biggest position**. If you buy into the weakness now, you will further inflate your "cluster risk". A healthy portfolio needs diversification. Even the best company in the world can get into difficult waters, for example due to weaker phases in individual markets such as China or Europe.

**The strategy:**
Don't use the fall in the share price as a justification for unbalancing your portfolio. Collect the solid dividend of €5.35, enjoy an excellently managed quality company in your portfolio and use your fresh capital to build up other sectors that you may still be missing.

Would you like me to pick out a few exciting investment ideas from other sectors that could make a useful addition to your portfolio?
•
2
•
image de profil
@Raketentoni Thank you very much 👍
•
1
•
@Tenbagger2024 Thanks for the great contribution and the work. Added to the watchlist.
•
1
•
Voir toutes les 2 autres réponses
image de profil
Very good company. A bit expensive at the moment, I could imagine buying it at a P/E ratio of 15, i.e. at half the current price 😅 but I would keep an eye on it nonetheless.
•
2
•
image de profil
@TechNav thanks, of course, the geopolitical uncertainties are driving the price. Plus the IPO of space X. That's pushing the whole sector. Let's see if a correction comes
•
3
•
image de profil
When do you sleep? Are you invested?
•
2
•
image de profil
@Crash-Propheteus no , only found yesterday. I'm already heavily invested in the sector, otherwise I would get in if there was a correction. The community is depriving me of sleep 🙈😂
•
3
•
image de profil
If I wasn't waiting for the Honeywell Aerospace division to be spun off, this would definitely be an interesting pick for me in the sector. Thanks for the introduction 🙏😊
•
2
•
image de profil
Good evening, thank you very much for the introduction. Interesting company that you have dug up again! The company is active in exciting segments and is relatively broadly diversified. There is certainly a lot more to come in the future. As you can probably guess, the growth is not high enough for me. The valuation is justified in my opinion, but the air is getting thinner on the upside. So currently not an investment for me... Have a nice evening 😊
•
2
•
image de profil
@Klein-Anleger why has $PNG risen so much today?
•
1
•
image de profil
@Tenbagger2024 Well, the takeover is now gradually being priced in:
-> Turnover triples. Profits are also increasing significantly and that still has to be priced in. I think by the end of 2026, ten euros per share is not unrealistic. 🚀😊
•
2
•
image de profil
Looks great! Thanks for the presentation.

Margins look solid for industry, for strong in the niche they might even be a bit better. But overall a solid profile that I like.👍🏻

What I like: the segment distribution, which is almost balanced across all segments. The sales declines in the Industrials segment can be more than compensated for by the growth in the other segments, which is very good in any case.

Exciting company, valuation should of course come down a little (more) before I would consider an entry here.

I like the overall constellation, although the margin profile and the payout profile are less in line with the requirements of my portfolio.🫣 Landing on the watch, my dear.🫶🏻
•
1
•
image de profil
@Get_Rich_or_Die_Tryin With pleasure, my dear. What I also like is the good and solid history. That speaks for quality and Burggraben
•
1
•
image de profil
Mega, thank you! ✌🏼
•
1
•
My favorite. The Moog I
•
1
•
Participez à la conversation