Hello my dears,
through the dear @Multibagger I was made aware of Solaris $SOI (-0,29 %) to my attention.
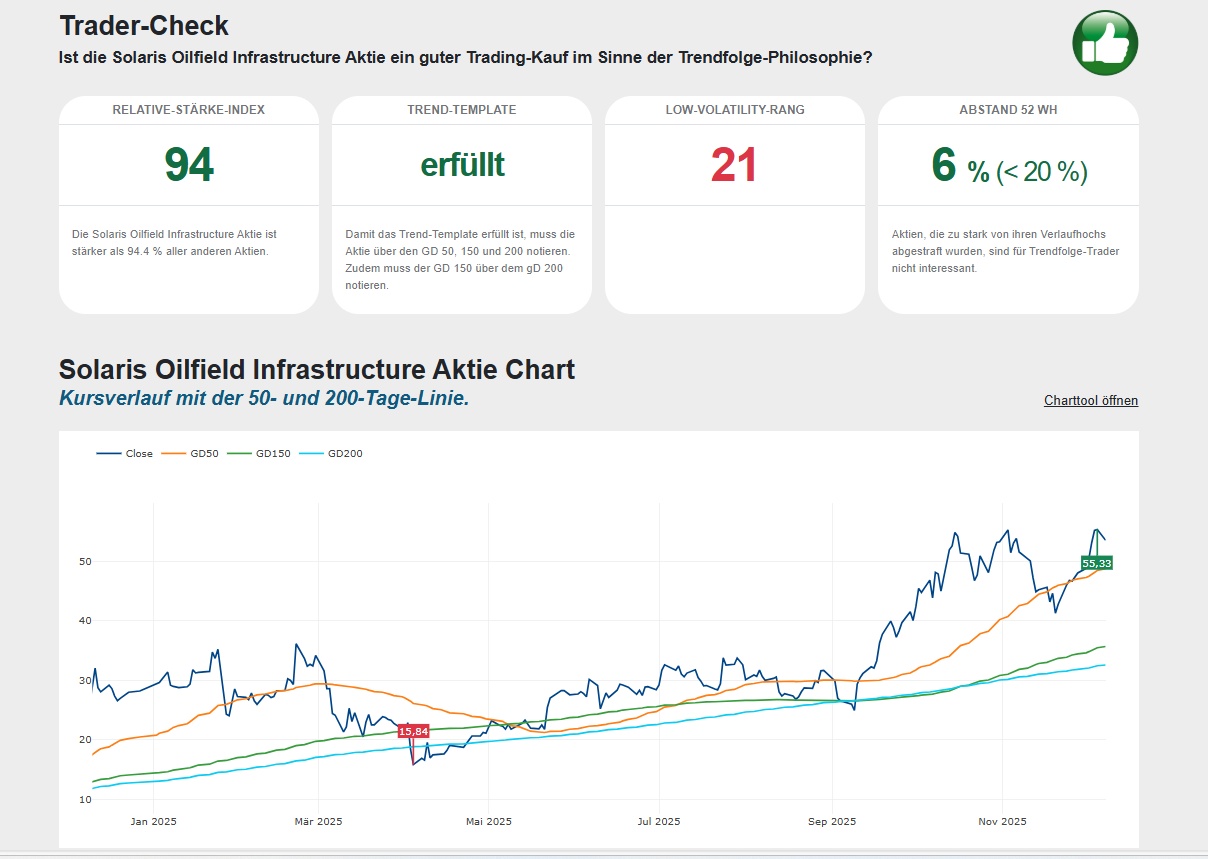
I quickly saw a few parallels with Siemens Energy.
And I realized that Solaris is also benefiting from the rise of data centers.
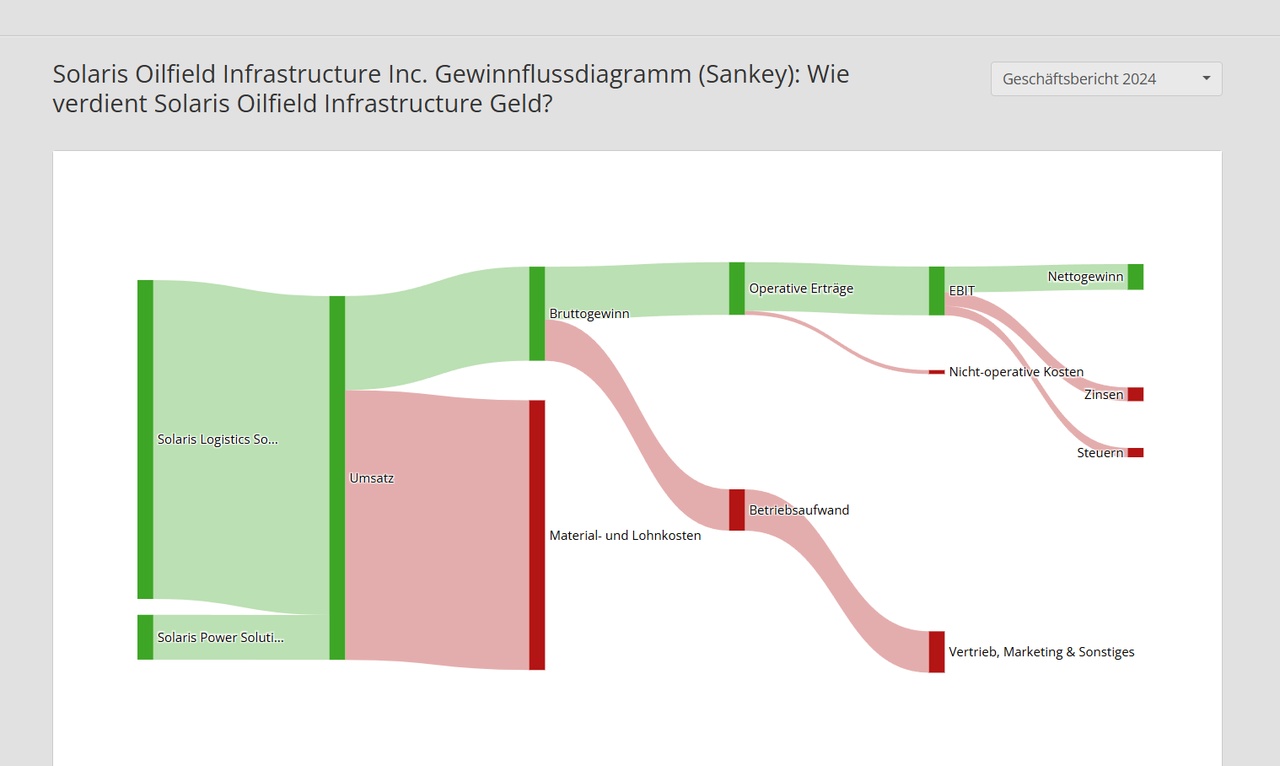
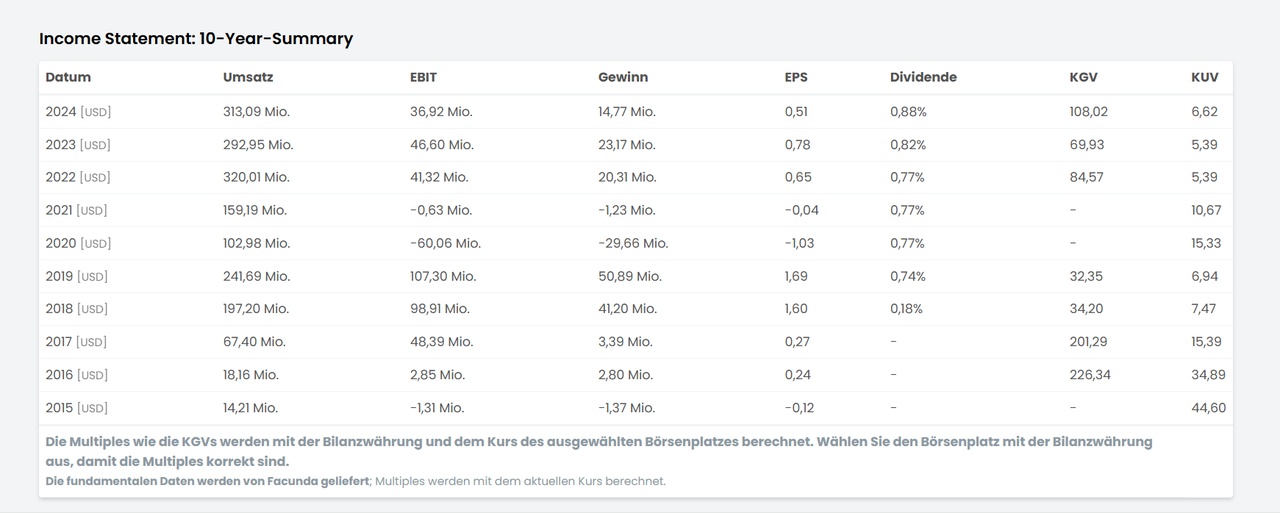
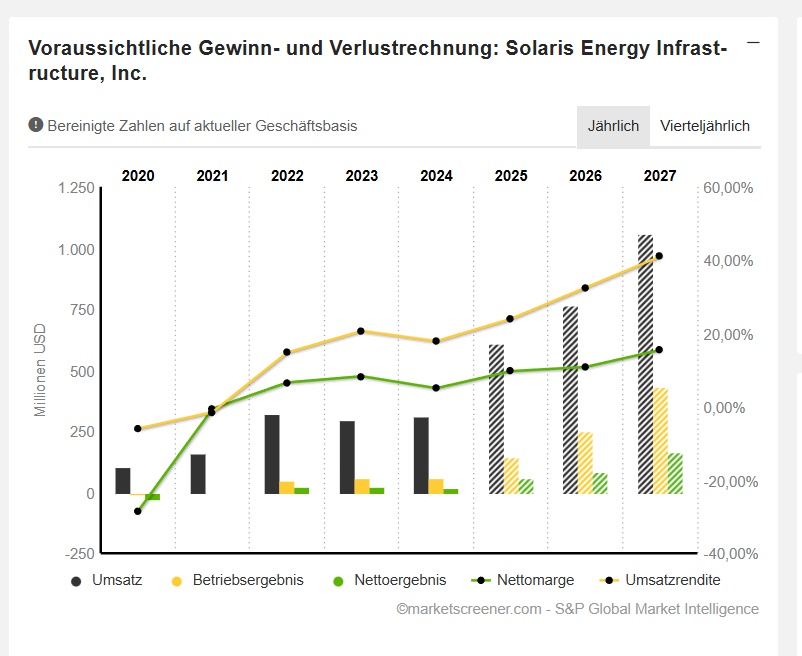
Which we can see from the nice increase in sales, profits and margins. And will continue to do so over the next few years.
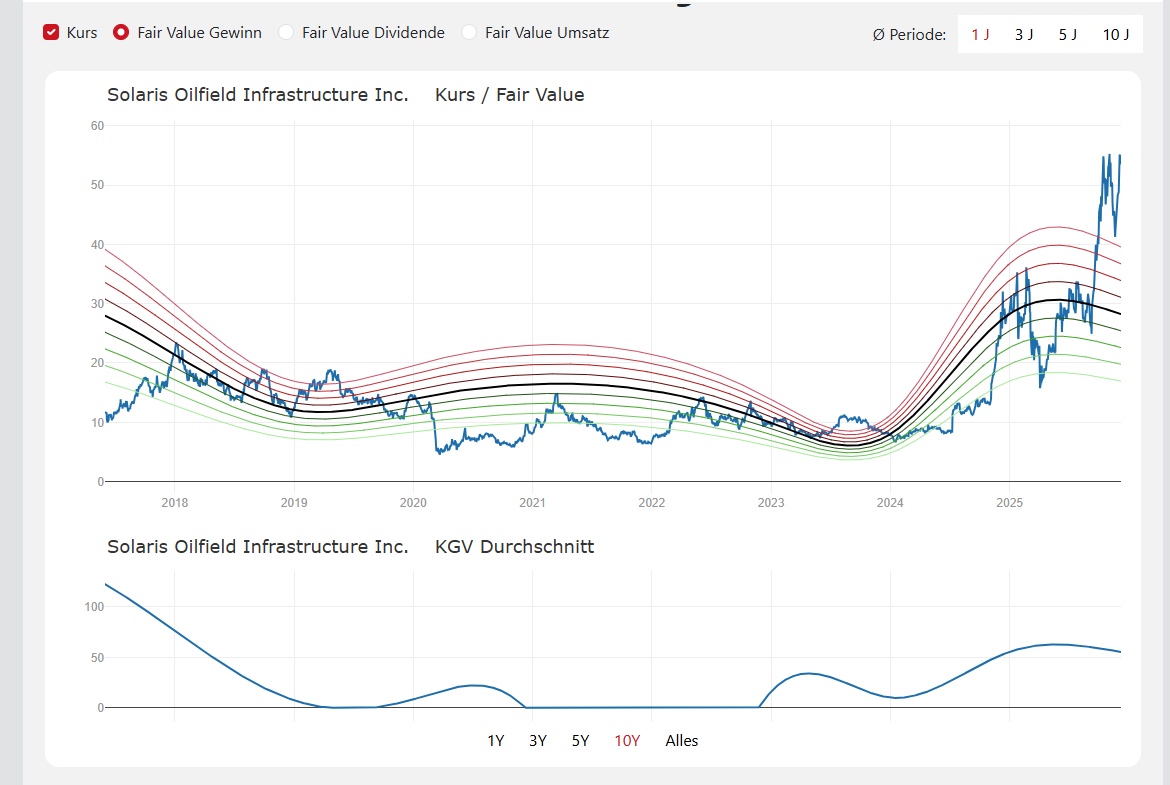
So I still see potential here.
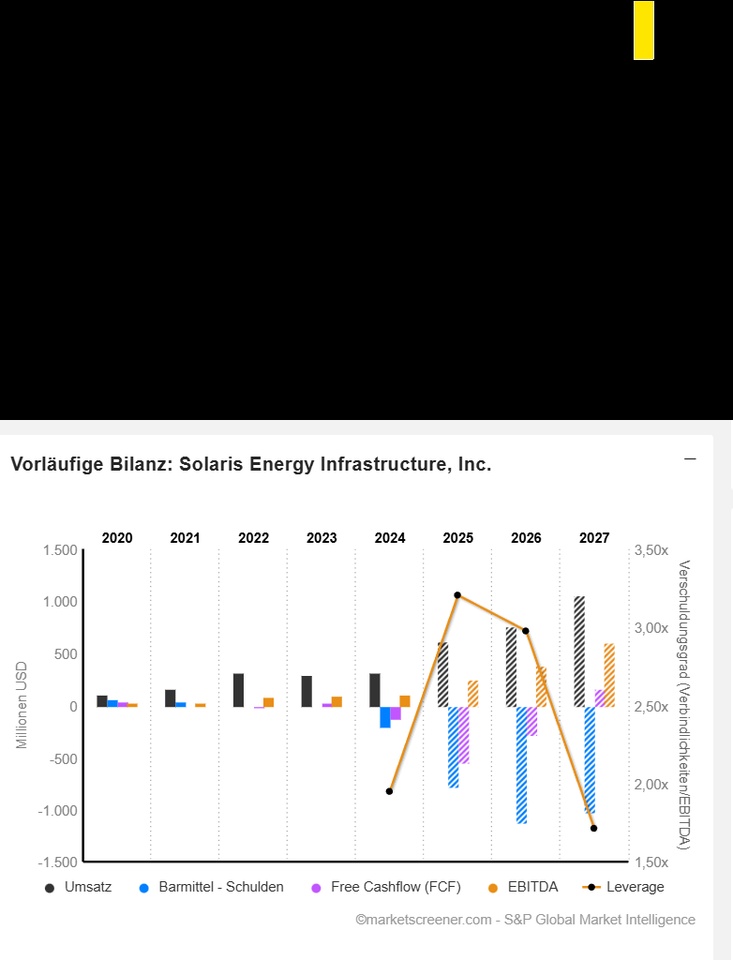
But all that glitters is not always gold, so I would also like to draw your attention to the rising debt with a negative free cash flow.
You can see this clearly in the chart below.
To show you where the money is going, I have included the CAPEX from 2023. Here we can see an enormous increase.
However, there are always companies that have overstretched themselves due to excessive investments.
But I find that difficult to classify here.
That's why I would like to get the community on board for this assessment.
I look forward to your comments!
It would also be nice to get an assessment from @Liebesspieler and @topicswithhead
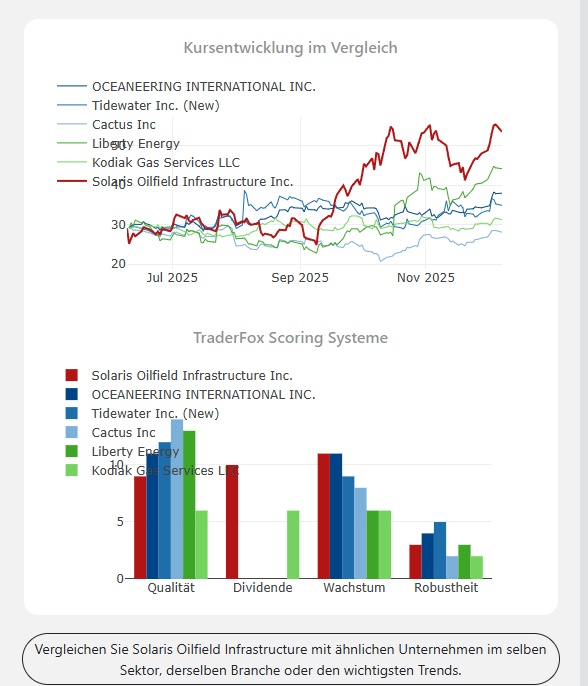
As alternatives, you will also find comparable companies in the chart below, such as $OII (-0,52 %) . Unfortunately, this company does not benefit from data centers. However, the company is active in other exciting sectors, such as critical infrastructure.
(October 6, 2025)
Solaris Energy Expects Several Growth Opportunities Due to Increasing "Grid Constraints" by 2030, Morgan Stanley says
Solaris Energy Infrastructure, Inc., together with its subsidiaries, provides mobile and scalable solutions for distributed power generation and the management of raw materials used in the completion of oil and natural gas wells. Its segments include Solaris Logistics Solutions and Solaris Power Solutions. The Solaris Logistics Solutions segment develops and manufactures specialized equipment for the management of raw materials used in the completion of oil and gas wells. Equipment-based logistics services include on-site technician support, software solutions and last-mile and mobilization services. The Solaris Power Solutions segment offers configurable sets of natural gas-powered mobile turbines and ancillary equipment. This segment leases equipment to customers in the data center and oilfield sectors and is focused on further expanding its services to these customers as well as to several commercial and industrial end markets.
Number of employees: 364
Who we are
Founded in 2014, Solaris Energy Infrastructure delivers reliable equipment and technology that integrates proven energy solutions, in-house expertise and customer-focused service.
We are a forward-thinking, growth-oriented company that provides turnkey solutions to traditional challenges and delivers results project after project.
Delivering results across the country
We operate in every major shale play in the U.S., including the Permian, Eagle Ford, Marcellus/Utica, Haynesville, STACK/SCOOP and Bakken formations.
We have strategic locations to support our customers' operations and manufacture our equipment at our 100,000 square foot facility in Early, Texas, delivering results and tangible value to our customers.
SEI Investor Presentation November 2025
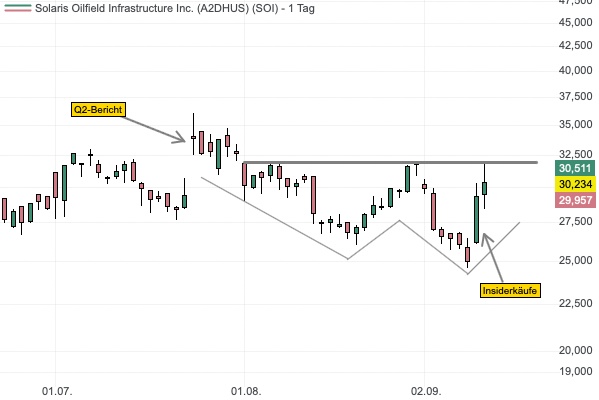
Insiderkäufe bei Solaris Energy Infrastructure — Aktie vor Ausbruch aus doppeltem Boden!
September 12, 2025
Solaris Energy Infrastructure offers, among other things, natural gas-powered mobile turbines for customers in the data center, energy and exploration sectors. As the Q2 figures from July 23 show, it is precisely these turbines that are generating momentum and have recently driven revenue growth by 18% YoY to USD 149.3 million. The company plans to expand its power plant fleet from the current 600 MW to 1,700 MW by Q2 2027 in order to meet the growing demand for energy solutions, particularly for data centers.
The order backlog, which already covers around 75% of the available capacity through contracts or advanced negotiations, offers a promising outlook. Bill Zartler, the company's CEO, recently expressed his satisfaction with the performance and highlighted the expansion of the power plant fleet, the accelerated energy supply for a data center project and the acquisition of new customers. On September 10, it was announced that he had purchased shares worth USD 248,000. The CFO also bought USD 50,000, which caused the share price to rise significantly.
The share could now quickly break above the resistance level of USD 32, bringing the annual high of USD 37 back into focus. (SEI)
Solaris Energy Infrastructure (SEI): High demand for mobile natural gas turbines drives growth!
July 24, 2025
Solaris Energy Infrastructure Inc (SEI) published its Q2 report on July 23 after the close of trading. According to the report, revenue increased sequentially by 18% to USD 149.3 million compared to the first quarter. This increase was largely driven by growth in the Solaris Power Solutions segment. This includes mobile, gas-powered turbines and related auxiliary equipment. Net profit reached USD 24 million. This corresponds to an EPS of USD 0.30, while the adjusted pro forma net profit amounted to USD 25 million or an EPS of USD 0.34. Total adjusted EBITDA increased sequentially by 29% to USD 61 million. Meanwhile, experts had only expected sales of USD 123.43 million and EPS of USD 0.18.
The Group is planning an ambitious expansion of its power plant fleet from the current 600 MW to 1,700 MW by Q2 2027 in order to meet the growing demand for energy solutions, particularly for data centers. The order backlog, which already covers around 75% of the available capacity through contracts or advanced negotiations, offers a promising outlook.
Bill Zartler, the company's CEO, expressed his satisfaction with the performance and highlighted the expansion of the power plant fleet, the accelerated energy supply for a data center project and the acquisition of new customers. For Q3 2025, Solaris Energy Infrastructure increased its guidance for adjusted EBITDA to USD 58 to 63 million (previously USD 55 to 60 million) and set a similar guidance of USD 58 to 63 million for Q4 2025. Management expects continued strong growth in the Power Solutions segment. From a financial perspective, the company is in a solid position to finance its growth strategy. The company has approved a dividend of USD 0.12 per share for Q3 2025, representing the 28th consecutive dividend payment. The company's net debt is estimated at approximately USD 730m, which represents a healthy debt to EBITDA ratio compared to adjusted net EBITDA of USD 440m to USD 465m. The company's capital plans indicate that Solaris should generate significant free cash flow from the end of 2026, once the 1.7 GW fleet is fully operational.
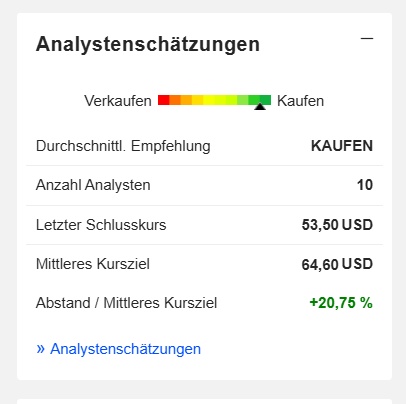
Piper Sandler raises Solaris Energy Infrastructure's share price target to USD 65
Piper Sandler raises Solaris Energy Infrastructure stock price target to $65 By Investing.com
USD in millions
estimates
Year Turnover Change
2025 609,2 94,57 %
2026 763 25,26 %
2027 1.058 38,64 %
Year EBIT Change
2025 146 161,19 %
2026 247,9 69,81 %
2027 433,5 74,91 %
Year Net result Change
2025 59,03 273,44 %
2026 82,7 40,09 %
2027 163,6 97,82 %
Year Net debt Change
2025 785 289,63 %
2026 1.128 43,69 %
2027 1.023 - 9,31 %
Year Free cash flow Change CAPEX
2023 64,39
2024 188,4
2025 -550,1 -326,24 % 797
2026 -285,8 48,03 % 595
2027 163 157,04 % 295
CAPEX 2023 64.39
CAPEX 2024 188.4
Year EBITDA margin (%) EBIT margin (%) ROE
2025 40,25 % 23,96 % 19,07 %
2026 49,64 % 32,48 % 21,21 %
2027 56,56 % 40,98 % 31,18 %
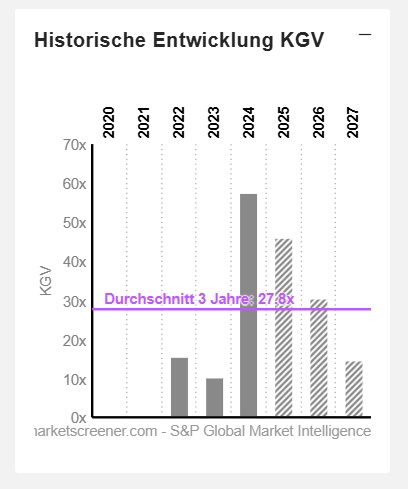
Year P/E ratio PEG
2025 46.1x 0x
2026 30.4x 0.6x
2027 14.7x 0x
Year Earnings p share
2025 1,16
2026 1,76
2027 3,637
Market value 2,611