Keyence ($6861 (-0,2 %)) is not a classic hardware trade, but a structural bet on the total automation of global industry and its unstoppable need for efficiency.
Industrial automation is only the tool here. The real value comes from a unique fabless model, radical direct sales and unrivaled pricing power. pricing power.
Margin instead of mass, problem solving instead of product sales, cash flow instead of capital commitment.
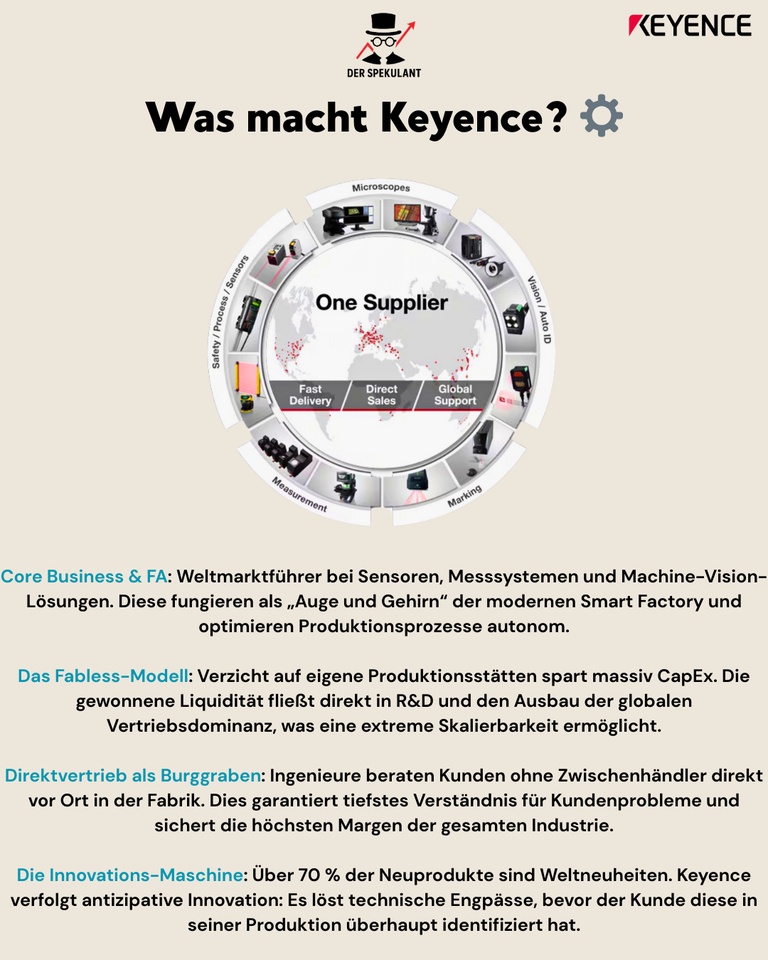
⚙️ What does Keyence do?
➡️ Core Business & FA (factory automation):
World market leader in sensors, measuring systems and machine vision solutions. Keyence provides the "eye and brain" of the modern smart factory. The products are essential for autonomous production.
→ Technology leadership + Indispensability.
➡️ The fabless model:
Keyence does not produce itself. By outsourcing production, the company makes massive CapEx savings and remains extremely agile. The capital flows primarily into R&D and sales.
→ Maximum scalability + asset-light structure.
➡️ Direct sales as a moat:
No middlemen. middlemen. Highly specialized engineers advise customers directly on site at the factory. This creates deep trust and secures the highest margins in the entire industry.
→ Deep customer understanding + enormous pricing power.
➡️ The innovation machine:
Over 70% of new releases are world firsts. Keyence anticipates industry problems before customers have even identified them themselves.
→ continuous competitive edge + high barriers to market entry.
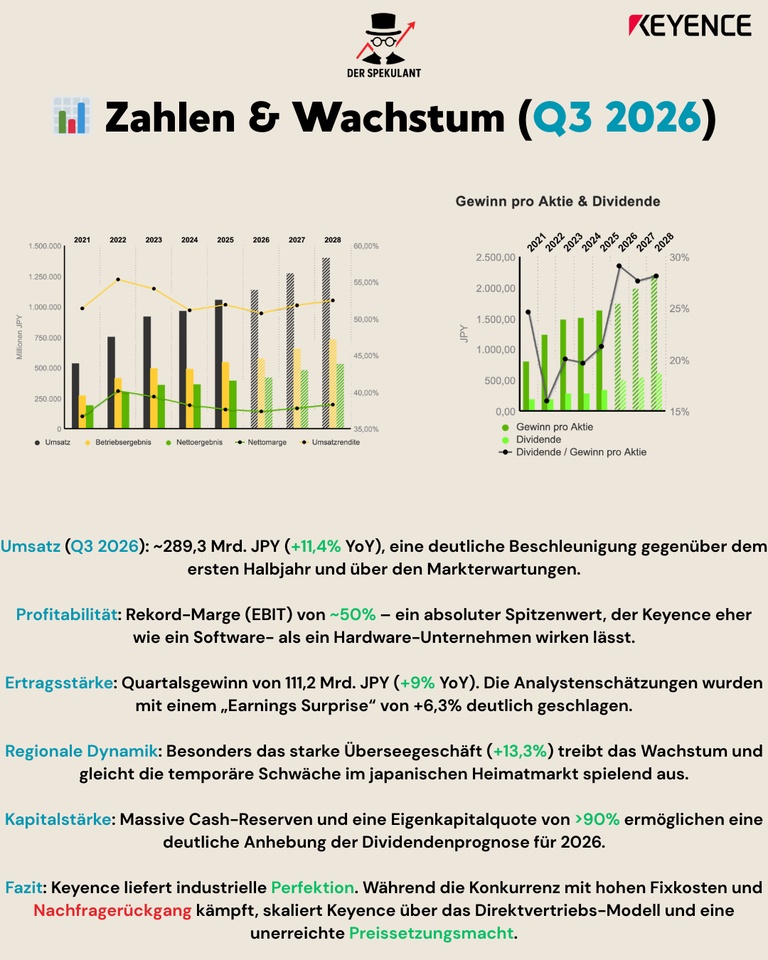
📊 Figures & growth (Q3 2026 - reported 29.01.26)
📈 Quarterly sales Q3:
~289.3 billion JPY (+11,4% YoY) → significant acceleration and outperformance compared to market expectations.
📊 9-month sales:
At JPY 834.6 billion (+7,7% YoY), the company is heading unerringly towards a new record year.
📈 Profitability:
Record operating margin (EBIT) of ~50% → An absolute peak value that makes Keyence look more like a software company than a hardware company.
👥 Regional dynamics:
The strong overseas business in particular (+13,3%) is driving growth and easily offsetting the temporary weakness in the Japanese domestic market.
💰 Capital strength:
Massive cash reserves and an equity ratio of >90% enable a significant increase in the dividend forecast for 2026.
Conclusion: Keyence delivers industrial perfection in numbers. While competitors struggle with fixed costs, Keyence scales through efficiency and desirability.
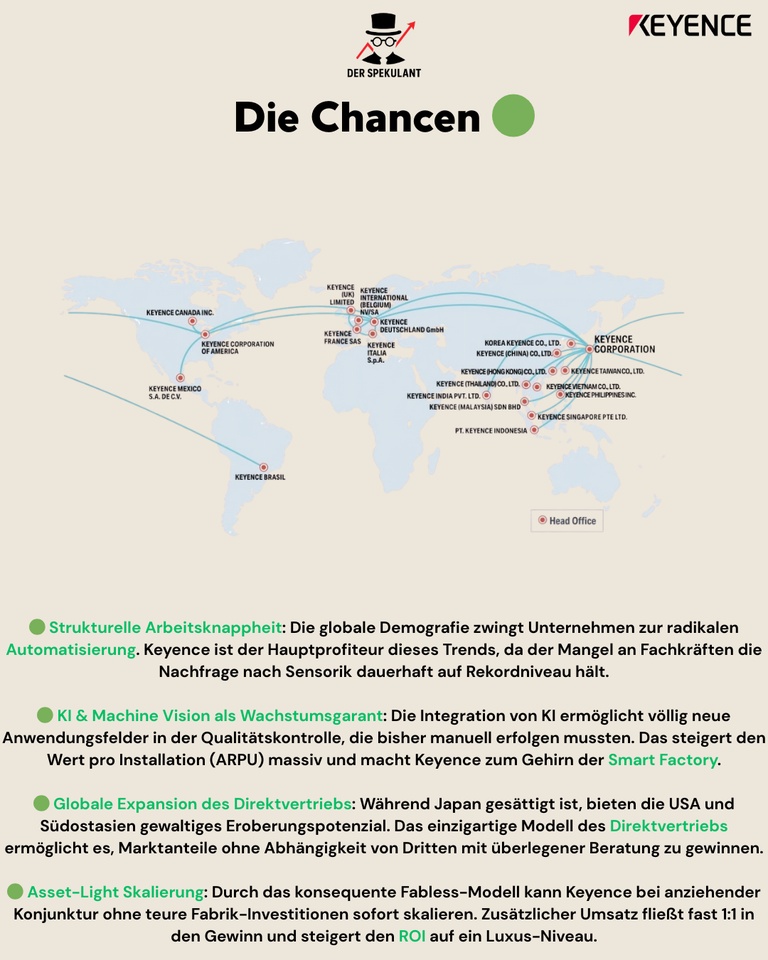
🟢 The opportunities
🟢 Structural labor shortage:
Global demographics are forcing companies to automate. Keyence is the natural beneficiary of the skills shortage in Japan, China and Europe.
🟢 AI & machine vision as a guarantee for growth:
New vision systems with AI support increase the value per installation (ARPU) and open up new markets in automated quality control.
🟢 Asset-light scaling:
During an economic upturn additional turnover flows almost 1:1 into the profit, as no expensive investments in own factories are necessary.
🟢 Global expansion:
The unique direct sales model still offers enormous potential for conquering traditional retail in the USA and South East Asia.
🔴 The risks
⚠️ Cyclical dependency:
Keyence depends on the investment cycles of the automotive and semiconductor industries. A global recession puts a direct brake on demand.
⚠️ Currency headwinds (yen):
As the majority of growth is generated outside Japan, a strong yen leads to negative translation effects. translation effects on earnings.
⚠️ China cluster risk:
A significant proportion of demand comes from China. Geopolitical
tensions or local phases of weakness have a direct impact on international momentum.
⚠️ Sporting assessment:
Quality has its price. The high
P/E RATIO leaves room for corrections in the event of the slightest operational disappointment or slower growth.
💡 Conclusion & outlook
Keyence is not a short-term hardware trade, but a structural bet on global automation of the next decade.
🔹 Short term:
Sensitive to the general valuation level (P/E ratio), global currency effects and market sentiment towards quality stocks.
🔹 Long-term:
ROI machine with a deep technological moatextreme pricing power and an operating marginthat is unparalleled worldwide.
🎯 Investment case:
Leverage on skills shortage + smart factory + AI sensor technology + maximum margin efficiency→ Structurally value-enhancing, operationally highly profitable, the gold standard for the portfolio in the long term.
💬 Community question:
👉 Japan's most profitable tech champion as a defensive anchor in the portfolio
or
👉 currently too expensive for a new entry at this P/E ratio?
I am curious about your assessment 👇