2J·

Sell off some, but never sell everything 🐜🪱

It was about time I made my $ACN (+1,75 %) position by cut in half. As competition has intensified, competition . However, my main reason for selling was to risk minimization … not because I had somehow concluded that ACN’s engine was broken. In fact, everything is still running smoothly there.


After the split, the stock is trading at approximately 2.35% of my portfolio. In my opinion, that’s a healthy position size.


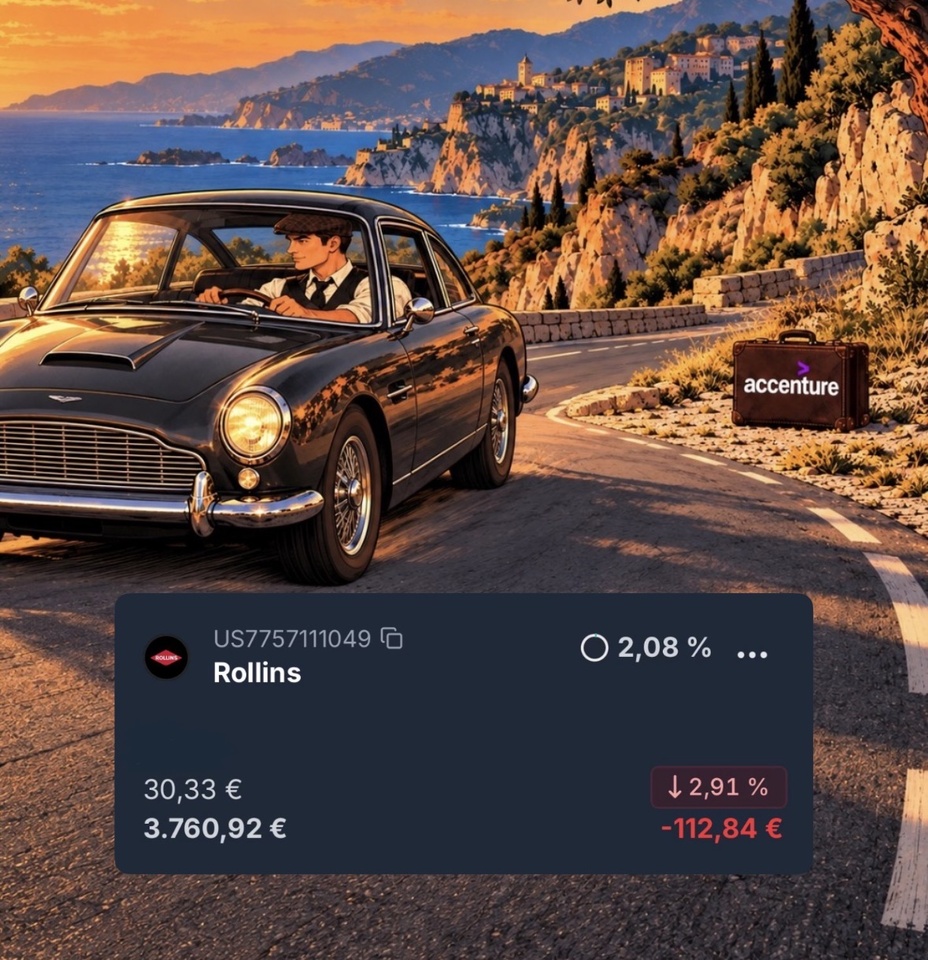
With the proceeds, I bought the overvalued stock of $ROL (+0,69 %) .


The operating growth of the pest control company has been… actually pretty good. However, the stock is ultimately facing operational hurdles . The reasons for this were:


  • AI-powered marketing: By using AI tools instead of traditional search engines to find providers, Rollins saw a sharp decline in digital customer inquiries in the consumer sector.
  • Margin Pressure and Rising Costs: Significantly higher personnel and insurance costs, coupled with a declining gross margin, weighed on profitability.
  • Disappointing Results and Lowered Forecast: Falling short of market estimates and a reduced annual forecast hit the already highly valued stock hard.


Over the past decade, the market has consistently assigned Rollins an excessively high P/E ratio of 50 or more . In the long run

No, you didn’t misread that 🙃


One reason for this was precisely the defensive nature and the sustainability of contracts and revenue.

No matter what the state of the economy is: hygiene and the elimination of insect infestations, termite infestations, and the like are a MUST (requirement) for hotels, restaurants, hospitals, pharmaceutical companies, consumer goods companies, etc.


That means: It has to be taken care of. And that’s where ROLLINS comes in.

And other companies, such as $ECL (+0,93 %)


I have a P/E ratio of ~30 for Rollins after the stock had nearly halved in value.


My new Rollins position currently yields about 2.1% of my portfolio. So it won’t hurt if the stock continues to underperform for a little while longer.


The stock itself might still be overvalued ... and in my opinion, it is, if you look at the other metrics like P/E, P/B, P/C... (you know the drill).


Compared to valuations over the past decade , however, the figures are now significantly lower because in the past, investors paid a premium for quality of the company. With a valuation like that, it’s also harder for the company to impress, because expectations are too high… which, in a way, makes a bit of sense.


Be that as it may… the future will decide whether something will pay off or not.


Do you have Rollins in your portfolio?
attachment
27.10
Accenture logo
a vendu x20 à 220,10 €
4 402,00 €
99,10 %
20
17 Commentaires

image de profil
Congratulations on the double! 😉
•
5
•
image de profil
@Part_Time_Joe Thanks, I think there's a lot more potential there.
•
1
•
image de profil
@PoorDad Yeah, that's definitely possible! But to be honest, I'm having a bit of a hard time with it these days, which is why I've sold all the shares I bought on my own. I'm still profiting from the employee stock, though. So, if the price keeps going up... I don't mind 😉
•
1
•
@Part_Time_Joe Can you do it at $ACN?
••
image de profil
@Johannes12345 Unglücklicherweise... 😂
•
1
•
@Part_Time_Joe What do you mean, "unfortunately"? So what don't you like about your job? 😅
••
image de profil
@Johannes12345 I don't even know where to start. It's just incredibly boring. I used to work at ACN Strategy (the strategy consulting division). The projects have nothing to do with strategy, and the focus on AI and so on is just marketing. A large part of the business is mindless implementation work or business process outsourcing. Anyway... you’re not likely to find professional fulfillment there. It’s a huge corporation, and just as opaque as you’d expect. You can use that to your advantage... 😂
•
1
•
@Part_Time_Joe Okay, I can understand the whole "mindless implementation work" thing. At least $ACN has come up in conversation with us quite a few times as a consulting firm, specifically for implementation. But the field doesn't seem all that versatile or exciting in general, which is why consulting is absolutely not for me 😅😂
•
1
•
image de profil
I would buy $ACN if there were another significant drop like the ones we've seen in the recent past ✌️ Congratulations on the excellent returns
•
1
•
image de profil
@emppsb From a financial standpoint, the current price would also be a bargain. The only question is how much damage the biggest fear—(Anthropic)—could cause.
•
1
•
image de profil
@PoorDad it’s far from ath so yeas still a good entry point , but.. people who bought around 120 , sooo good. I thin $ACN will survive because consultancy it’s not going anywhere
••
As of today, $ROL is indeed part of my portfolio. It’s a long-term performer with solid dividend growth that’s finally available at a reasonably good price. I’m convinced that it will continue to bring us a lot of joy in the long run.
•
1
•
image de profil
@Baisse-Jumper From a financial metrics perspective, the price isn't really reasonable, but the market has always been willing to pay a high P/E ratio for Rollins. That said, compared to its direct competitor $RTO, Rollins looks like a prime example of a top-tier company…
I also think Rollins is going to be a lot of fun👍🏽
•
1
•
@PoorDad Auf welcher Grundlage ist die Aktie aus deiner Sicht überbewertet ?

Laut Alphaspread:

The DCF Value for Rollins Inc (ROL) under the Base Case is 44.58 USD. Compared with the current market price of 33.4 USD, the stock appears UNDERVALUED by 25% .

Key assumptions:
Revenue Growth 7.8% lower than 5Y Historical 11.7%; close to Wall Street 5Y 8.5%
Net Margin 14.9% close to 5Y Historical 14.1% and Wall Street 5Y 15.5%
••
image de profil
@CashflowG Take a look at the individual metrics, and you'll see what I mean.
••
image de profil
In historical terms, it's much more undervalued, in my opinion
••
image de profil
A stylish car on a cool route through beautiful countryside. That’s where the trip has to go... 😉
••
Participez à la conversation