7Mo·

The share on Sunday, Business with SSD memory controllers is booming

Hello my dears,

Sunday is often the day for horse racing. That's why there's a racehorse for you today and, as promised, for dear @Get_Rich_or_Die_Tryin .


That's why I've looked at points that are important to him:


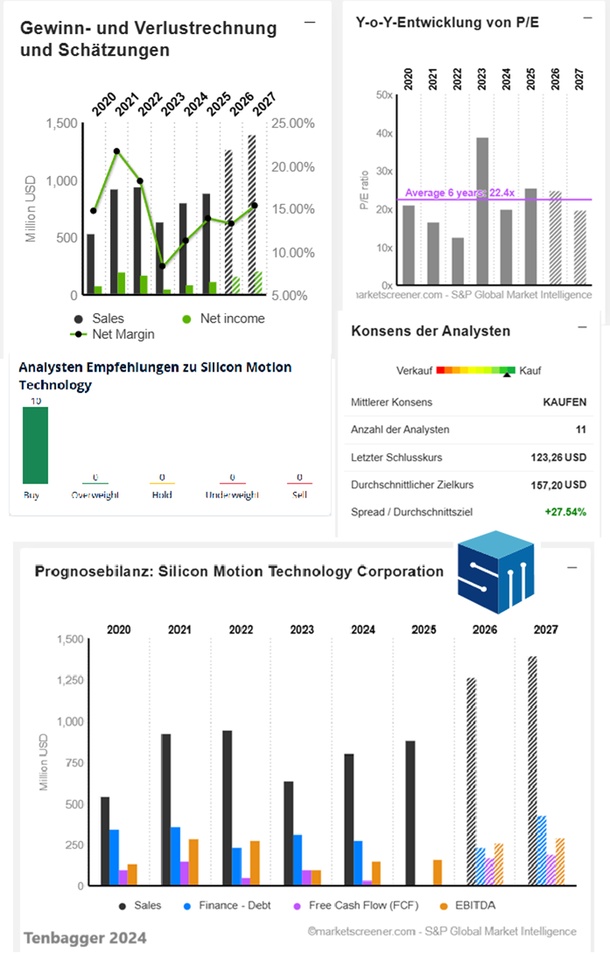
  • The EBIT margin rises to almost 20%
  • Net sales increase in the double-digit range
  • Profit growth is higher than sales growth
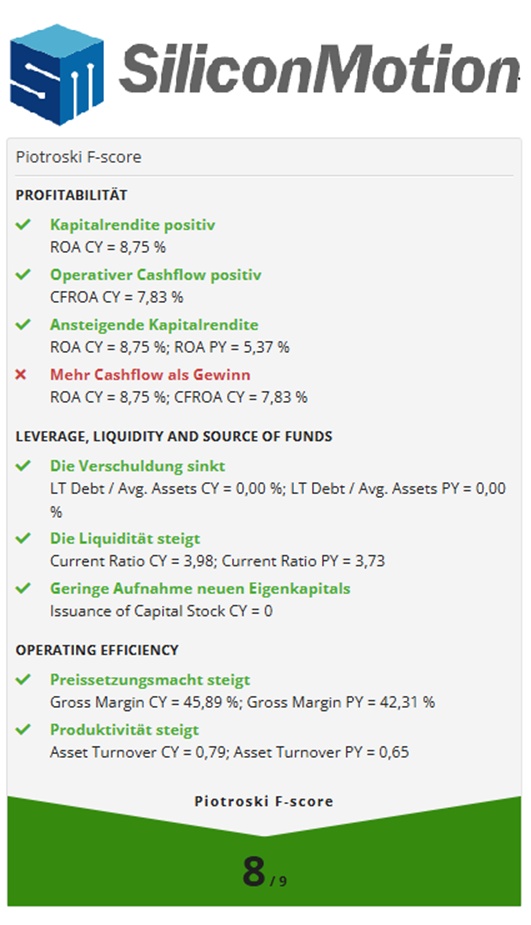
  • Debt free
  • Free cash flow growth in the triple-digit range
  • Dividend yield of almost 2% (which is rather a rarity in the semiconductor sector) @Dividendenopi
    @SAUgut777
    @Max095


Customers such as Samsung, Micron and SK Hynix are currently unable to keep up with the high demand for memory chips. This is driving up margins.

Micron's figures are due on Wednesday, which could give the sector a further boost.


My dears,

your opinions in the comments.


$SIMO (-4,81 %)

SILICON MOTION TECHNOLOGY CORPORATION is a provider of negative-AND (NAND) flash controllers for solid state drives (SSDs) and other solid-state storage devices. The Company is principally engaged in the design, development and sale of low-power semiconductor solutions for original equipment manufacturers (OEMs) and other customers in the mobile storage market. The company is mainly engaged in the development of NAND flash controller integrated circuits (ICs) for semiconductor storage devices and specialty radio frequency (RF) ICs for mobile devices. In the mobile memory market, the company's products are controllers used in SSDs, embedded multimedia cards (eMMCs) and other embedded memory products, as well as flash memory cards, Universal Serial Bus (USB) flash drives and other expandable memory products. The company's products are used in smartphones, tablets, personal computers (PCs) and other devices. In addition, the segment offers Others segment offers solutions such as embedded graphics processors. These processors are used in various fields of application, such as servers, workstations and commercial and industrial products.

Number of employees: 1,819


Silicon Motion Technology: Business with SSD memory controllers is booming - sales to leading GPU manufacturers started!

04,02,2026


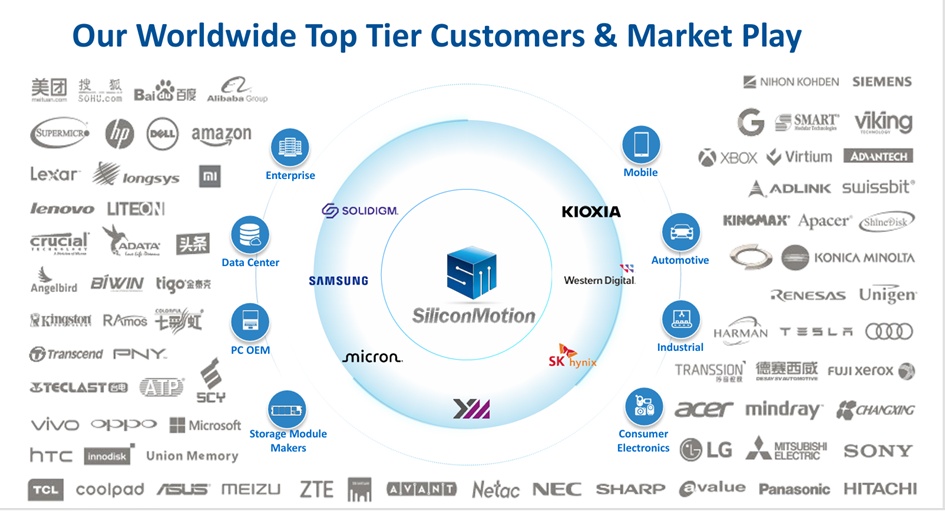
As a leading supplier of NAND flash controllers for solid-state storage devices (SSDs), Silicon Motion Technology (SIMO) is benefiting from the current high demand for memory. As the "brains" of SSDs, the technologies are crucial for data communication between the memory and the computer. They play an important role in the generated storage bandwidth, energy efficiency and even the service life of the storage products. Customers include leading NAND flash manufacturers such as Micron, SK Hynix, Samsung and Kioxia.

With a high order backlog and an expected acceleration in growth, CEO Wallace Kou now confidently emphasizes: "Looking ahead to 2026, our momentum in growing our market share, expanding our customer and product portfolio and opening up new markets is stronger than ever before." The business with client SSDs for PCs, laptops and notebooks achieved strong sequential growth of over 25%. The eMMC/UFS business for smartphones, tablets and embedded devices also grew by up to 5% quarter-on-quarter with further market share gains and new customer wins.

New growth potential is also provided by the enterprise business with data centers, where the first sales of fully assembled boot drive storage products for the server startup process were sold to a leading GPU manufacturer. The 4th quarter saw impressive year-on-year growth of almost 46%. The sales forecast signals an acceleration in growth to between 76 % and 84 %. The trend could continue with a breakout to an all-time high.
attachment

March 12, 2026 at 9:00 a.m. EDT

Silicon Motion launches the SM8008, the industry's first purpose-built PCIe Gen5 controller for enterprise boot drives and ultra-power-efficient storage
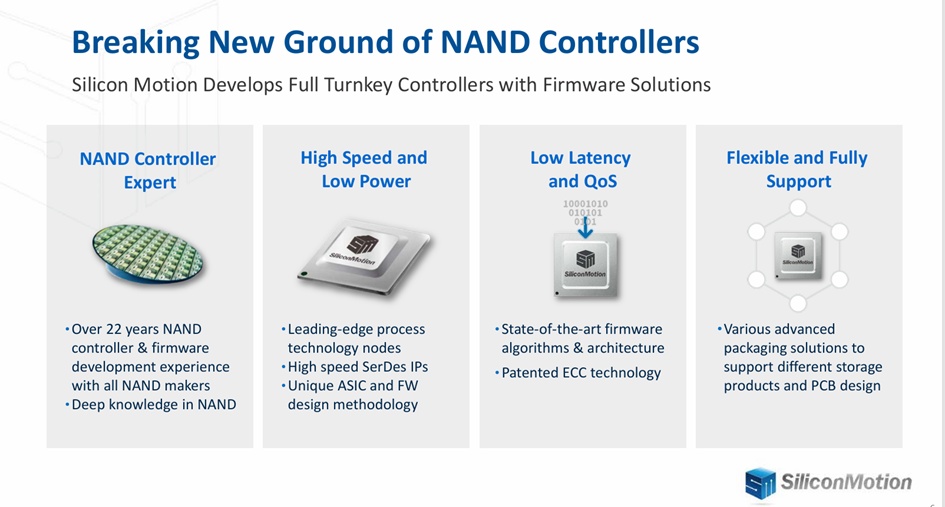
Silicon Motion bringt SM8008 auf den Markt, den ersten speziell entwickelten PCIe-Gen5-Controller der Branche für Enterprise-Bootlaufwerke und Ultra-Low-Power-Speicher – Silicon Motion Technology Corporation

attachment

February 4, 2026 at 7:00 a.m. CST

Silicon Motion Announces Results for the Fourth Quarter and Year Ended December 31, 2025

Business Highlights

  • Fourth quarter 2025 sales increased 15% quarter-over-quarter and increased 46% year-over-year
  • SSD controller sales: Q4 2025 increased 25% to 30% quarter-over-quarter and 35% to 40% year-over-year
  • eMMC+UFS controller sales: In Q4 2025, the number of controllers increased by 0% to 5% quarter-on-quarter and by 50% to 55% year-on-year
  • SSD solution sales: In Q4 2025, the quarterly semester increased by 125% to 130% and year-on-year by 110% to 115% year-on-year
  • Announced annual cash dividend of $2.00 per American Depositary Share ("ADS")


Silicon Motion gibt Ergebnisse für das vierte Quartal und das am 31. Dezember 2025 endende Jahr bekannt – Silicon Motion Technology Corporation


January 28, 2026 at 12:16 p.m. EST

Silicon Motion recognized as a 2026 Clarivate Top 100 Global Innovator

Silicon Motion wurde 2026 als eines der Clarivate Top 100 Global Innovator ausgezeichnet – Silicon Motion Technology Corporation


November 14, 2025 at 9:00 am EST

Silicon Motion announces SM8388, the industry's leading power-efficient PCIe Gen5 8-channel enterprise SSD controller that delivers 14.4 GB/s performance at less than 5W power for near SSDs

Silicon Motion kündigt SM8388 an, den führenden energieeffizienten PCIe Gen5 8-Channel-Enterprise-SSD-Controller der Branche, der 14,4 GB/s Leistung bei weniger als 5 W Leistung für nahegelegene SSDs liefert – Silicon Motion Technology Corporation


August 5, 2025 at 9:00 a.m. EDT

Silicon Motion showcases MonTitan™ SM8366 in core-to-edge AI server applications at FMS 2025

Silicon Motion präsentiert MonTitan™ SM8366 in Core-to-Edge-KI-Serveranwendungen auf der FMS 2025 - Silicon Motion Technology Corporation


Silicon Motion 4Q25 Earnings Highlights NASDAQ: SIMO February 4, 2026

Silicon Motion 4Q25 Earnings Presentation

COMPANY PROFILE

attachment
attachment


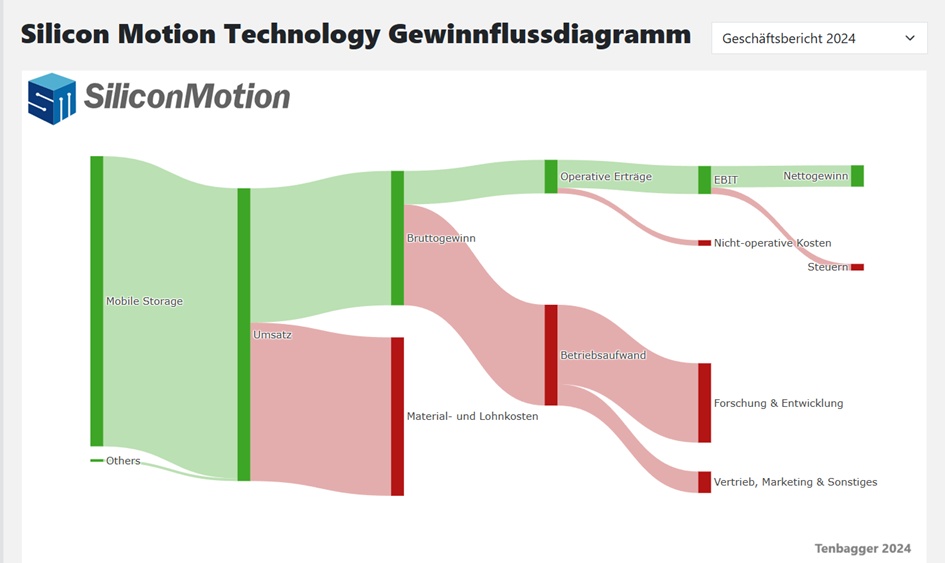
Geographical breakdown of sales:

(year 2024) USD

China 332 million

Other 180 million

Singapore 145 million

Korea 73.06 million

Taiwan 58.11 million

USA 13.02 million

Malaysia 3.59 million


USD in millions

Estimates

Year Net sales Change

2024 803,6 25,72 %

2025 885,6 10,21 %

2026 1,268 43,12 %

2027 1,394 9,98 %

2028 1.690,11


Year EBIT Change

2024 123,1 61,53 %

2025 132,3 7,47 %

2026 221,4 67,37 %

2027 266,7 20,45 %


Year Net result Change

2024 90,72 71,58 %

2025 122,6 35,18 %

2026 168,1 37,08 %

2027 213,7 27,13 %


Year Net debt CAPEX

2024 -276 44,19

2025 -214 67,13

2026 -230 45,25

2027 -42 50,35


Year Free cash flow Change

2024 33,01 -66,5 %

2025 18,6 -43,65 %

2026 169,1 809,01 %

2027 192,7 13,97 %


Year EBIT margin ROE

2024 15,32 % 15,38 %

2025 14,94 % 14,08 %

2026 17,47 % 22,07 %

2027 19,13 % 24,01 %


Year EPS Change

2024 2,69 70,25 %

2025 3,64 35,32 %

2026 4,937 55,89 %

2027 6,261 26,81 %

2028 10,35


Year Dividend Yield

2024 2 3,7 %

2025 1,686 1,37 %

2026 1,991 1,62 %

2027 2,356 1,91 %


Year P/E ratio PEG

2024 20.1x 2.37x 0.3x

2025 25.5x 4.83x 0.7x

2026 25x 4.31x 0.4x

2027 19.7x 3.73x 0.7x

Market value 4.189

Number of shares (in thousands) 33.984

Date of publication 02,03,2026
attachment
attachment


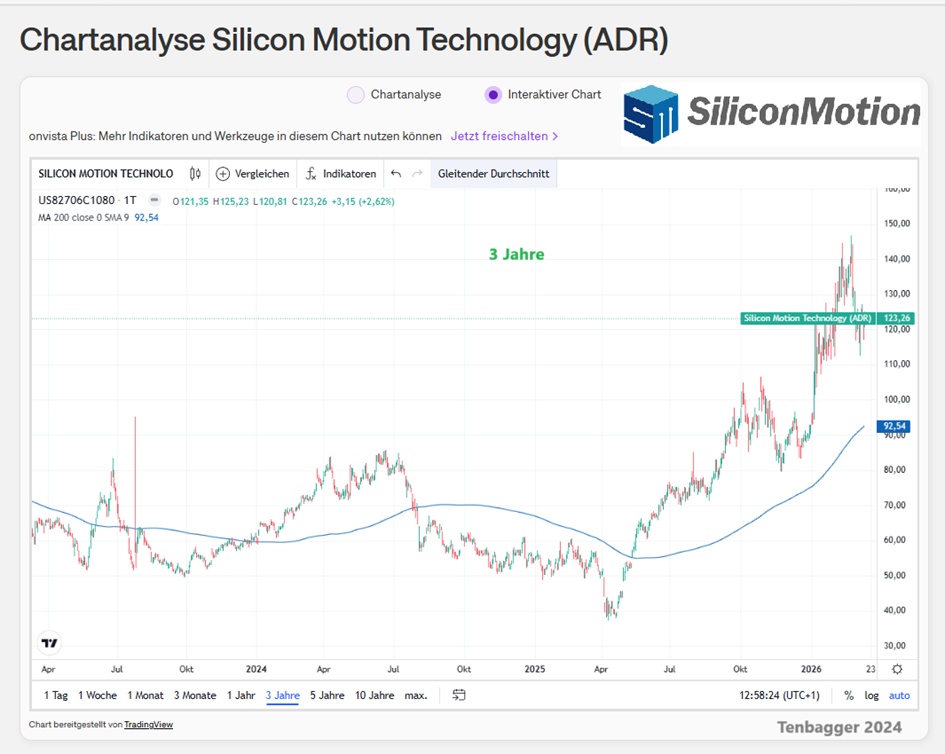
Performance

1 week +4.15 %

1 month -9.55 %

6 months +38.92 %

1 year +139.57 %

3 years +101.52 %
attachment


@Klein-Anleger
@Multibagger
@Hotte1909
@NichtRelevant
@schlimmschlimm
@Liebesspieler
@Raketentoni etc.


$SIMO (-4,81 %)

39
24 Commentaires

image de profil
You've really put a fine racehorse on the track for Sunday! Silicon Motion (SIMO) is a highly exciting pick that fits right in with the current AI and data center fantasy. As you know, my AI assistant "Mr. Prompt" not only looks at the story, but also runs every horse relentlessly through our quality scanner.

Let's do the math on the numbers you provided:

🔬 The tough formula check for SIMO
1. the core quality formula (sales growth + operating margin = score)
You mentioned the huge growth for 2026. Let's take your exact estimates for this year:

Sales growth (2026e): 43.12 %

Operating margin (EBIT 2026e): 17.47 %

Result: An impressive score of 60.59!

Conclusion: Our rule of thumb says: anything over 25 is "very good". With over 60 points, SIMO has catapulted itself into the league of elite growth stocks. This is qualitative growth at its best, far removed from empty promises.

2. the cash flow quality formula (FCF yield = free cash flow / market cap)
Profits are opinion, cash flow is fact.

You write about triple-digit FCF growth. Your figures show a jump from USD 18.6m (2025) to a whopping USD 169.1m (2026e).

If we put this expected free cash flow in relation to the current market value (USD 4.189 bn), we end up with an FCF yield of approx. 4.0%.

Conclusion: For a pure value cash flow investment, we actually require > 5 %. But: Since the balance sheet is extremely strong (as you rightly say: virtually debt-free, they have negative net debt of USD -230m, so they are swimming in net cash!) and the growth is so high, this FCF yield is absolutely first-class for a tech racehorse!

3. the dividend issue
We know that you don't care about the dividend 😉 But for the rest of us: the roughly 1.6% yield is a great "treat" here. More importantly, this payout will be easily covered by the massive cash flow explosion from 2026.

⚠️ What's the catch? (The reality check)
The company supplies controllers for NAND flash (Micron, Samsung etc.). This entire memory market is notorious for its extreme pig cycles. They are currently surfing the perfect wave due to the AI and server boom. However, if the market is flooded with an oversupply of memory chips again in two or three years' time, the strong margins can melt away very quickly. Anyone entering this market must keep a close eye on the memory cycle.

My conclusion:
An extremely strong pick for the speculative, growth-oriented side of the portfolio! The fundamental quality (high-margin, net cash, growing) is 100% right here. Thank you for this Sunday presentation! I will definitely take a closer look at the Micron figures on Wednesday to see whether the tailwind for SIMO will continue.
•
5
•
image de profil
@Raketentoni thank you, we both understand each other better and better 😘
••
image de profil
@Raketentoni your Mister Prompt could analyze Rocket Lab. The company is really hyped by many, so I'd be interested to see if it stands up to your quality check.
I'm also invested there myself.
Many thanks in advance
••
image de profil
@capital_captain_2693 We just had this the other day, so here's a brief evaluation:

🚀 The "real rocket" for the risk side: Rocket Lab USA (RKLB)
When it comes to real, tangible growth fantasy, Rocket Lab is currently one of the most exciting stocks. The company builds rockets and satellite systems and is regarded on the stock market as the only really serious competitor to SpaceX.

Current share price: approx. USD 68.40

The fluctuation: Extremely volatile. In the last 52 weeks, it has gone from below USD 15 to almost USD 100 and now back to around USD 68.

The story (the fantasy):
The space sector (defense, communications) is exploding. Rocket Lab is currently developing the new "Neutron" rocket. This is the absolute game changer with which the company wants to get its hands on the gigantic contracts from the Pentagon and NASA in order to compete with SpaceX's Falcon 9.

The tough filter check (Core Quality):

Sales growth: approx. 38% (absolute hyper-growth).

Operating margin: Currently still negative (approx. -10 %).

Score (growth + margin): 38 + (-10) = 28.
This means that despite the negative margin, the target of 25 ("very good") for qualitative growth will be broken because sales growth is so extremely high.

Why the value does not fall through the hard exclusion rule (margin < 5%):
The operating margin is red, but the company is at a fundamental inflection point. The gross margin has improved massively to almost 40%. This proves that the pure business model itself is working. The high operating losses are currently almost exclusively due to the massive investment in the development of the new Neutron rocket. The whole thing is underpinned by full order books (backlog of around USD 1.85 billion). So there is real substance here and a huge technical moat.

The bottom line for the gamble:
P/E ratios, dividends and cash flow calculations can be completely thrown out the window here. This is a highly binary bet on engineering. If the Neutron rocket flies successfully and the orders are processed, a future giant will emerge here. If the rocket explodes on the launch pad or there are massive delays, the price will plummet. A pure, highly volatile satellite for the absolute risk side - the law applies here: Only go in with play money, where you can still sleep soundly even with -40% in your portfolio!
•
2
•
image de profil
The racehorse has already run a long way. But basically it looks very interesting.

The only thing that worries me is the usual storage cycle. Otherwise, a lot of things fit here for me. Very exciting value in any case, will end up on my watch. Margins, especially the FCF margin, could be even higher, but the growth more than compensates for this in my view.👍🏻

Never heard of it before, so thanks for introducing me, dear.🙏🏻
•
3
•
image de profil
@Get_Rich_or_Die_Tryin it has become very quiet here and hardly any comments
••
image de profil
@Tenbagger2024 But my dear fellow, we know that there is traditionally little response here at the weekend.😉 Don't let it get you down, you're one of the great assets here.🫶🏻 Alongside my newly beloved @Raketentoni and his top analyst Mr. Prompt.🚀
•
1
•
image de profil
@Get_Rich_or_Die_Tryin I think I'm blushing 😆😆😂😂😂😂
•
1
•
image de profil
@Raketentoni I would like to found a holding company with Mr. Prompt
•
1
•
image de profil
@Get_Rich_or_Die_Tryin I have gone to a lot of trouble to find a semiconductor value for you
•
1
•
image de profil
@TradingHase Hello dear, thank you for your like. It's nice that you're still here. It has become very quiet here
•
2
•
image de profil
@Tenbagger2024 Yes, that's true. But it was a bit predictable after the last escapades.
I'm extremely short of time at the moment.
•
1
•
image de profil
@TradingHase still great that you remain loyal to me
••
image de profil
Thank you very much. I also find $ENVX very exciting (and speculative 🙈)
••
image de profil
@Max095 yes, very volatile
•
1
•
image de profil
@Max095 have a look at $ELVA
••
image de profil
@Tenbagger2024 No, not yet thanks for the tip 😊
••
image de profil
@Max095 maybe I'll make an introduction
•
1
•
image de profil
@Tenbagger2024 You're welcome :)
•
1
•
image de profil
@Tenbagger2024 Have you already bought more at $CAMX?
••
image de profil
@Max095 not not. Pharma is having a hard time at the moment
•
1
•
image de profil
What is your absolute top pick as a dividend growth stock?
••
image de profil
@user1d7gf8465j461735 I'm not really a dividend investor. But maybe have a look at $INSTA
••
image de profil
•
1
•
Participez à la conversation