
Hensoldt exceeded expectations after the first nine months of 2026 and raised its full-year forecast. Revenue rose 21% to 1,863 million EUR, while adjusted EBITDA jumped 33% to 281 million EUR—according to Dow Jones, analysts had expected revenue of only about 1.81 billion EUR and EBITDA of 260 million EUR. Order intake surged by 77% to EUR 3,564 million, and the order backlog reached a new record of EUR 10,367 million. Management is now targeting approximately 2.8 billion EUR in revenue and an adjusted EBITDA margin of around 19% for 2026. The catch: Adjusted free cash flow stands at −104 million EUR after nine months, the major PEGASUS contract may not materialize until 2027, and problems at the ZEBEL logistics center are eroding confidence. Prior to the start of trading on Xetra on November 5, 2026, the stock was trading at the previous day’s closing price of 81.44 EUR—the market’s reaction to the figures is still pending. From a technical analysis perspective, the stock has been trading within a range between 63 and 97 EUR for months—only a breakout above 96.80 EUR or a break below 63.14 EUR will provide the next signal.
Key Points
- 9M revenue: 1,863 million EUR (+21%), adjusted EBITDA: 281 million EUR (+33%), margin: 15.1%
- Order intake: EUR 3,564 million (+77%), record order backlog: EUR 10,367 million
- 2026 forecast raised: approximately 2.8 billion EUR in revenue (previously 2.75 billion EUR), margin approximately 19%
- Caveats: Free cash flow of −104 million EUR, PEGASUS may not launch until 2027, ZEBEL logistics issues
- Analysts: Average price target around 92 EUR, range 60 to 105 EUR
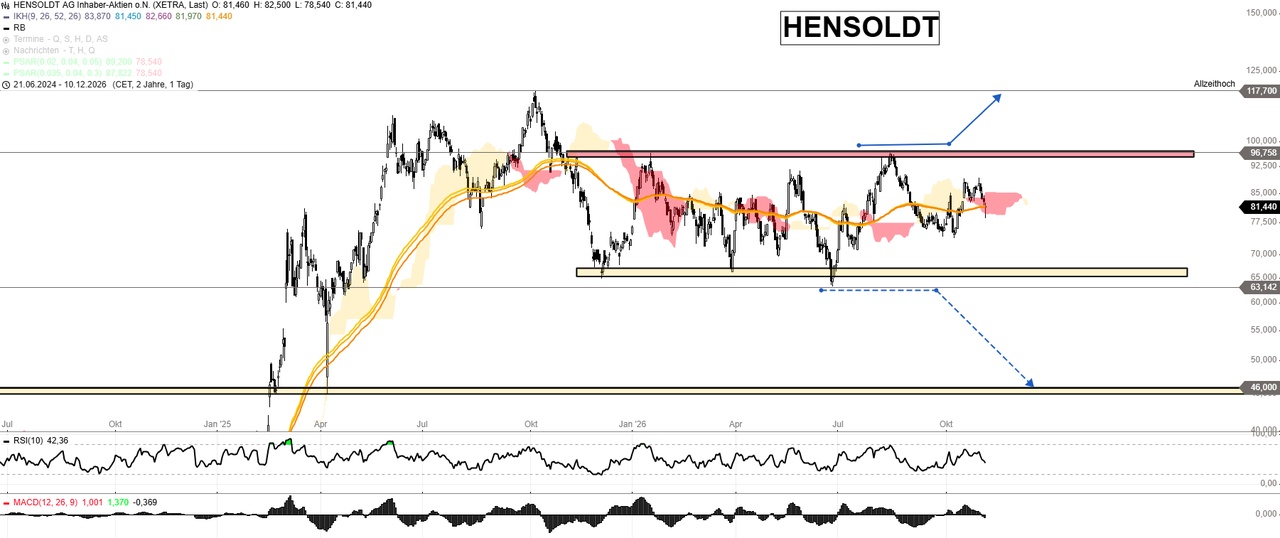
- Chart levels: Breakout above 96.80 EUR with a target of 117.70 EUR; break below 63.14 EUR with a target of 46 EUR
What are the current key metrics for Hensoldt stock?
The Hensoldt stock was trading at 81.44 EUR before the start of Xetra trading on November 5, 2026 (Xetra closing price as of November 4, 2026; down 1.7% on November 4). Since the beginning of the year, the stock has thus gained about 11%, while Rheinmetall has lost about 36% over the same period. However, it is still nearly 19% below its 52-week high of 96.70 EUR and as much as 45% below its all-time high of 117.70 EUR.
What news is currently driving Hensoldt’s stock?
Hensoldt’s stock is currently being driven primarily by strong nine-month results and an upward revision to the full-year forecast. Revenue and adjusted EBITDA exceeded analyst estimates, and the order backlog reached a new record. On the downside are negative free cash flow, the possible postponement of the major PEGASUS contract to 2027, and reports of massive disruptions at the Bundeswehr’s ZEBEL logistics center. Just how quickly defense sector euphoria can turn to disappointment has also been RENK Aktie —at Hensoldt, the stock chart will now determine the direction the company takes.
What does Hensoldt’s management have to say about the nine-month results?
CEO Oliver Dörre sees Hensoldt clearly on a growth trajectory: The structurally high defense spending in Germany and Europe “continues to fill our order books.” According to a press release, this demand is now increasingly reflected in revenue because Hensoldt is producing and delivering significantly more thanks to additional capacity. Strategically, the company aims to evolve from a sensor specialist into a “neo-systems house,” where sensors, platforms, and software work more closely together.
What went well: Adjusted EBITDA grew by 33%, significantly faster than revenue, which rose by 21%. CFO Christian Ladurner emphasizes that margins have increased in both segments—in Optronics, the margin more than doubled to 12.6%. In the third quarter alone, the adjusted EBITDA margin reached 20.6%, up from 17.6% in the prior year, and free cash flow turned positive at +32 million EUR.
The catch: After nine months, adjusted free cash flow still stands at −104 million EUR. The book-to-bill target depends on orders in the fourth quarter; the major PEGASUS order might not come until early 2027. The press release does not address reports of disruptions at the ZEBEL logistics center—and that, to me, remains the unresolved issue.
Outlook: For 2026, Hensoldt now expects revenue of around EUR 2.8 billion, an adjusted EBITDA margin of around 19%, and a book-to-bill ratio at the upper end of the 1.5x to 2.0x range. The medium-term targets have been confirmed, and the Capital Markets Day in London will take place on November 10, 2026.
What does Hensoldt do—and how does the company make its money?
Hensoldt specializes in defense and security electronics—in other words, the “eyes and ears” of modern armed forces. The MDAX-listed company, headquartered in Taufkirchen near Munich, was spun off from the Airbus Group in 2017, employs approximately 10,000 people, and generated revenue of EUR 2.46 billion in 2025. Its anchor shareholders are the Federal Republic of Germany and Leonardo.
Sensors: The largest segment supplies radars such as the TRML-4D for air defense, maritime radars, electronic warfare systems, and avionics. After nine months of 2026, Sensors generated revenue of 1,522 million EUR (+15.5%) with an adjusted EBITDA margin of 15.5% and an order backlog of approximately 7.4 billion EUR.
Optronics: This division manufactures rifle scopes, thermal imaging devices, and optronics for vehicles. This division is the growth engine: revenue of EUR 354 million (+52.4%), order intake of EUR 1,157 million (+253%), and a book-to-bill ratio of 3.3x.
Services and Logistics: Through the ZEBEL logistics center in Wolfhagen, Hensoldt manages central spare parts logistics for the Army. It is precisely this division that is currently in the spotlight due to software glitches.
Why the market remains hesitant nonetheless: Hensoldt is posting record figures, but the stock has been stuck below its record high of 117.70 EUR for over a year. The valuation is high, cash flow fluctuates significantly with project milestones, and political issues such as peace talks or delays in major contracts repeatedly cause setbacks across the entire defense sector.
Fundamental Analysis: Is the Hensoldt stock too expensive after the nine-month results?
Fundamentally, Hensoldt is strong operationally but not cheaply valued—growth is already largely priced into the share price. Based on the consensus estimate of EUR 1.87 in earnings per share for 2026, the P/E ratio stands at around 45, while Rheinmetall’s is about 31. According to Aktienfinder, the adjusted P/E ratio of 55.7 is significantly above the average of 24.5 over the past eight years.
Growth and Margins: Revenue grew by 21% to EUR 1,863 million after nine months, or 17.7% excluding pass-through revenue. Adjusted EBIT rose by 45% to EUR 177 million, with the margin increasing from 7.9% to 9.5%. Since the fourth quarter is traditionally the strongest, the full-year margin is expected to be significantly higher than the nine-month figure—Hensoldt is targeting around 19%.
Cash Flow and Debt: Adjusted free cash flow after nine months stood at −104 million EUR, compared to −119 million EUR in the prior year. For the full year, Hensoldt continues to expect a cash conversion rate of around 50% of adjusted EBITDA and a debt-to-equity ratio of around 1.5x. Just how quickly a highly valued growth stock with a record order backlog can be revalued is also demonstrated by the Siemens Energy Aktie —the key is that, in the end, cash remains.
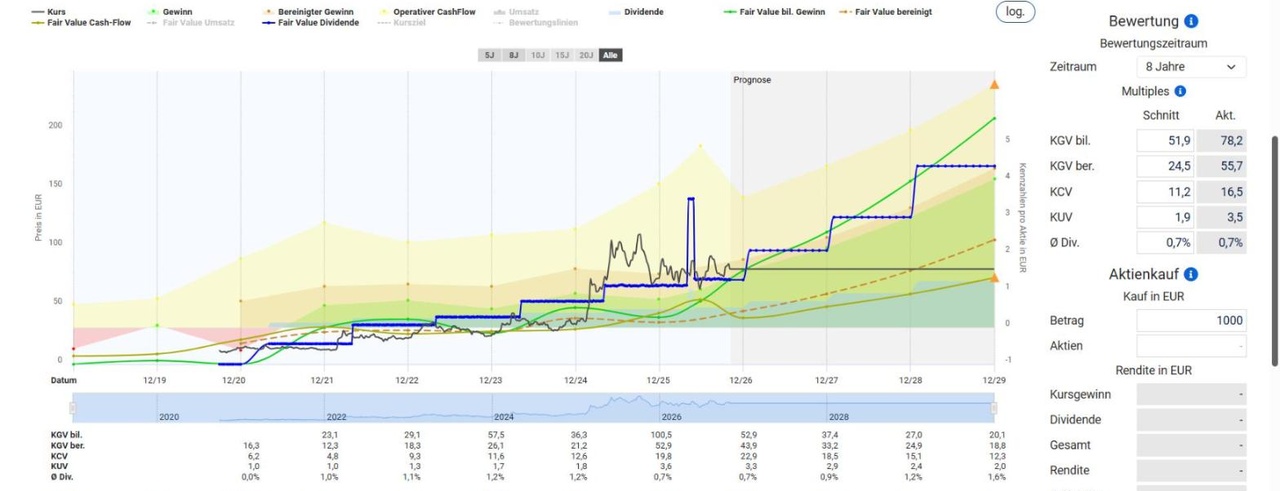
Order backlog as a safety net: At EUR 10,367 million, the order backlog is nearly four times the expected annual revenue. This secures capacity utilization for years to come and makes Hensoldt less dependent on individual quarters.
Dividend: For 2025, Hensoldt paid a dividend of 0.55 EUR per share, representing a yield of only about 0.7% at the current price. The payout ratio is expected to be between 30% and 40% of adjusted net income—Hensoldt is a growth stock, not a dividend stock.
Hensoldt Stock Price Targets and Forecast for 2026
Analysts see an average price target of around 92 EUR for Hensoldt stock, representing upside potential of about 13%. According to Aktienfinder, the consensus among 16 analysts is 90.34 EUR, while finanzen.net arrives at 94.43 EUR based on seven price targets. The range extends from 60 EUR (mwb research) to 105 EUR (Deutsche Bank). New price targets following the nine-month results were not yet available as of press time (November 5, 2026, 8:45 a.m.).
Key price levels:
- 52-week high: 96.70 EUR (January and August 2026)
- Current price: 81.44 EUR (Xetra close on November 4, 2026; data imported on November 5, 2026, at 8:45 a.m., prior to Xetra opening)
- Resistance: 96.80 EUR (red resistance zone, breakout level)
- All-time high: 117.70 EUR (October 2025, target after breakout)
- Support: 66–67 EUR (yellow support zone)
- Critical downside level: 63.14 EUR
- Short target: 46.00 EUR (yellow zone)
Analyst price targets:
- Average price target: approx. 92 EUR (Aktienfinder: 90.34 EUR based on 16 analysts; finanzen.net: 94.43 EUR)
- Deutsche Bank: Buy, 105 EUR (October 16, 2026)
- JPMorgan: Neutral, 100 EUR (August 6, 2026)
- Jefferies: Buy, 98 EUR (October 7, 2026)
- Barclays: Equal Weight, 97 EUR (June 1, 2026)
- Bank of America: Buy, 94 EUR (October 1, 2026)
- Warburg Research: Buy, 94 EUR (August 3, 2026)
- Goldman Sachs: Neutral, 85 EUR (October 6, 2026)
- mwb research: Sell, 60 EUR (October 30, 2026)
Chart Analysis:
Hensoldt’s daily chart shows a classic sideways trend: For months, the stock has been fluctuating within a wide range between approximately 63 and 97 EUR, with neither side gaining the upper hand. What stands out is its relative strength—Hensoldt is clearly outperforming Rheinmetall Aktie significantly. Since the beginning of the year, Hensoldt is up about 11%, while Rheinmetall is down about 36%.
Here, it’s important to wait for the trigger levels. On the upside, the key level is at 96.80 EUR, where the red resistance zone has so far held the stock back every time. If it breaks out above this level, I expect further buying momentum up to the record high of 117.70 EUR.
On the downside, I’m watching the EUR 63.14 level, which lies directly below the yellow support zone around EUR 66 to 67—a zone that has held on multiple occasions. If the stock falls below EUR 63.14, a downward move to EUR 46 would be a good opportunity to short the stock.
Between these two levels, Hensoldt remains a classic range-bound candidate in my view. I’ll wait until one of the two trigger levels is hit—only then will a trade with a clear direction emerge.
Opportunities and Risks of the Hensoldt Stock
Opportunities:
- ✅ Results beat consensus: Revenue of 1,863 million EUR, adjusted EBITDA of 281 million EUR
- ✅ 2026 forecast raised to approximately EUR 2.8 billion in revenue and approximately 19% margin
- ✅ Record order backlog of 10,367 million EUR secures revenue for years to come
- ✅ Optronics as a growth driver: Revenue +52%, book-to-bill ratio 3.3x
- ✅ Relative strength: up approx. 11% year-to-date compared to approx. −36% for Rheinmetall
- ✅ A breakout above 96.80 EUR opens the door to the record high of 117.70 EUR
Risks:
- ⚠️ Adjusted free cash flow after nine months at −104 million EUR
- ⚠️ PEGASUS contract may not be awarded until early 2027
- ⚠️ ZEBEL logistics issues are weighing on confidence and reputation
- ⚠️ High valuation: 2026e P/E ratio around 45
- ⚠️ Political risks, such as peace talks, are weighing on the defense sector
- ⚠️ A break below 63.14 EUR would open up downside potential to 46 EUR
Conclusion: Hensoldt Stock—Record Numbers, but When Will the Range Break?
Based on the nine-month results, Hensoldt stock is operationally stronger than ever, but from a technical perspective, it still calls for patience—I’m waiting for the trigger. Revenue and adjusted EBITDA exceeded expectations; the order backlog reached 10,367 million EUR, and the forecast for 2026 has risen to approximately 2.8 billion EUR in revenue with a margin of around 19%. At the same time, negative free cash flow, the potential PEGASUS delay, and the ZEBEL disruptions remain real headwinds.
With a P/E ratio of around 45 for 2026, a lot of growth is already priced in; the average analyst price target is around 92 EUR. From a technical analysis perspective, the outlook is clear: above 96.80 EUR, the likelihood of follow-on buying increases toward the record high of 117.70 EUR; below 63.14 EUR, there is a risk of a downward move to 46 EUR. In between, the stock remains within its range.
Anyone in the defense sector who focuses on software rather than sensor technology should also take a look at Palantir Aktie —where a very different battle is raging between growth and valuation.
Sources
- Hensoldt Press Release (EQS-News): HENSOLDT Increases Adjusted EBITDA by 33% and Revises 2026 Forecast Upward (November 5, 2026)
- EQS-News via FinanzNachrichten.de: Hensoldt’s Nine-Month Results (November 5, 2026)
- HENSOLDT Investor Relations
- dpa-AFX via finanzen.at: Hensoldt Becomes Even More Optimistic Amid the Defense Boom (November 5, 2026)
- Dow Jones via FinanzNachrichten.de: Hensoldt Reports Strong Order Intake and Improved Forecast, Including Consensus (November 5, 2026)
- Sharedeals: Do the Q3 figures justify a P/E ratio of 45? (Consensus, Valuation, Analysts)
- Heidelberg24, citing WirtschaftsWoche: Spare Parts Freeze at the German Armed Forces (ZEBEL, October 30, 2026)
- Finanztrends: mwb’s price target lowered to 60 euros (November 1, 2026)
- finanzen.net: Analyst price targets for Hensoldt
- FinanzNachrichten.de: Analyst ratings for Hensoldt
- Finanztrends: Analysts Divided Ahead of November Earnings (Goldman Sachs, Bank of America)
- EQS News via Börse Online: Annual Shareholders’ Meeting Approves Higher Dividend
- boerse.de: Historical prices for Rheinmetall
- boerse.de: Hensoldt Stock – Price, 52-Week Range, Performance
- Xetra Closing Price for Hensoldt on November 4, 2026 (Alpha Vantage, finanzen.net)
- Alpha Vantage: Daily and weekly prices for Hensoldt (HAG.DEX) and Rheinmetall (RHM.DEX), Xetra
- Stock3: Hensoldt daily chart (Xetra, EUR), as of Nov. 5, 2026
- Aktienfinder: Fair value calculation, valuation metrics, and analyst consensus for Hensoldt, as of November 5, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What are your current thoughts on $HAG (-2,81 %) ?