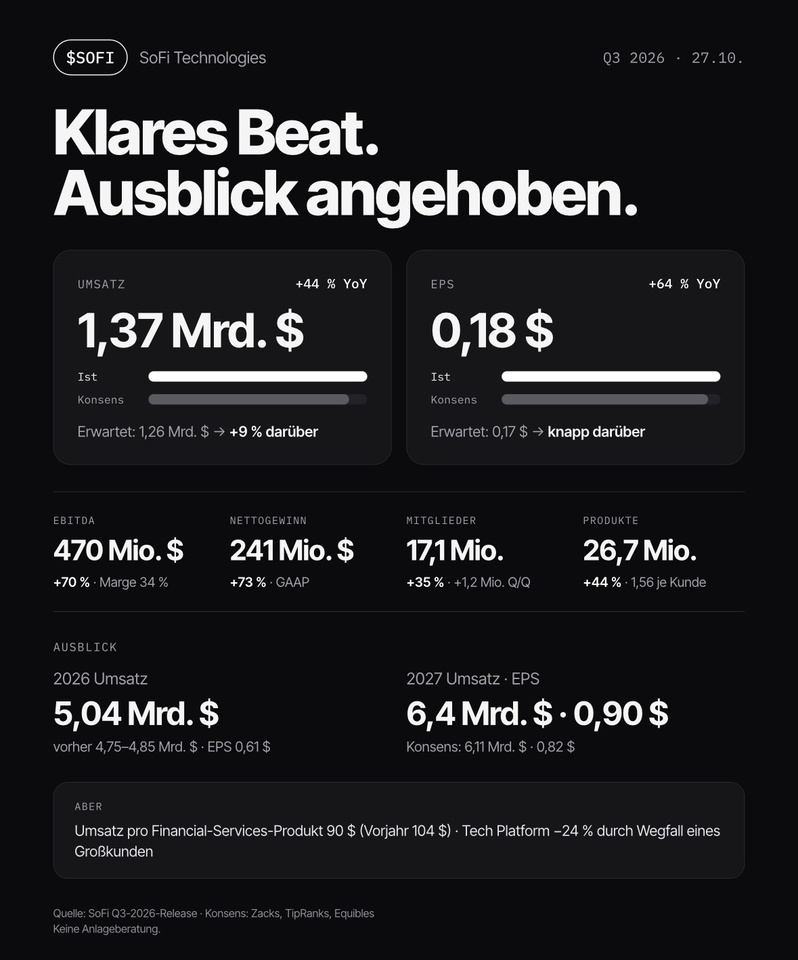
Q3 vs. Expectations
- Revenue: $1.37 billion (+44%) instead of the expected $1.26 billion (+30%). This exceeds the highest individual estimate of $1.31 billion.
- EPS: $0.18 instead of $0.17
- EBITDA: $470 million (+70%), margin 34% after 29.7% in Q2
- Net income: $241 million (+73%)
Growth
- Members: 17.1 million (+35%), record growth of 1.2 million
- Products: 26.7 million (+44%)
- Lending: A record $16.9 billion
- Deposits: $51.3 billion (+$5.8 billion for the quarter)
Outlook—Forecast Raised!
- 2026: Revenue $5.04 billion, previously $4.75–4.85 billion. EPS $0.61, previously $0.60.
- 2027: $6.4 billion in revenue (+27%) and $0.90 EPS. The consensus was $6.11 billion and $0.82.
- 2030 Target: 100 million products, plus five business segments, each with more than $1 billion in revenue.
Statements and Analysis
- CEO Noto called the results exceptional, especially given the challenging year of 2026. He said his confidence is higher than ever.
- There had been concerns beforehand that rising interest rates would weigh on earnings. However, the net interest margin actually rose to 6.14%.
- Weaker: Revenue per product in the Financial Services division fell year-over-year from $104 to $90. The tech platform lost 24% due to a major customer leaving.
- Prior to the earnings release, the stock was down about 44% year-to-date.