

In times of market panic like we’re seeing now, I believe what matters isn’t how the stock price moves in the short term, but whether you truly believe in the companies
you’re investing in.
Of course, you shouldn’t blindly trust every company.
Anyone engaged in real stock picking today can no longer afford to accept just any business model—only companies that truly perform operationally, generate cash flow, and are able to pay off their debt cleanly.
I’m extremely skeptical—and clearly on the bear side—especially when it comes to the “neo-clouds” that are so hyped right now; I don’t like these massive debt stories at all. Well, maybe I’m wrong and missing out on something, but I’ll continue to stay away.
Incidentally, this post was triggered by a classic ragebait post that actually advised some people to sell my absolute top stock. That’s why I’m providing a another, detailed overview of Zeta Global (NYSE: $ZETA (-6,54 %)
) —so everyone can decide for themselves what the company is really all about.
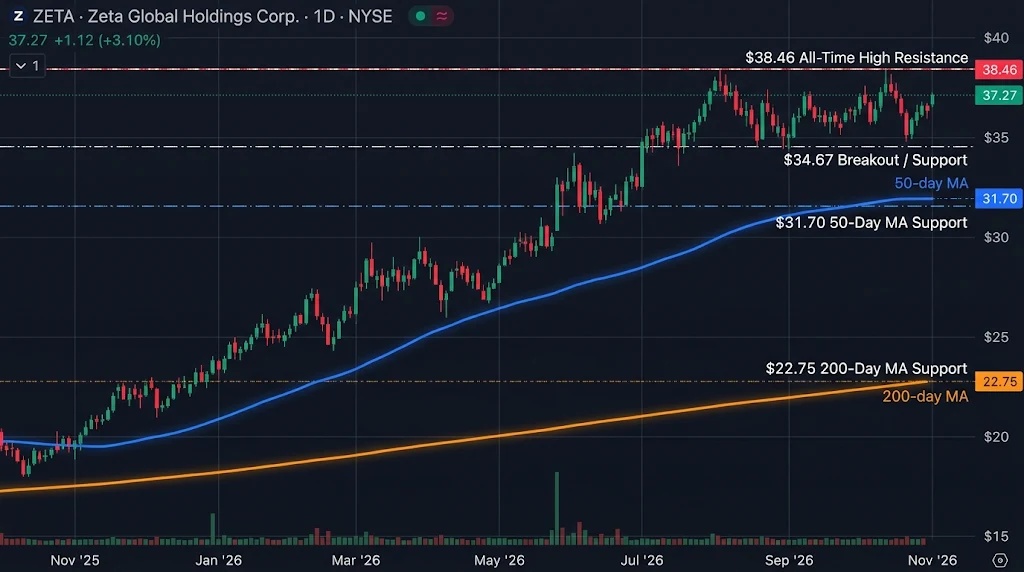
An important note up front for anyone who’s gotten interested in the stock after reading this overview and is thinking about buying in: Don’t blindly chase the price! After its strong run, it makes sense to to buy in staggered increments —that is, either wait for healthy pullbacks to key support levels (such as the 50-day moving average at around $31.70 or the breakout zone around $34.67) or to wait until after a clean breakout above the recent all-time high of $38.46 before adding to your position.
....................................................................................................................................................................................
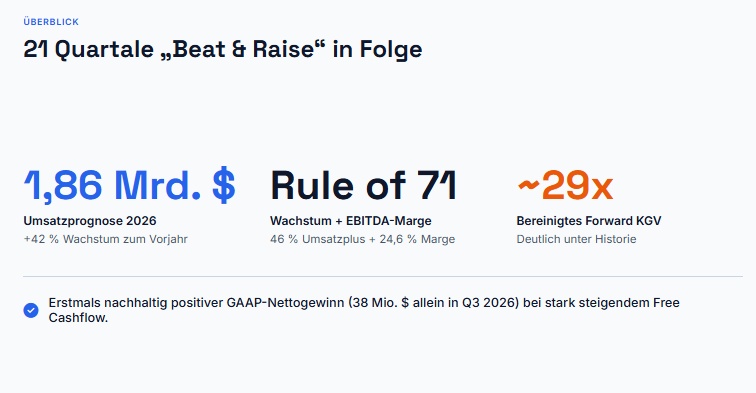
While many software companies are currently struggling to grow, Zeta Global is delivering one record quarter after another—it’s now 21 consecutive “Beat & Raise” quarters, during which the company has exceeded both its own and analysts’ expectations and raised its full-year forecast.
What exactly does Zeta Global do?
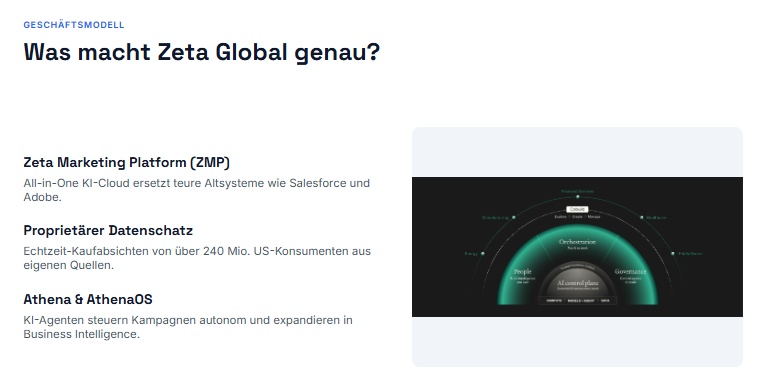
At its core, Zeta offers the Zeta Marketing Platform (ZMP) an AI-powered all-in-one marketing cloud that helps companies acquire new customers, retain existing ones, and increase revenue per customer. The key difference from established heavyweights like Salesforce or Adobe lies in the combination of software and proprietary data: Zeta has a proprietary data treasure trove containing real-time purchase signals from over 240 million U.S. consumers.
Instead of expensive, cumbersome standalone solutions, customers get a centralized platform where AI agents like Athena and the new operating system AthenaOS control and evaluate campaigns largely autonomously. This delivers measurable benefits for customers: On average, they achieve a 6:1 return on ad spend and launch campaigns about 50% faster than with traditional legacy systems.
Explosive growth in revenue, cash flow, and major clients
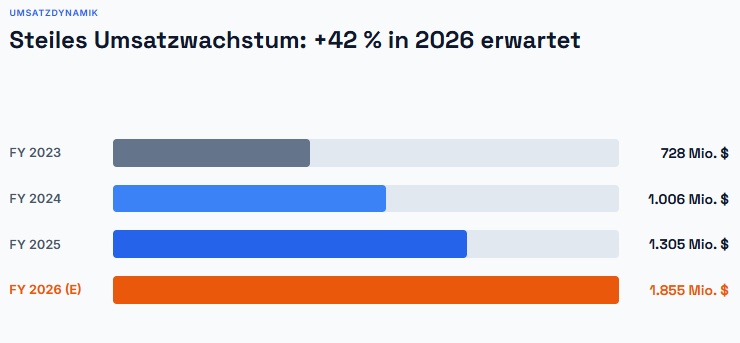
A look at the numbers shows just how well the model scales. For the full year 2026, management now expects revenue of $1.855 billion —an increase of 42% compared to the previous year (even after adjusting for acquisitions and political campaign budgets, organic growth stands at a robust 27%).
Even more impressive than the sheer revenue growth is the operating leverage behind it:
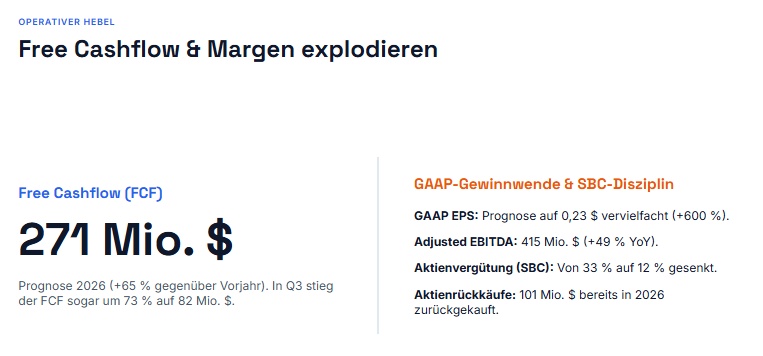
- Free Cash Flow (FCF): For 2026, $271 million is expected for 2026 (+65% year-over-year). In Q3 alone, FCF jumped 73%.
- GAAP profitability: Zeta has made the leap into sustainable profitability ($38 million in GAAP net income in Q3 alone) and has drastically reduced stock-based compensation (SBC) from 33% to around 12% of revenue.
- Rule of 71: The sum of revenue growth (46% in Q3) and adjusted EBITDA margin (24.6%) reaches a peak of over 70, the highest in the entire SaaS sector.
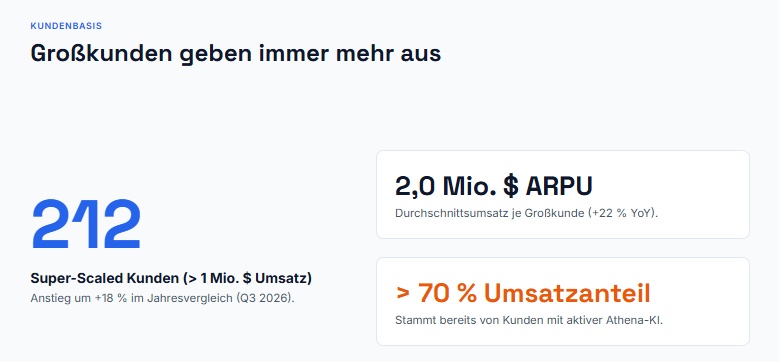
This trend is driven primarily by so-called super-scaled customers —that is, enterprise customers who spend more than $1 million per year with Zeta. Their number recently rose by 18% to 212 major customers, while the average revenue per major customer (ARPU) rose by 22% to $2.0 million . Over 70% of revenue already comes from customers who actively use the Athena AI.
Valuation: Why the GAAP P/E ratio is misleading and the adjusted P/E ratio is attractive
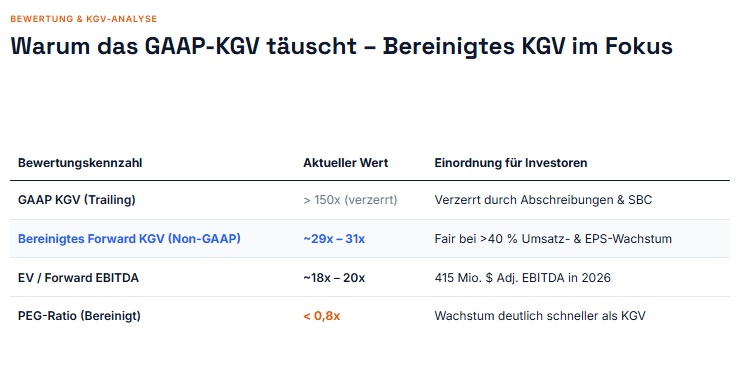
Anyone looking up Zeta’s P/E ratio on traditional financial portals is often put off by a high GAAP P/E ratio (>150x). However, this figure is heavily distorted by non-cash amortization from past acquisitions as well as historical stock-based compensation.
If, on the other hand, one considers the adjusted forward P/E ratio (non-GAAP), Zeta is currently trading at around 29x to 31x. Given revenue and earnings growth of over 40%, this results in a PEG ratio of less than 0.8 —meaning the stock is growing significantly faster than the P/E ratio would suggest. The same is true for the ratio of enterprise value to adjusted EBITDA (EV/EBITDA of approximately 18x–20x), the valuation appears moderate compared to other high-growth AI software stocks.
Acquisition Strategy: What Zeta Has Already Acquired—and What’s Next
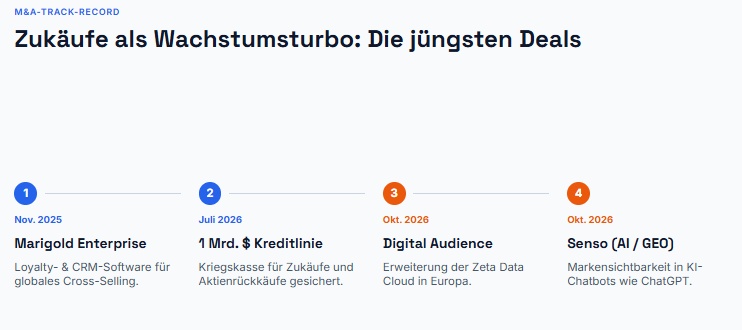
Zeta strategically uses acquisitions to accelerate growth. Following the acquisition of Marigold Enterprise in late 2025 (loyalty and CRM software), management secured a $1 billion credit line. This was immediately followed in October by the acquisitions of Digital Audience (expansion of the European data cloud) and Senso (optimizing brand visibility in AI chatbots such as ChatGPT).
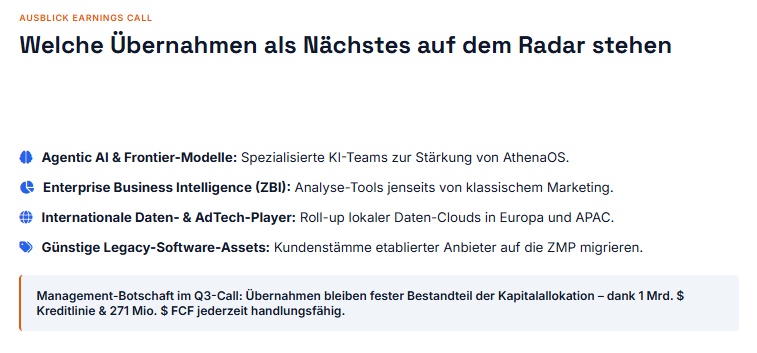
During the most recent earnings call, management explicitly emphasized that further acquisitions are not ruled out, but rather remain an integral part of capital allocation. Four areas in particular are on the radar:
Agentic AI & frontier models: Specialized AI teams for the further development of AthenaOS.
Enterprise Business Intelligence (ZBI): Analytics tools that enable Zeta to expand beyond traditional marketing into other areas of the business.
International Data & AdTech Players: Acquisition of local data clouds in Europe and Asia.
Low-cost legacy software providers: Acquisition of established customer bases, which are subsequently migrated to the higher-margin ZMP platform.
Who’s invested? Well-known figures and major investors
On the investor side, Zeta also boasts prominent “smart money”:
- John Sculley: The former CEO of Apple and PepsiCo is not only an early-stage investor but also a co-founder of the company and has been involved with Zeta since 2007.
- David A. Steinberg (CEO): The co-founder and CEO personally holds millions of shares and is known for regularly buying additional shares on the open market.
- Institutional heavyweights: Over 75% of the free float is held by large investors—including BlackRock, Vanguard, Fidelity, and Morgan Stanley and Goldman Sachs Asset Management.
Conclusion
A top niche company with enormous potential over the next few years that is heavily undervalued.
(Note: This is not investment advice, but rather a personal assessment of the company based on the Q3 2026 figures and guidance.)
