

No frills 😬
Today we’ve got another post about your health 🤧
Let’s go!
Today we’re talking about the biotech company:
🧬 Adaptive Biotechnologies $ADPT (-0,05 %) : The indomitable immunological eye of cancer medicine
Adaptive Biotechnologies $ADPT (-0,05 %) is not a traditional biotech company that searches for new molecules on a whim. It is the global technological pioneer and infrastructure monopolist in the field of immune sequencing (the precise mapping of the human immune system). While pharmaceutical giants like Bristol Myers Squibb $BMY (-0,86 %) develop cancer therapies, Adaptive—with its flagship product clonoSEQ—provides the critical, high-precision “monitoring eye” that proves the success of these therapies in the first place.
They control the leading system for detecting minimal residual disease (MRD) in blood cancers—this is the ultra-detailed checkpoint that the oncology of the future cannot bypass.
1. The Business Model: Unleashing the MRD Monopoly 🔬⚙️📈
Adaptive $ADPT (-0,05 %) controls the market through a radically scalable, proprietary tech platform:
The clinical checkpoint (clonoSEQ): When a patient with multiple myeloma or leukemia is undergoing treatment, doctors want to know: Is the cancer really gone? Conventional methods miss one in 10,000 cancer cells. clonoSEQ detects one in a million cells.
The switching costs for oncologists and clinics are extremely high: Once a patient has been profiled with clonoSEQ and is under monitoring, the doctor cannot switch systems without destroying the historical comparability of the data.
“Design-in” protection in pharmaceutical trials: When approving new cancer drugs, the FDA increasingly requires proof of “MRD negativity.” Pharmaceutical companies use Adaptive as the standard endpoint for their clinical trials (such as the groundbreaking CEPHEUS trial). Once a regulatory trial has integrated clonoSEQ, Adaptive is firmly established as the exclusive diagnostic partner for the entire global lifecycle of that drug.
The monumental breakthrough in 2026 (focus on margins): For years, the stock suffered due to the Immune Medicine division (early-phase research with Microsoft), which devoured millions as a cash burner. In mid-June 2026, management dropped a bombshell: The unprofitable research segment will be completely spun off or partnered out separately by the end of the year. What remains starting in 2027 is a clean, highly profitable, extremely fast-growing pure-play diagnostics company (Pure-Play MRD).
2. Key Figures (As of Q1/Q2 2026 / FY Trend) 📊
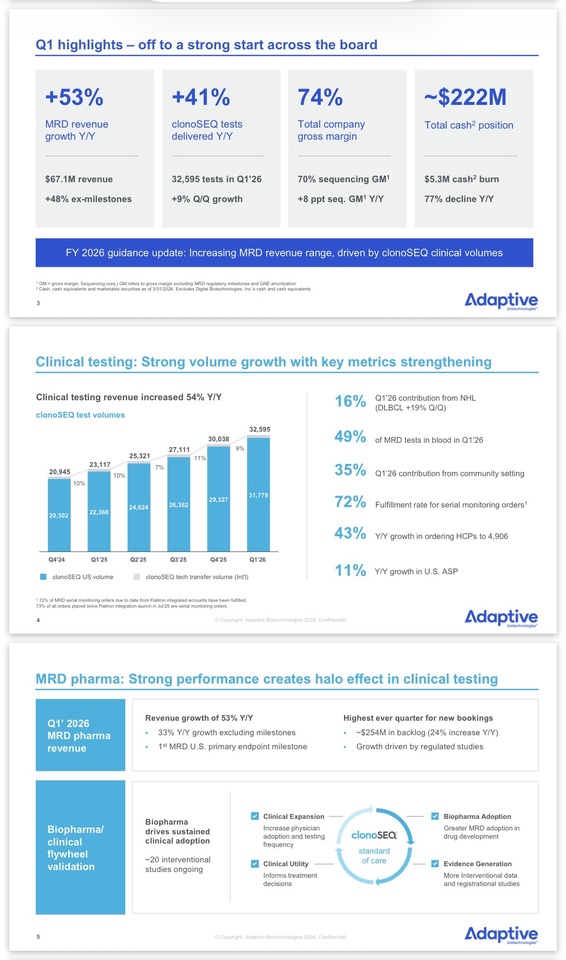
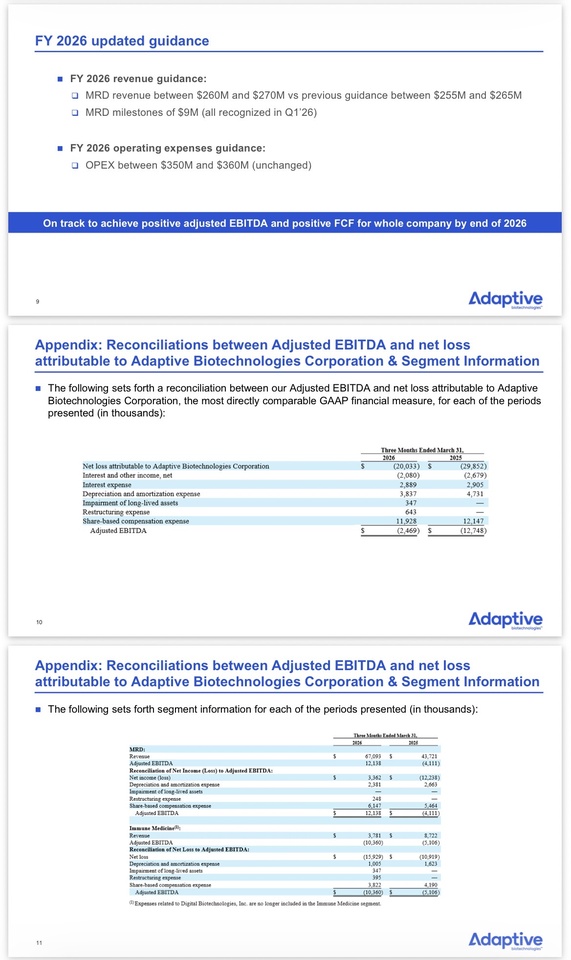
Revenue Base & Beat: Total revenue in the current Q1 2026, at $70.9 million, smashed analyst estimates by a massive 16.4%. For the full year, a core MRD forecast of $260 million to $270 million is on the table.
🚀Growth Explosion: The core MRD business is growing completely independently of economic conditions. In Q1 2026, MRD revenue surged by +53% year-over-year, driven by a +67% increase in volume for cancer tests in the U.S. private practice sector.
🚀Massive Software Margins: The sequencing gross margin climbed to a phenomenal 70.0% (+8% YoY) thanks to massive scaling. Once the labs are up and running, nearly every additional dollar of revenue flows through the income statement as pure profit.
🚀The Break-Even Point: At the corporate level, the loss has been almost completely eliminated (adjusted EBITDA in Q1 was a mere -$2.5 million). The MRD unit alone is already highly profitable (+$12.1 million in EBITDA). With the breakup set to be completed by the end of 2026, the company will become a highly profitable cash flow machine starting in 2027.
The $500 Million War Chest: With approximately $237 million in net cash from operations plus a $300 million convertible bond strategically placed in June 2026 (at a 0% coupon!), management possesses an impregnable financial fortress. Shareholder dilution is off the table for the next 10 years.
3. Why is the stock so exciting right now? 🚀
1. The catalyst for the breakout: The market is still valuing ADPT at a discount due to its past cash-burn periods. Once the spin-off of Immune Medicine is formally completed at the end of 2026, Wall Street will be forced to revalue the remaining 50% growth business using the premium multiples of high-end SaaS/diagnostics companies.
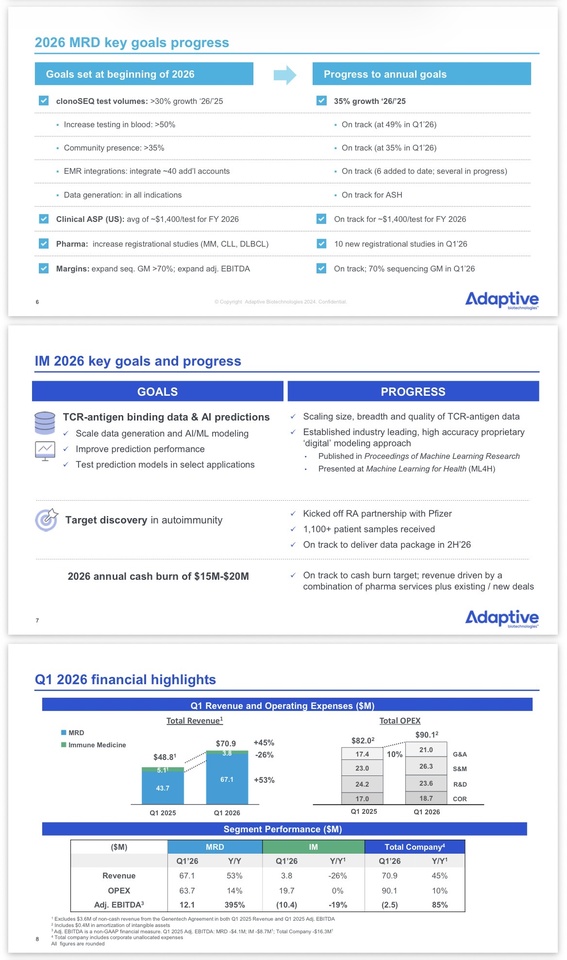
2. The Pharma Backlog Leverage: The contractually secured order backlog with pharmaceutical giants surpassed $254 million in the first half of the year (+24% YoY). This provides exceptional visibility into revenue for the next 36 months.
3. The Reimbursement Wave: More and more private and government U.S. health insurers (including Medicare) are adding clonoSEQ to their standard coverage for an increasing number of cancer types. This opens the floodgates to the mass market beyond high-end clinics.
4. Risks ⚠️
❗️Concentration risk in approval studies: If several major pharmaceutical partners were to unexpectedly halt their cancer studies, short-term data and sample revenue in the B2B segment would suffer
❗️FDA Regulatory Requirements: The FDA is currently tightening controls on so-called Lab-Developed Tests (LDTs). Adaptive is ideally positioned here thanks to its already extremely high level of clinical validation, but regulatory delays will cost time
❗️One-time restructuring costs: The physical and accounting separation of the two parts of the group will weigh on the remainder of 2026 with one-time effects
5. Reaper Rating 💀
Jack’s Verdict:
“Adaptive Biotechnologies $ADPT (-0,05 %) is the perfect example of a high-yield cash cow that was buried under a convoluted corporate structure. Anyone buying ADPT now is buying the undisputed cancer-monitoring monopoly of the future at the very moment of its great breakthrough.
Forget the classic biotech gamble, where you hope a Phase 2 pill doesn’t fail. Buy the device that everyone must use to prove the pill’s success. For years, Adaptive Biotechnologies $ADPT (-0,05 %) was, for years, the stock about which people said, “Brilliant product, but the cash burn is killing me.” With the radical M&A breakup in June 2026, management has blown away precisely that millstone. They raised $300 million via a zero-percent-interest convertible bond and spun off the unprofitable division. What remains is a flawless cancer-testing business with a 70% margin and over 50% growth. At prices around $21, the stock is simply undervalued given what it will represent starting in 2027. This is the entry point before the major institutional revaluation.”
Reaper Rating: 🔥 STRONG BUY (Diagnostics Growth / Strategic Breakup Winner)
Reaper Score: 8.4/10 (Justified by the breathtaking 70% product margin, 53% core growth, and the complete elimination of balance sheet risk through the $300 million zero-coupon refinancing in June).
@Get_Rich_Or_Die_Tryin @Raketentoni
@Tenbagger2024
@Stocktective
@schlimmschlimm
@Multibagger and, of course, all other users are warmly invited! 🫶✌️


