5Mo·

🏥 Sotera Health US - Introduction & Insight - No hype value, no value dividend compounder but great potential for scalability? 📈

Let's get started, today some cash was added to the portfolio and a new position was opened. I really thought long and hard about whether I should get in or not - now it's time.


Welcome ☢️
$SHC (-2,99 %) ☢️
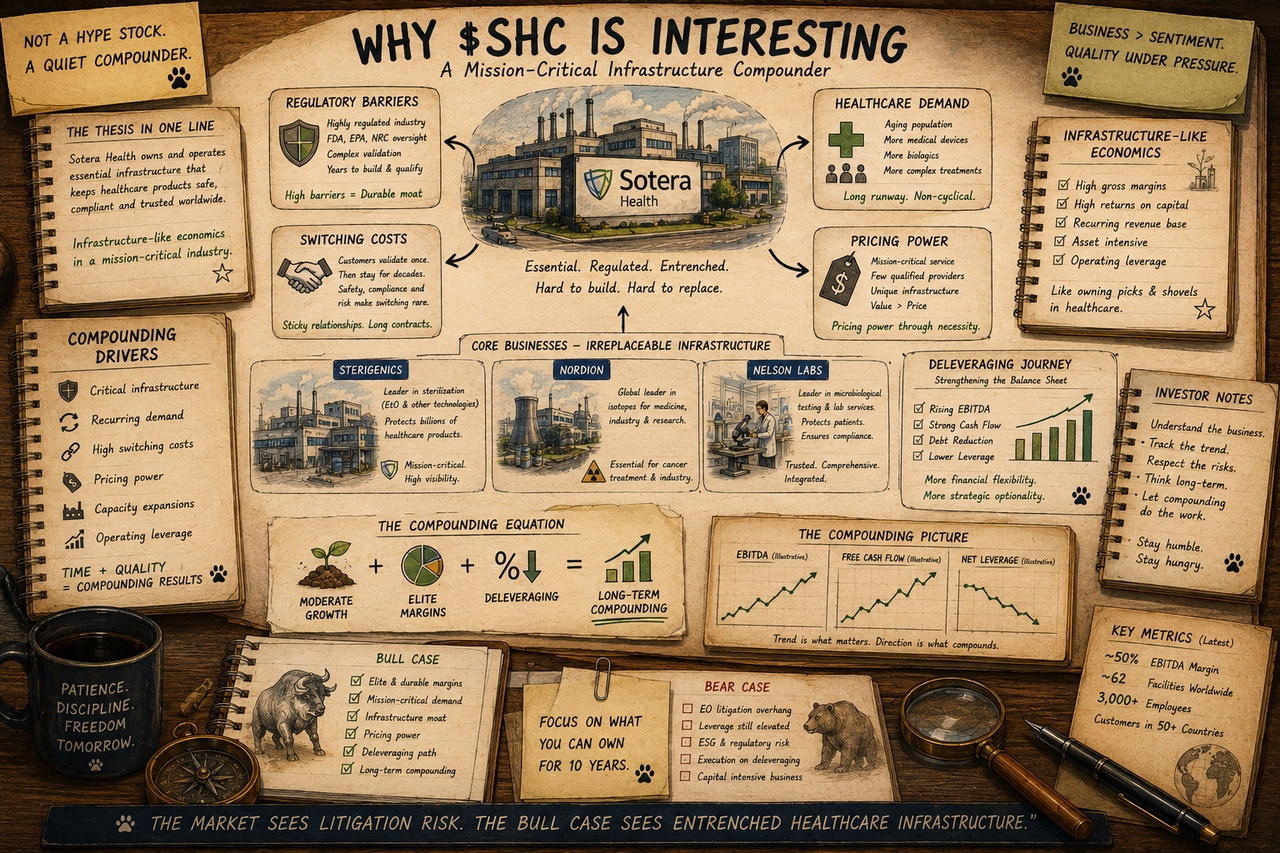
attachment

Offside boring dividend stocks, this might even arouse the interest of some people to find out what is behind this inconspicuous company.

That's why I'm giving you a brief overview of what Sotera Health is up to and why it fits well into my portfolio, at least for me.


*Please don't expect a super elaborated presentation, I'm trying to write everything myself, but I allowed myself some support with the creation of graphics - came out somehow by chance and I liked it*.


Where do we categorize $SHC (-2,99 %) classify?

This is a company in the healthcare sector and even better, which is why it is so interesting for me, a real infrastructure play in the healthcare sector.


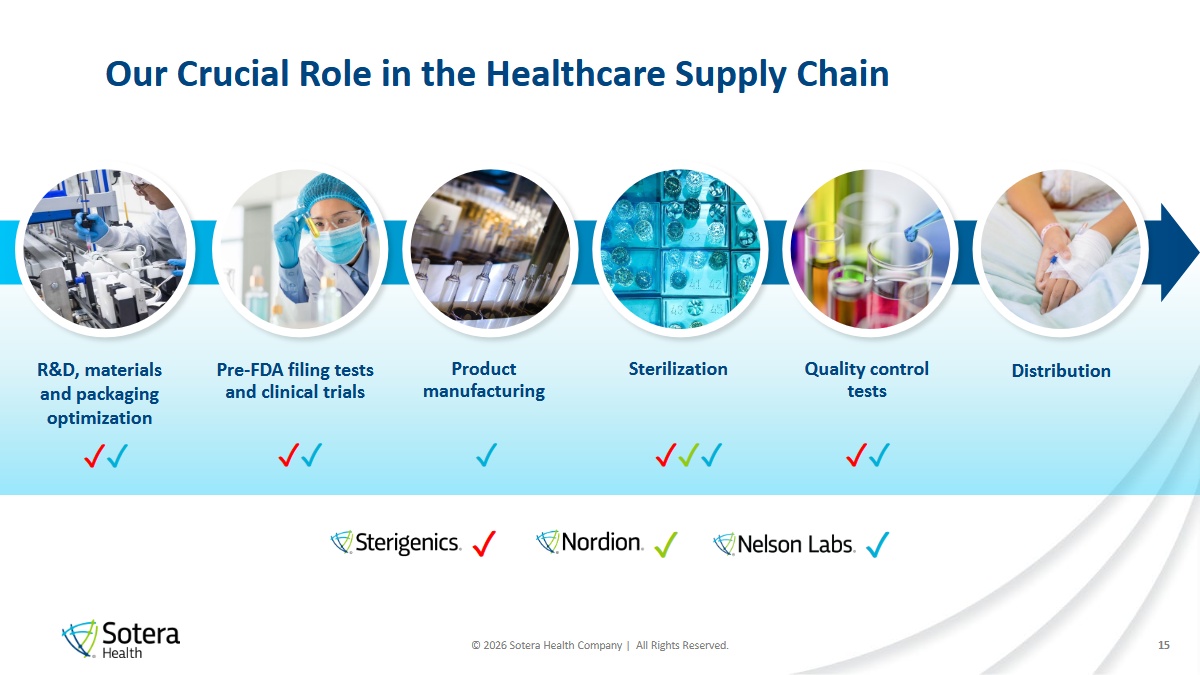
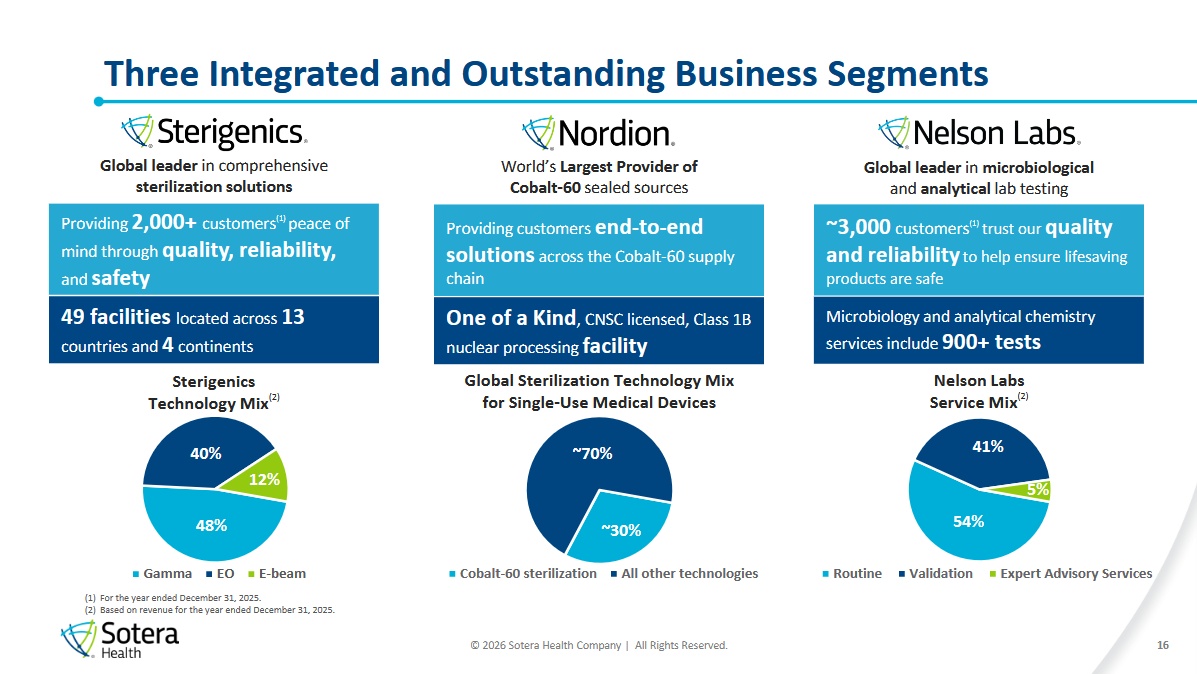
No products or hardware are sold - Sotera sterilizes, tests and supports through its 3 companies - Sterigenics, Nordion and Nelson Labs. Sterigenics, Nordion and Nelson Labs the provision of essential services worldwide to keep modern medicine running.


If you look at the following products from other manufacturers, they all have a different purpose, are essential today, but share one feature - or at least they should. or at least they should 🫚
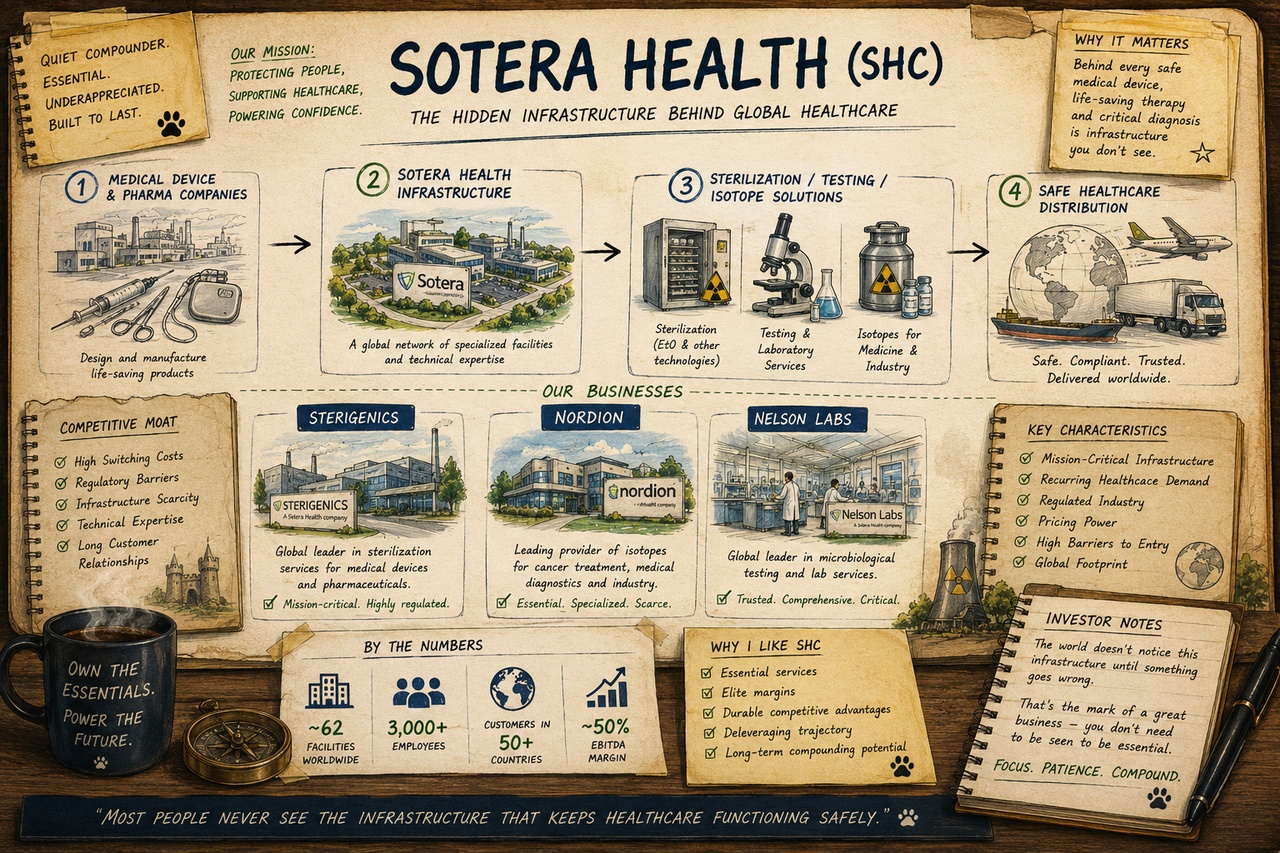

attachment
  • Surgical instruments
  • Catheters/syringes/cardiac pacemakers
  • Orthopaedic implants
  • Stents/vascular supports
  • Gloves, etc.
  • Wound care products
  • Tissue implants
  • etc...

They must be sterile be sterile! 💉 And this is where Sotera comes in, because without you, a large part of the healthcare sector would not be able to distribute its services and products safely.


The global demand for healthcare continues to grow structurally year on year and the importance of Sotera's infrastructure continues to grow with increasing demand.


  • Medical technology
  • pharmaceutical products
  • sterile supply chains
  • regulatory validation


But why is the company interesting for me? Here are a few facts that stood out for me & made me buy:


  • ~50% adj. EBITDA margin
  • ~20-23% FCF margin
  • ~20%+ operating margin
  • ~45% gross margin
  • Strong cash flow conversion
  • Net debt/EBITDA continuously improving & positive interest coverage development
  • High customer retention and real switching costs
  • High regulation & validation processes create massive barriers to entry
  • Pricing power


attachment

The massive EBITDA margin including the other figures makes it easy to see that there is a massive moat for $SHC (-2,99 %) is present.

Sotera has nested itself directly under the global healthcare system and cashes in when others want to sell their goods.

All products need to be sterilized, tested, validated which creates huge workflow bindings. Each process is individual and needs full attention, there is no real copy-paste here.


If you want to switch from Sotera to another provider, you have to:


  • Have their product validated again
  • Realign the entire process
  • Needs the regulatory OK
  • Must change their logistics
  • This results in very high costs & possible interruptions in the supply chain

attachment

In addition, anyone who wants to take Sotera by the scruff of the neck to reduce margins needs to think very carefully and bring a big wallet with them. Because the infrastructure that has been created and has to be copied is not without its costs:


  • Sterilization facilities
  • Expertise in radioactivity/gamma radiation & ethylene oxide
  • Regulatory approvals
  • Logistics systems (incoming & outgoing goods)
  • Confidence in the validation of products
  • Customer loyalty


It takes years, a lot of capital and, above all, expertise to accomplish all this.

Another advantage of Sotera is that it offers the customer a complete system. It is sterilized, tested, validated and you can supply yourself with Co-60. With $SHC (-2,99 %) there is virtually everything under one roof.

Competition is therefore rare, with $STE (-1,93 %) there is a larger player, but it is not nearly as concentrated and is unlikely to pose a major threat.
attachment

If you want to use the Rule of 40 as an evaluation, this is only possible to a limited extent with Sotera, as the growth appears low at first glance.


-> Mid single to high single digits, probably won't knock anyone's socks off.


I would $SHC (-2,99 %) But I would also look at their EBITDA margin & the Moat to see if the business is running - this is really more of an infrastructure play.

If margins remain exceptionally high or even grow, EBITDA grows faster than debt, demand remains stable and cash flows continue to scale - even moderate growth can produce a decent compounder.


-----------> Of course, there are also negatives, I can hear them from afar 👂<-----------


1) "The share price looks horrible, it's going to be a disaster" 🛝📉


In fact, the company is currently still having problems with legal proceedings.

Some products with ethylene oxide the problem here:

In high concentrations, this is considered potentially carcinogenic

The company is therefore currently suffering from the possible further lawsuits and claims for damages that the market has on its radar.


2) "Surely this nonsense has an impact on the environment!" 🦖


Like pretty much everything, yes, but Sotera's business could suffer from regulatory implementations/legislation or limit capacity.


3) "The balance sheet looks like it would $SHC (-2,99 %) rather collect debt than revenue" 🆘


Absolutely also a core risk that is not to be taken lightly, here too my pain threshold has actually already been reached. Additional or recurring costs for legal disputes or the like would of course be detrimental to de-leveraging and hamper the future.


4) "The ROIC gives my AI prompt bacterial irritable cough" 😮‍💨


Admittedly, the ROIC is not entirely bad, but in relation to the WACC it is no reason to wake up from a coma beaming with joy.


5) "If I was interested in the fucker, I could rub more salt in the wound, sterilized better anyway" 🧂


  • A good part of the Moat is based on EtO
  • Large customers (concentration)
  • Infrastructure costs
  • Less growth
  • Re-rating fails to materialize
  • Recent CEO change


---------------------------------------------------------------------------------------------------------


Why am I still investing?

No real growth play, no dividend & no clean slate because of the court 🔨


I find the discrepancy between the business quality, the moat and the market sentiment super interesting. I am clearly speculating that the business of $SHC (-2,99 %) will remain incredibly systemically relevant, that no one else will attack the business case so quickly and that the worries about the legal disputes will soon come to an end -> Re-rating from the market!


In my humble opinion, this could give the share price a real boost, as the business model is indispensable and deeply rooted in our society.

Nobody wants to stay in hospital twice, three times or even longer after a successful operation or medical treatment because there was a little green thing on the cutlery 🦠🧫


What do you think 👍or rather👎?


Questions, suggestions, corrections or AI Prompt seals of approval are always welcome in the comments.


Until then and have a nice evening everyone 👋


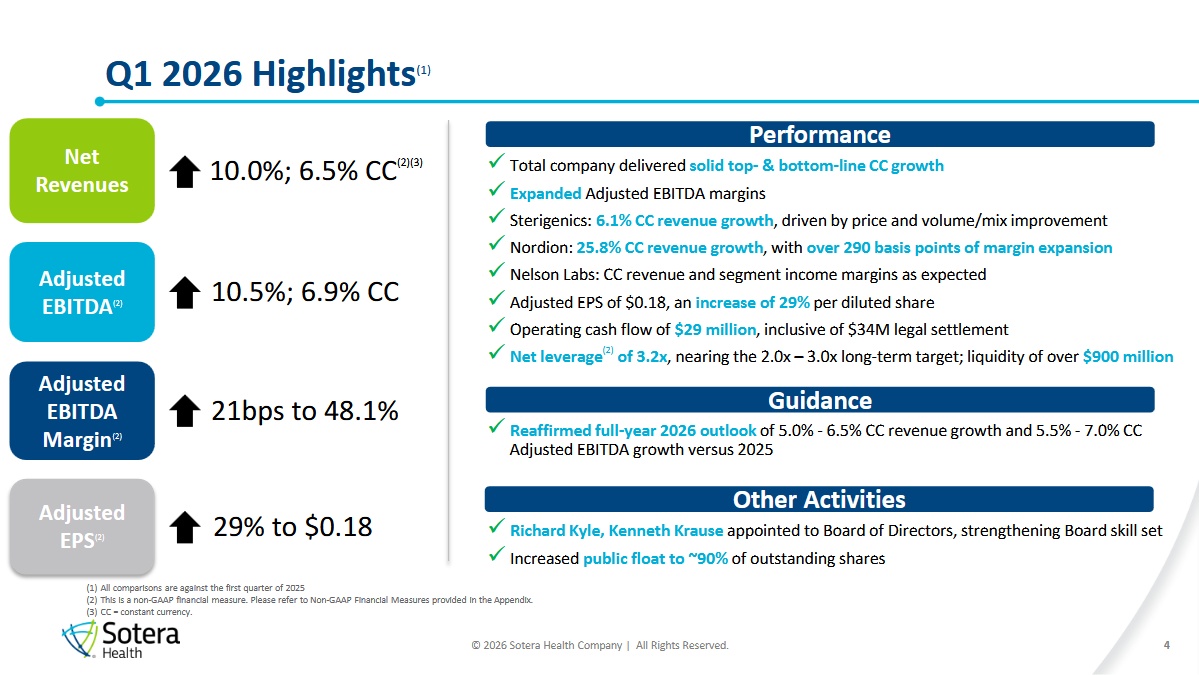
*This has probably gotten a bit out of hand, but I hope I was able to outline the company briefly and concisely for anyone who is interested. Please and above all don't take the AI-generated graphics for granted, there may have been errors or not entirely accurate data may have crept in :) The same goes for myself and my research. Otherwise, the sources are probably the usual platforms, the $SHC (-2,99 %)
Q1/26 presentation of course & AI training wheels. No investment advice by any stretch of the imagination, burn your money elsewhere 😶‍🌫️*

27.05
Sotera Health US logo
Acheté x100 à 13,78 €
1 378,33 €
13
10 Commentaires

image de profil
Thanks for the presentation. After comparing the two competitors you mentioned, I personally (and I put them directly on my watch) would definitely opt for $STE. 😅 Decisions can be so different.

Why? CEO change, debt, legal risks, regular FCF charges from compensation payments due to the ethylene oxide stuff and the shareholder structure.

Nevertheless, I wish you every success with your investment.👌🏻
•
3
•
image de profil
@Get_Rich_or_Die_Tryin Thank you also for your honest assessment! It also took me a long time to make the decision, as the worries about the market did bring some dark clouds.

But for me, $SHC is the better ratio IF they continue to follow their path, of course. Get out of debt, maintain their dominance and avoid any more catastrophic legal disputes. I think a solid foundation has been laid here in recent years, mainly thanks to the work of the previous CEO.

The interesting thing about Sotera is that despite such high burdens, they are stubborn and the figures speak for themselves. Although the FCF margin is under pressure, it is still very good :)

Edit:
At $STE the EBITDA is unfortunately much worse, probably because the day-to-day business is much more cost-intensive. The FCF margin also lags behind $SHC. For me, the only arguments in favor of Steris were the larger market cap, a certain "security" and the slightly higher YoY growth. But honestly, with an almost 50% worse EBITDA margin, this could be smoked very quickly 😅

It's also interesting that last time you were leaning more towards specialized companies. But here you would prefer the play that has several construction sites? 😁

But yes, there are currently some points that could gnaw at Sotera, but that could also go in the other direction.
•
3
•
image de profil
@Stocktective It always depends on whether I prefer the Pure Play or the broader Generalist. In a direct comparison here, I would lean more towards the "more solid" generalist due to the disruptive factors, which I still don't think have been eliminated and are already serious (since I didn't know either of them beforehand, both had the same starting conditions for me).

The most important thing for me, however, is: what will stick at the end? In comparison, Sotera's FCF margin is around 5bp higher, that's right (not counting the EBIT margin, which is of course top notch, but that doesn't end up as cash on a one-to-one basis). However, if the FCF is regularly burdened at irregular intervals by compensation payments (which inevitably squeezes the margin), this indicates to me as an investor that real cash flows cannot be reliably predicted and I simply lack the imagination for real, long-term compounder potential.

And I really don't like that.🤷🏼‍♂️😅
•
1
•
image de profil
@Get_Rich_or_Die_Tryin I can well understand that, yes, the litigation risks hang like a sword of Damocles over $SHC and that will remain the case for some time until it disappears, but I think it will. Of course, this will also have an impact on the share price, which won't really get going for the time being.

However, the course has been set well and the management is acting very conservatively, allocating capital sensibly and working in a shareholder-friendly manner. After the PE IPO, of course, things still have to settle down, but the last massive second offerings have been sold.

Let's see what happens in the future, I'm curious :)
•
2
•
image de profil
Thanks for the introduction my dear.
I'll just run Jack's analysis through the comments

Hello Stocktective, Jack here ✌️schön that we have the pleasure. Are you ready for the execution?

The indestructible duopoly in a stranglehold:

Sotera Health operates not in the spotlight, but as a critical, systemically important infrastructure provider for the healthcare industry. With its Sterigenics and Nordion segments, the company, together with its competitor Steris, operates a de facto duopoly for the sterilization of medical devices and pharmaceutical packaging in the USA. Anyone who wants to bring surgical instruments or syringes onto the market cannot avoid Sotera's validation and irradiation systems for regulatory purposes.

🛠️DNA-Check
Reliable operating margins: The company boasts a GAAP operating margin of around 24.4% and stable gross margins of 55.5%.
Solid cash flow generation: Sotera converts the business into a real FCF margin of c. 17.1% (adjusted for SBC and non-recurring items), underlining the inherent strength of the operating model.
Capital efficiency with a flaw: Normalized ROIC of 13.25% is above the cost of capital but misses our hard 20% quality threshold due to a goodwill-heavy balance sheet.
Growth resilience: The historical 5-year EPS CAGR of a meagre ~5.4% proves that organic growth is not a sure-fire success.

🚀 Growth levers & catalysts
Extreme switching costs: Once a medical device has been validated by the FDA in combination with a Sotera system, the customer virtually never switches providers. The risk of production downtime blocks any change of supplier.
Demographic tailwind: The increasing demand for medical procedures worldwide ensures crisis-proof, volume-based base growth of a forecast 5.0% to 6.5% for the full year 2026.
Deleveraging potential: If the management succeeds in rapidly reducing the current level of debt (net leverage of ~3.2x EBITDA) through strong cash generation, a significant multiple rating beckons.

⚠️ Valuation & risks
The plaintiff kryptonite: The sterilizing gases (ethylene oxide) are the focus of cancer allegations. Even after the expensive Illinois settlements, the US plaintiff industry threatens permanent, unpredictable special charges ($65m in FY25 alone). The Moat protects against competition, but not against lawyers.
Crushing debt burden: Over $2.2 billion in long-term debt weighs on the balance sheet. The current interest rate environment makes refinancing expensive in the coming years and puts pressure on net FCF.
Symmetrical upside: A reverse DCF shows that the market is pricing in annual FCF growth of 7.2% at the current price of $15.55. This is fair, but leaves little room for maneuver. This is fair, but leaves little room for operational disappointment.

🎯My verdict for Sotera Health:
"Sotera Health is an operational money printing machine stuck in a legal and financial straitjacket. The business model is almost unkillable thanks to the regulatory duopoly, but the combination of plaintiff risks and high leverage requires a thick margin of safety. It is not a core investment, but a defensive specialty stock. If you can sit out the unpredictable US litigation component, you can wait for the setback in a disciplined manner."

Reaper rating: BEOBACHTEN
Reaper Score: 5.2/10
•
3
•
image de profil
@Aktienhauptmeister thanks for the feedback and playing through :)
Always interesting to see what or how it is filtered/rated.

I pretty much neglected EPS here, for example, as it's not really the deciding factor and adjusted is probably more like 10% CAGR if you try to average it out.

I focused more on EV/EBITDA & FCF, as well as the margins themselves and the leverage trend. Robust cash flow is already in place and strongly implemented.
•
2
•
image de profil
@Stocktective of course I wish you every success with your investment 👍 keep us up to date 😬
•
2
•
image de profil
@Stocktective I would be interested in your assessment of my introduction to UCB 🤔
••
Thank you for the insight and your work ☺️
•
1
•
image de profil
@Eschi75 I would love to :)
•
1
•
Participez à la conversation